- Who files
- Ultimate purchasers, registered vendors and card issuers
- Filed with
- The income tax return
- Due
- With the income tax return
- Form revision
- 2025 (instructions Dec. 10, 2025)
- Pages
- 4
At a glance
Form 4136 takes back the federal excise tax that was in the price of fuel you used in a use the Code does not tax, as a credit on your income tax return. The instructions list four uses: the alternative fuel credit, “A credit for certain nontaxable uses (or sales) of fuel during your income tax year.”, a credit for blending a diesel-water fuel emulsion, and “A credit for exporting dyed fuels or gasoline blendstocks.” The Form 4136 guide explains who qualifies and how it fits with the other claim routes; this page walks the 2025 form line by line.
- Who files. The ultimate purchaser that used the fuel (farms, off-highway business equipment, exporters, commercial fishing and the other uses), plus registered ultimate vendors, registered credit card issuers and emulsion blenders on their own lines. Partnerships do not file it; they pass the details to partners on Schedule K-1.
- When. With the income tax return for the year the fuel was used (or sold, for a vendor). For tax year 2025, “The IRS will begin accepting e-filed tax year 2025 returns that include Form 4136, Credit for Federal Tax Paid on Fuels, on Feb. 22, 2026.”
- Where. Attached to the income tax return, not sent to the excise unit; the total goes on line 17 and then to the return.
- Form revision. Form 4136 (2025), with the Instructions for Form 4136 (2025). It has four pages: Part I on page 1 and the Part II credit lines on pages 1 to 4. The 2026 revision was not posted as of November 2026.
- Records. “You must keep records to support any credits claimed on this return for at least 3 years from the date the return is due or filed, whichever is later.”
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
Name and Part I
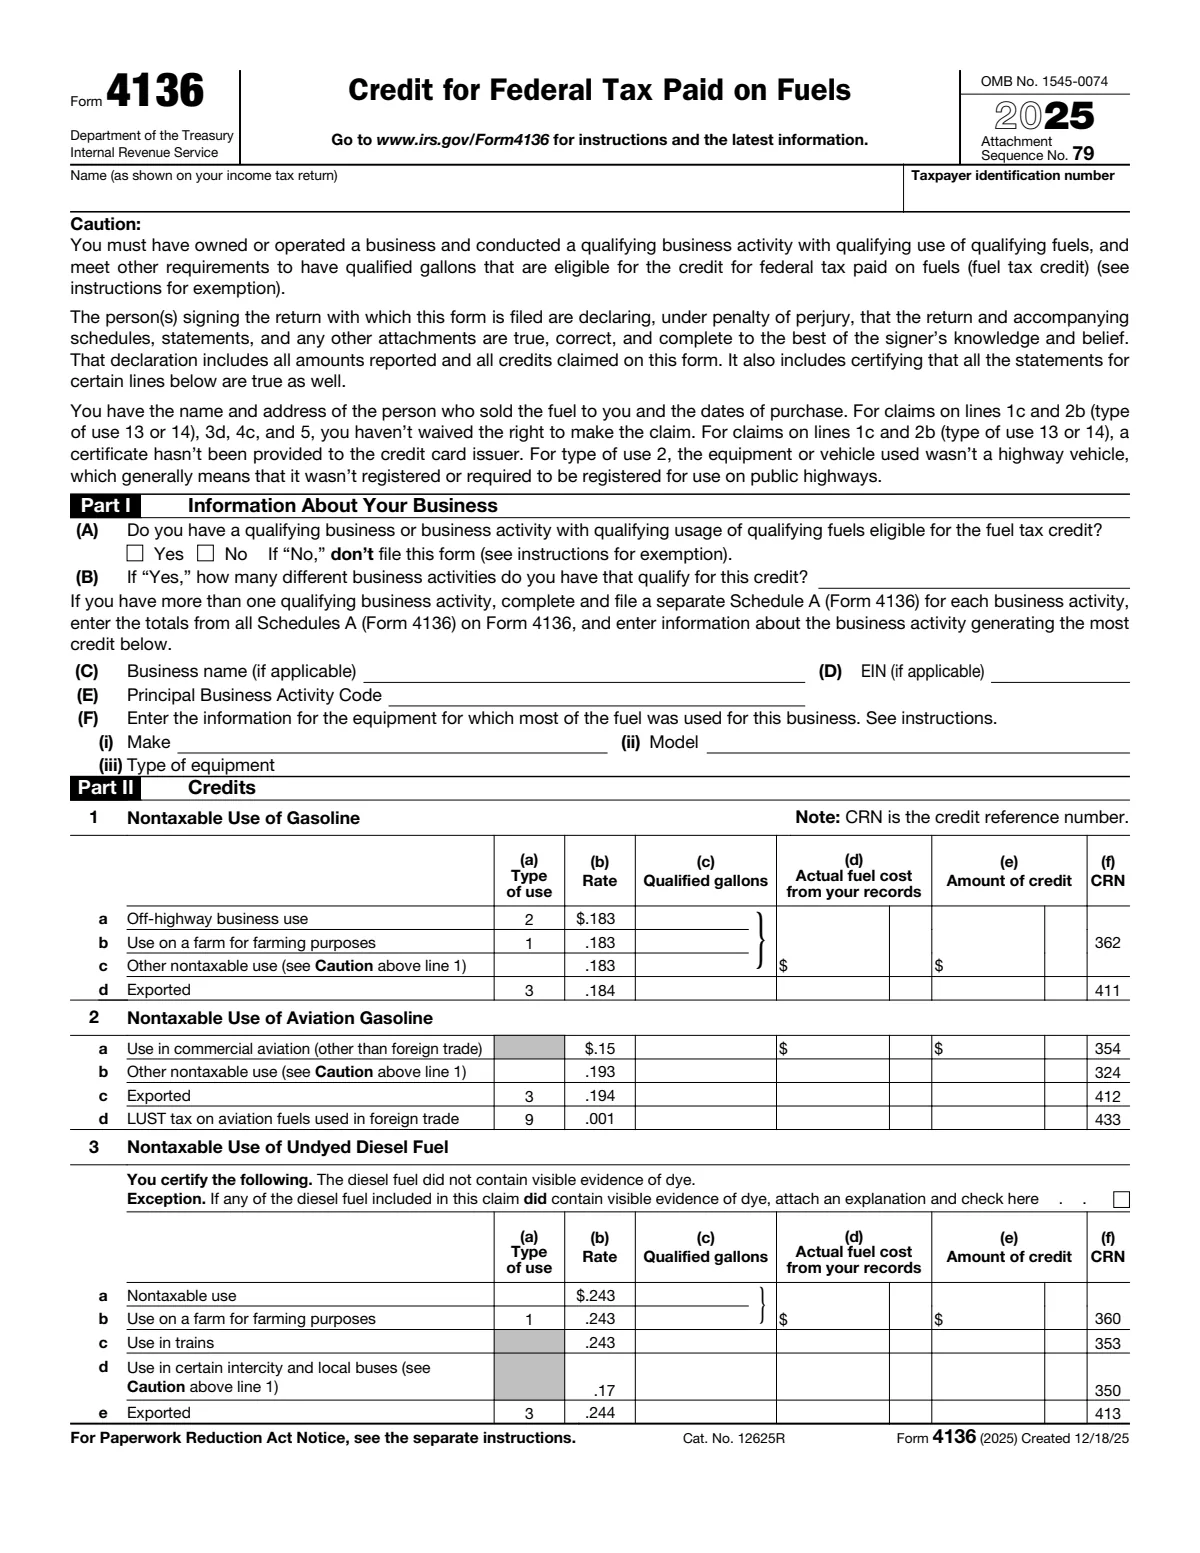
Part I is new for 2025. It asks whether you have a qualifying business at all, how many qualifying activities you run, and which equipment burned most of the fuel. The form opens with a caution: “You must have owned or operated a business and conducted a qualifying business activity with qualifying use of qualifying fuels”. Personal driving never qualifies: “A taxpayer who uses gasoline in their vehicle for personal use, commuting to work, or driving for ride sharing services” does not qualify for the credit.
| Line | Label | What goes there |
|---|---|---|
| Name | Name (as shown on your income tax return) | Form 4136 is an attachment, not a stand-alone claim: use the name on the Form 1040, 1120, 1120-S, 1041 or other income tax return it is filed with. Partnerships do not file it at all (see line 17). |
| TIN | Taxpayer identification number | The same number as on the return. A business EIN asked for separately goes on line D. |
| A | (A) Do you have a qualifying business or business activity with qualifying usage of qualifying fuels eligible for the fuel tax credit? | New for 2025. “If you answer ‘No’ on line A, you aren't eligible for the credit, don't complete Form 4136.” The exception is undyed kerosene bought (other than from a blocked pump) and used at home for heating, lighting or cooking: answer Yes, skip lines B to F and go to Part II. |
| B | (B) If “Yes,” how many different business activities do you have that qualify for this credit? | With two or more, “you must use a separate Schedule A (Form 4136) for each business or business activity.” Add the Schedule A totals into Part II of this form and describe the activity that produces the most credit on lines C to F. |
| C | (C) Business name (if applicable) | The trade or business name of the activity generating the most credit (farming, construction and the like), if different from the name at the top. |
| D | (D) EIN (if applicable) | “Enter on line D the EIN that was issued to you on Form SS-4. Don't enter your SSN on this line.” No EIN: leave it blank. |
| E | (E) Principal Business Activity Code | “Enter on line E the six-digit principal business activity code.” Use the same code as the income tax return's business schedule. |
| F | (F) Enter the information for the equipment for which most of the fuel was used for this business. | Make, model and type of the equipment “which used most of the fuel that provided your principal source of income on the business reported on line C.” A tractor, a generator, a fishing boat or a loader, for example: equipment, not a highway vehicle, for off-highway business use. |
How a credit line works
Every Part II line has the same six columns. You choose the line by fuel and use, enter the type of use number where the line asks for one, the gallons, the actual fuel cost from your records, and the credit. “Generally, multiply the rate by the number of gallons.” The rates and CRNs below are read from the 2025 form itself. Most are the tax rate less the 0.1 cent LUST tax, which is generally not refunded except on the foreign trade and export lines.
Form 4136 and Instructions (2025). Keep the fuel invoices and cost records; do not attach them.
| Box | Label | What goes there |
|---|---|---|
| cols | Columns (a) Type of use, (b) Rate, (c) Qualified gallons, (d) Actual fuel cost from your records, (e) Amount of credit, (f) CRN | Column (a) takes a number from the Type of Use Table (below). Column (b) is printed. Column (c) is gallons (or gasoline or diesel gallon equivalents for CNG, LPG and LNG on line 11). Column (d) is new for 2025: the actual fuel cost from your records; do not attach receipts, keep them. Column (e) is gallons times rate: “Enter the result (or the combined result, as indicated by the brackets) in the Amount of credit column.” Column (f) is the printed credit reference number (CRN). |
Lines 1 to 5: the ultimate purchaser
Lines 1 to 5 are the buyer's own claims for gasoline, aviation gasoline, undyed diesel, undyed kerosene and kerosene used in aviation. On each, the ultimate purchaser is the claimant; for gasoline, “The ultimate purchaser of the gasoline is the only person eligible to make this claim.” A claim for a state or local government's use (types of use 13 and 14) follows an order of priority: the registered credit card issuer first, then the registered ultimate vendor if the buyer waives the claim, and the buyer only when neither can claim. The exported lines (1d, 2c, 3e, 4d, 14b, 16a and 16b) need proof of export: “Taxpayers making a claim for exported taxable fuel must keep proof of exportation with their records.”
| Line | Label | What goes there |
|---|---|---|
| 1a | Off-highway business use | Gasoline used “for a business use other than in a highway vehicle registered (or required to be registered) for highway use (type of use 2).” Not a motorboat, unless commercial fishing. Rate printed: $.183 a gallon. CRN: 362. |
| 1b | Use on a farm for farming purposes | Gasoline used on a farm for farming purposes (type of use 1). Farmers also read Pub. 225. Rate printed: $.183 a gallon. CRN: 362. |
| 1c | Other nontaxable use (see Caution above line 1) | For type of use 4, 5, 7, 11, 13, 14 or 15. “For type of use 13 or 14, the claimant must not have waived the right to make a claim.” Lines 1a to 1c are bracketed: one combined amount in column (e). Rate printed: $.183 a gallon. CRN: 362. |
| 1d | Exported | Gasoline exported during the period (type of use 3). Keep the export bill of lading or another proof the instructions list. Rate printed: $.184 a gallon. CRN: 411. |
| 2a | Use in commercial aviation (other than foreign trade) | “The ultimate purchaser of the aviation gasoline is the only person eligible to make this claim.” Rate printed: $.15 a gallon. CRN: 354. |
| 2b | Other nontaxable use (see Caution above line 1) | Type of use 1, 2, 9, 10, 11, 13, 14 or 15. “Use line 2b to make a claim for aviation gasoline used outside the propulsion system of an aircraft.” Rate printed: $.193 a gallon. CRN: 324. |
| 2c | Exported | Aviation gasoline exported during the period (type of use 3). Rate printed: $.194 a gallon. CRN: 412. |
| 2d | LUST tax on aviation fuels used in foreign trade | Type of use 9. The leaking underground storage tank (LUST) tax of $.001 a gallon on aviation fuel used in foreign trade. Rate printed: $.001 a gallon. CRN: 433. |
| 3-dye | Exception. If any of the diesel fuel included in this claim did contain visible evidence of dye, attach an explanation and check here | Line 3 is for undyed diesel. By claiming you certify “The diesel fuel did not contain visible evidence of dye.” Dyed diesel was never taxed, so there is nothing to claim on it; the box is for the odd case of a claim gallon that showed dye, with an explanation attached. |
| 3a | Nontaxable use | “The ultimate purchaser of the diesel fuel is the only person eligible to make this claim.” Type of use 2, 6, 7, 8, 11, 13, 14 or 15; “Type of use 8 includes use as heating oil and use in a motorboat.” Rate printed: $.243 a gallon. CRN: 360. |
| 3b | Use on a farm for farming purposes | Undyed diesel used on a farm for farming purposes (type of use 1). Lines 3a and 3b share one amount and one CRN. Rate printed: $.243 a gallon. CRN: 360. |
| 3c | Use in trains | Undyed diesel used in a train (the rate reflects the 0.1 cent LUST tax that is not refunded). Rate printed: $.243 a gallon. CRN: 353. |
| 3d | Use in certain intercity and local buses (see | Certain intercity and local buses (type of use 5). The claimant must not have waived the right to make the claim to the vendor. Rate printed: $.17 a gallon. CRN: 350. |
| 3e | Exported | Undyed diesel exported during the period (type of use 3). Rate printed: $.244 a gallon. CRN: 413. |
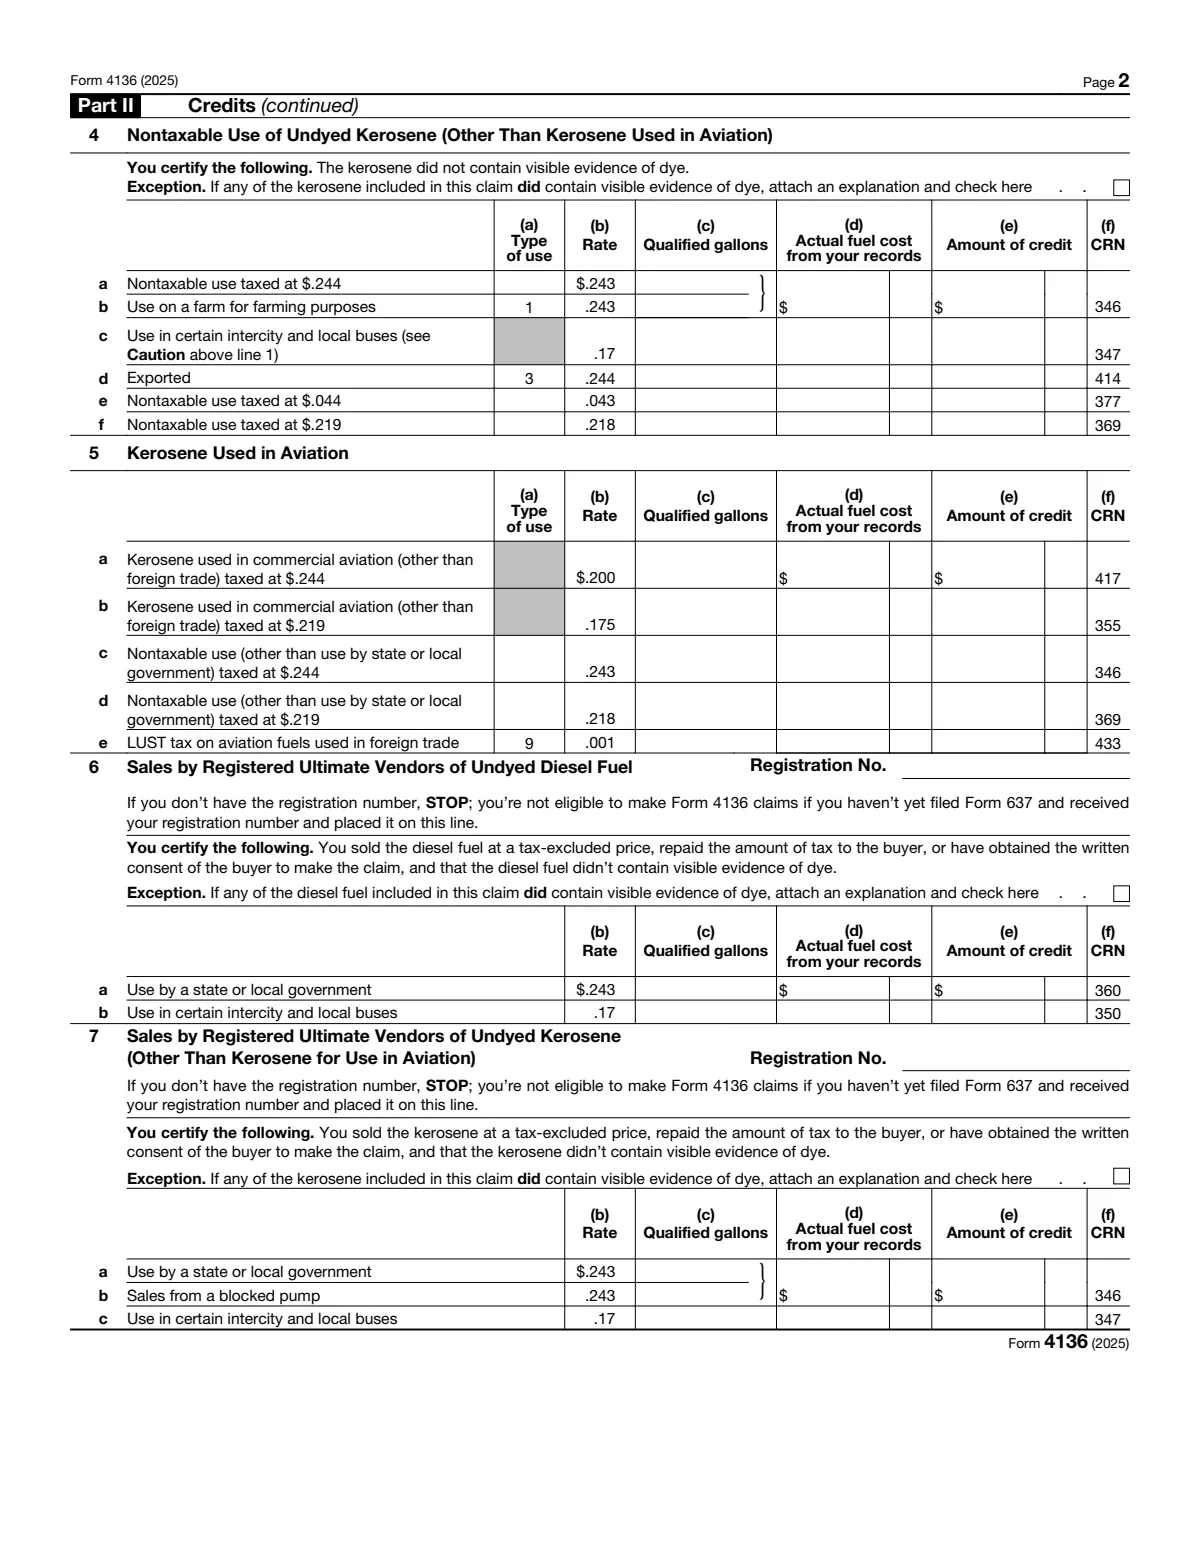
| 4-dye | The kerosene did not contain visible evidence of dye. | The same certification as line 3, for undyed kerosene other than kerosene used in aviation. |
| 4a | Nontaxable use taxed at $.244 | Type of use 2, 6, 7, 8, 11, 13, 14 or 15. Home use: enter 8 in column (a), the gallons in column (c), and multiply by $.243; if it is your only credit, carry it to line 17 and to Schedule 3 (Form 1040), line 12. Rate printed: $.243 a gallon. CRN: 346. |
| 4b | Use on a farm for farming purposes | “Line 4b doesn't include claims for kerosene used in aviation for farming purposes;” those go on line 5. Rate printed: $.243 a gallon. CRN: 346. |
| 4c | Use in certain intercity and local buses (see | Certain intercity and local buses. The claimant must not have waived the right to make the claim. Rate printed: $.17 a gallon. CRN: 347. |
| 4d | Exported | Undyed kerosene exported during the period (type of use 3). Rate printed: $.244 a gallon. CRN: 414. |
| 4e | Nontaxable use taxed at $.044 | Kerosene taxed at the reduced $.044 rate and used in off-highway business use (type of use 2). Rate printed: $.043 a gallon. CRN: 377. |
| 4f | Nontaxable use taxed at $.219 | Kerosene taxed at $.219 and used in off-highway business use (type of use 2). Rate printed: $.218 a gallon. CRN: 369. |
| 5a | Kerosene used in commercial aviation (other than | For kerosene taxed at $.244 and used in commercial aviation (other than foreign trade). Mixed commercial and noncommercial buyers follow Notice 2005-80, section 3(e)(3). Rate printed: $.200 a gallon. CRN: 417. |
| 5b | foreign trade) taxed at $.219 | Commercial aviation (other than foreign trade) for kerosene taxed at $.219. Rate printed: $.175 a gallon. CRN: 355. |
| 5c | Nontaxable use (other than use by state or local | Noncommercial aviation in type of use 1, 9, 10, 11, 13, 15 or 16, for kerosene taxed at $.244. State and local government use is claimed by the vendor or card issuer instead. Rate printed: $.243 a gallon. CRN: 346. |
| 5d | government) taxed at $.219 | The same uses as line 5c, for kerosene taxed at $.219. Rate printed: $.218 a gallon. CRN: 369. |
| 5e | LUST tax on aviation fuels used in foreign trade | Type of use 9. “This claim is made in addition to the claim made on lines 5c and 5d for type of use 9.” CRN: 433. |
Lines 6 to 8 and 13: vendors and card issuers
Lines 6, 7, 8 and 13 belong to sellers, not users. A registered ultimate vendor claims the tax on fuel it sold to a state or local government, a bus operator or an aviation buyer, and a registered credit card issuer claims on government card purchases. Each line starts with a registration number box and a stop sign: “If you don't have the registration number, STOP; you're not eligible to make Form 4136 claims if you haven't yet filed Form 637 and received” the number. Gasoline is different: “Form 4136 can't be used by ultimate vendors to make gasoline claims.” Vendors of gasoline and most vendors of the other fuels claim on Form 8849 (Schedule 2) or Form 720 Schedule C during the year; see the Form 8849 guide and the Form 637 registration guide.
| Line | Label | What goes there |
|---|---|---|
| 6 | 6 Sales by Registered Ultimate Vendors of Undyed Diesel Fuel | Ultimate vendors must be registered: “Enter your registration number, including the prefix, on the applicable line for your claim.” Line 6a uses the UV registration and line 6b the UB registration. If you are not registered, apply on Form 637 first. |
| 6-dye | You certify the following. You sold the diesel fuel at a tax-excluded price, repaid the amount of tax to the buyer, or have obtained the written | By claiming, the vendor certifies it sold at a tax-excluded price, repaid the tax to the buyer or has the buyer's written consent, and that the diesel showed no dye. Check the box only with an explanation if some did. |
| 6a | Use by a state or local government | The registered ultimate vendor is the only claimant and must hold the buyer's certificate (Model Certificate P in Pub. 510). Attach a statement with the name and TIN of each government unit and the gallons sold to each. Rate printed: $.243 a gallon. CRN: 360. |
| 6b | Use in certain intercity and local buses | The vendor claims only if the buyer waives the right by giving an unexpired waiver (Model Waiver N in Pub. 510). Enter the UB registration number. Rate printed: $.17 a gallon. CRN: 350. |
| 7 | 7 Sales by Registered Ultimate Vendors of Undyed Kerosene | Enter the UV or UP registration number for lines 7a and 7b and the UB number for line 7c. “You can't make a claim on lines 6 through 8 if you haven't received your IRS-issued Form 637 registration number and placed it on the applicable lines.” |
| 7-dye | You certify the following. You sold the kerosene at a tax-excluded price, repaid the amount of tax to the buyer, or have obtained the written | Tax-excluded price, repayment or written consent, and no visible dye; check the box with an explanation if some kerosene showed dye. |
| 7a | Use by a state or local government | The vendor is the only claimant, with Model Certificate P from the buyer and a statement of each government unit's name, TIN and gallons. Rate printed: $.243 a gallon. CRN: 346. |
| 7b | Sales from a blocked pump | Kerosene sold from a blocked pump. The claimant must have a statement, if required, with the date of sale, the buyer's name and address and the gallons. Rate printed: $.243 a gallon. CRN: 346. |
| 7c | Use in certain intercity and local buses | As on line 6b: only with the buyer's unexpired waiver. Enter the UB registration number. Rate printed: $.17 a gallon. CRN: 347. |
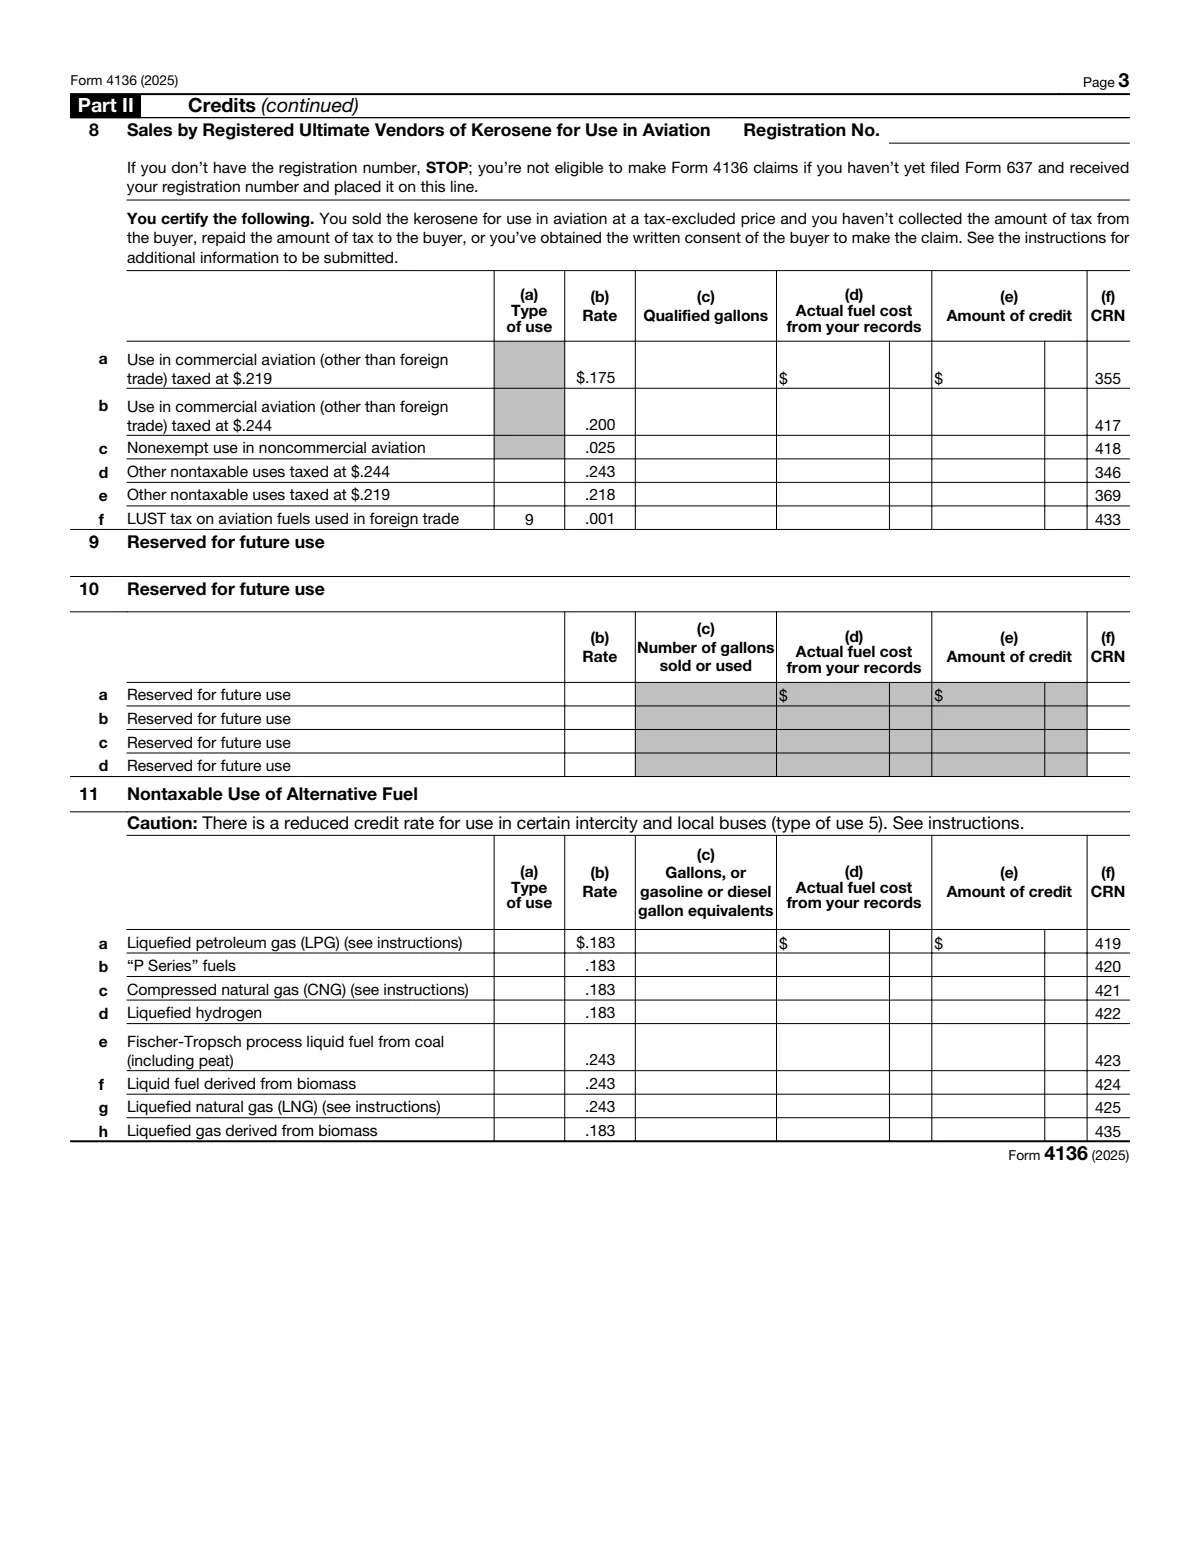
| 8 | 8 Sales by Registered Ultimate Vendors of Kerosene for Use in Aviation | Enter the UA registration number (UV if the sale was for type of use 14, a state or local government). |
| 8-cert | You certify the following. You sold the kerosene for use in aviation at a tax-excluded price and you haven't collected the amount of tax from | The aviation version of the vendor certification. Waivers come from the buyer: Model Waiver L, or Model Certificate Q for line 8c. |
| 8a | Use in commercial aviation (other than foreign | “The registered ultimate vendor of the kerosene sold for use in commercial aviation is eligible to make this claim only if the buyer waives the right by providing the registered ultimate vendor with an unexpired waiver.” Rate printed: $.175 a gallon. CRN: 355. |
| 8b | trade) taxed at $.244 | Commercial aviation (other than foreign trade) for kerosene taxed at $.244, with Model Waiver L. Rate printed: $.200 a gallon. CRN: 417. |
| 8c | Nonexempt use in noncommercial aviation | The vendor is the only claimant for kerosene sold for nonexempt noncommercial aviation, and must hold Model Certificate Q. Rate printed: $.025 a gallon. CRN: 418. |
| 8d | Other nontaxable uses taxed at $.244 | Noncommercial aviation for type of use 1, 9, 10, 11, 13, 14, 15 or 16, with the buyer's Model Waiver L (Model Certificate P for type of use 14). Rate printed: $.243 a gallon. CRN: 346. |
| 8e | Other nontaxable uses taxed at $.219 | The same uses as line 8d, for kerosene taxed at $.219. Rate printed: $.218 a gallon. CRN: 369. |
| 8f | LUST tax on aviation fuels used in foreign trade | Type of use 9; “This claim is made in addition to the claim made on lines 8d and 8e for type of use 9.” Rate printed: $.001 a gallon. CRN: 433. |
| 13 | 13 Registered Credit Card Issuers | “Enter your CC registration number in the space provided.” The card issuer claims only if it is registered, has not collected the tax from the buyer (or has its consent), has repaid or will repay the vendor, and holds an unexpired Model Certificate R. |
| 13a | Diesel fuel sold for the exclusive use of a state or local | Purchased with a credit card issued to the ultimate purchaser for the exclusive use of a state or local government (including essential government use by an Indian tribal government). “If any of these conditions isn't met, the credit card issuer must collect the tax from the ultimate purchaser and only the ultimate purchaser can make the claim.” Rate printed: $.243 a gallon. CRN: 360. |
| 13b | Kerosene sold for the exclusive use of a state or local | Kerosene sold on the issuer's card for a government's exclusive use. Rate printed: $.243 a gallon. CRN: 346. |
| 13c | Kerosene for use in aviation sold for the exclusive use of a | Printed for kerosene taxed at $.219. “For line 13c, if the kerosene was taxed at $.244, the claim rate is $.243.” Write "Taxed at $.244" to the left of column (b) and enter $.243. Rate printed: $.218 a gallon. CRN: 369. |
Lines 9 to 17
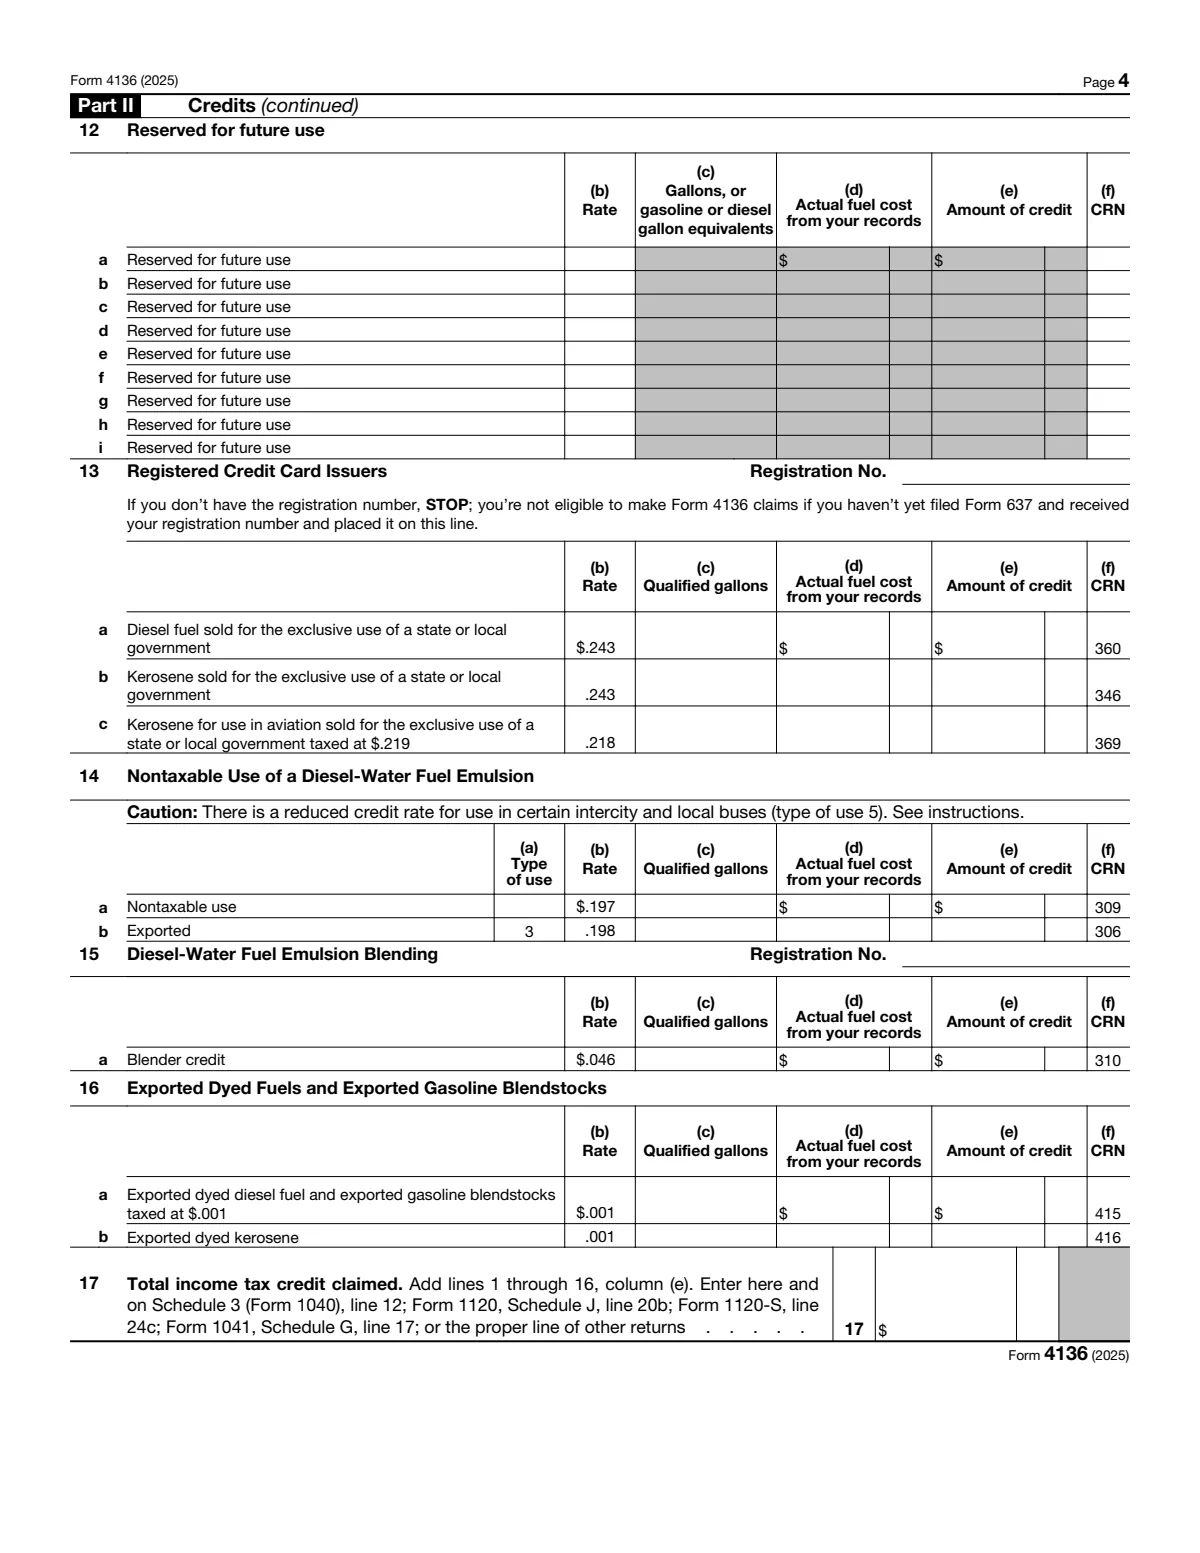
The back half of the form holds the alternative fuel lines, the closed mixture credits, the diesel-water fuel emulsion lines, exported dyed fuel and the total. Lines 9, 10 and 12 are reserved on the 2025 form because the credits behind them ended after 2024; leave them blank.
| Line | Label | What goes there |
|---|---|---|
| 9 | 9 Reserved for future use | Reserved. Leave it blank. |
| 10 | 10 Reserved for future use | “The section 6426/6427 credits/refunds for mixtures of biodiesel, agri-biodiesel, and renewable diesel expired for sales, uses, or removals after 2024.” Lines 10a to 10c are reserved, and line 10d (sustainable aviation fuel) too: “You can't claim SAF credit on Form 4136 after 2024.” |
| 11 | 11 Nontaxable Use of Alternative Fuel | “The ultimate purchaser of the taxed alternative fuel is the only person eligible to make this claim.” Allowed uses: type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15. For type of use 5 (buses), write "Bus" to the left of column (a) and enter the lower claim rate from the instructions' table. |
| 11a | Liquefied petroleum gas (LPG) (see instructions) | Enter GGE in column (c): the instructions define a GGE of LPG as 5.75 pounds or 1.353 gallons. Their bus example: “10,000 gallons of LPG ÷ 1.353 = 7,391 GGE x $0.109 = $805.62 claim amount.” Rate printed: $.183 a gallon. CRN: 419. |
| 11b | “P Series” fuels | P Series fuels used in a nontaxable use. Rate printed: $.183 a gallon. CRN: 420. |
| 11c | Compressed natural gas (CNG) (see instructions) | Compressed natural gas, entered in gasoline gallon equivalents. Rate printed: $.183 a gallon. CRN: 421. |
| 11d | Liquefied hydrogen | Liquefied hydrogen used in a nontaxable use. Rate printed: $.183 a gallon. CRN: 422. |
| 11e | Fischer-Tropsch process liquid fuel from coal | Liquid fuel from coal (including peat) by the Fischer-Tropsch process. Rate printed: $.243 a gallon. CRN: 423. |
| 11f | Liquid fuel derived from biomass | Liquid fuel derived from biomass used in a nontaxable use. Rate printed: $.243 a gallon. CRN: 424. |
| 11g | Liquefied natural gas (LNG) (see instructions) | Liquefied natural gas, entered in diesel gallon equivalents. Rate printed: $.243 a gallon. CRN: 425. |
| 11h | Liquefied gas derived from biomass | Liquefied gas derived from biomass used in a nontaxable use. Rate printed: $.183 a gallon. CRN: 435. |
| 12 | 12 Reserved for future use | The section 6426 and 6427 alternative fuel and alternative fuel mixture credits “expired for sales, uses, or removals after 2024. Part II, lines 12a through 12i, are reserved for future use.” |
| 14 | 14 Nontaxable Use of a Diesel-Water Fuel Emulsion | “The ultimate purchaser of the diesel-water fuel emulsion is the only person eligible to make this claim.” For type of use 5, write "Bus" and use the $.124 rate. |
| 14a | Nontaxable use | Type of use 1, 2, 5, 6, 7, 8, 11, 13, 14 or 15. Rate printed: $.197 a gallon. CRN: 309. |
| 14b | Exported | Diesel-water fuel emulsion exported during the period (type of use 3). Rate printed: $.198 a gallon. CRN: 306. |
| 15 | 15 Diesel-Water Fuel Emulsion Blending | “Enter your M registration number in the space provided.” The blender attaches a statement certifying at least 14% water, an EPA-registered additive, undyed diesel taxed at $.244, and use or sale in the blender's business. |
| 15a | Blender credit | “The person that produced (the blender) and sold or used the diesel-water fuel emulsion is the only person eligible to make this claim.” Rate printed: $.046 a gallon. CRN: 310. |
| 16a | Exported dyed diesel fuel and exported gasoline blendstocks | Dyed fuel carries only the LUST tax; this line returns it on exports. “The person that exported dyed diesel fuel or dyed kerosene during the period of claim is the only person eligible to make this claim.” Rate printed: $.001 a gallon. CRN: 415. |
| 16b | Exported dyed kerosene | Dyed kerosene exported during the period. Keep proof of exportation. Rate printed: $.001 a gallon. CRN: 416. |
| 17 | 17 Total income tax credit claimed. Add lines 1 through 16, column (e). Enter here and | The total goes to “Schedule 3 (Form 1040), line 12; Form 1120, Schedule J, line 20b; Form 1120-S, line 24c; Form 1041, Schedule G, line 17; or the proper line of other returns”. Partnerships do not file Form 4136; they report each partner's gallons, rates and uses on Schedule K-1. |
Type of Use Table
Column (a) takes a number from this table, from the Instructions for Form 4136 (2025). The same numbers are used on Form 8849 and Form 720 Schedule C.
| Type of use | Description |
|---|---|
| 1 | On a farm for farming purposes |
| 2 | Off-highway business use (other than in a highway vehicle registered or required to be registered for highway use) |
| 3 | Export |
| 4 | In a boat engaged in commercial fishing |
| 5 | In certain intercity and local buses |
| 6 | In a qualified local bus |
| 7 | In a bus transporting students and employees of schools (school buses) |
| 8 | Diesel fuel and kerosene (other than kerosene used in aviation) used other than as a fuel in the propulsion engine of a train or diesel-powered highway vehicle (but not off-highway business use) |
| 9 | In foreign trade |
| 10 | Certain helicopter and fixed-wing aircraft uses |
| 11 | Exclusive use by a qualified blood collector organization |
| 12 | In a highway vehicle owned by the United States that isn't used on a highway |
| 13 | Exclusive use by a nonprofit educational organization |
| 14 | Exclusive use by a state, political subdivision of a state, or the District of Columbia |
| 15 | In an aircraft or vehicle owned by an aircraft museum |
| 16 | In military aircraft |
Rules that trip filers up
- Claiming the same gallons twice. “You can't claim any amounts on Form 4136 that you claimed on Form 8849; Form 8864; or Form 720, Schedule C.” A business that reports excise tax on Form 720 may have to use its credits there first.
- Highway vehicles. Type of use 2 is off-highway business use. Fuel burned in a vehicle registered, or required to be registered, for the highway does not qualify, and the form makes you certify it for type of use 2.
- Leaving column (d) blank. The actual fuel cost column is new for 2025. The IRS uses it to test the claim against the activity's receipts and may ask for the invoices later; keep them with your books.
- Vendor lines without a registration. Lines 6 to 8, 13 and 15 need a Form 637 number with its prefix. Apply first, then claim.
- Claiming the ended credits. Biodiesel, renewable diesel, alternative fuel mixture and SAF credits are not claimed on the 2025 form.
- Forgetting the income side. “Include any credit or refund of excise taxes on fuels in your gross income if you claimed the total cost of the fuel (including the excise taxes) as an expense deduction that reduced your income tax liability.”
How it connects
- The rules behind the lines: the Form 4136 guide, the federal fuel excise tax hub (rates, the rack, dyed fuel) and the dyed fuel rules.
- The quarterly routes for the same tax: the Form 8849 guide and its form page, and Form 720 Schedule C on the Form 720 form page.
- Vendor and card issuer registration: Form 637 registration and the Form 637 form page.
- Truckers: IFTACompliance.com covers Form 4136 for truckers, with the reefer and off-highway lines, and reefer and off-highway fuel tax refunds on Form 4136 and Form 8849.
Questions filers ask
Do I still file Form 4136 if I answer No on line A?
No. The instructions say that if you answer No on line A you are not eligible and should not complete the form. The one exception is undyed kerosene bought (not from a blocked pump) and used at home for heating, lighting or cooking: answer Yes, skip lines B to F and claim on line 4a.
What goes in the new column (d)?
The actual fuel cost from your records for the gallons claimed on that line. Do not attach receipts; keep them, because the IRS may ask for proof later.
Where does the line 17 total go?
On Schedule 3 (Form 1040), line 12; Form 1120, Schedule J, line 20b; Form 1120-S, line 24c; Form 1041, Schedule G, line 17; or the proper line of another income tax return.
Can a fuel vendor claim gasoline sales on Form 4136?
No. Form 4136 cannot be used by ultimate vendors to make gasoline claims; registered vendors and credit card issuers claim gasoline sold to state and local governments or nonprofit schools on Form 8849 or Form 720 Schedule C.
Do I need more than one Form 4136 for several businesses?
One Form 4136, plus a separate Schedule A (Form 4136) for each qualifying business activity when there is more than one. Combine the Schedule A totals on Form 4136 and describe the activity with the most fuel use in Part I.
Why are lines 10 and 12 blank on the 2025 form?
The biodiesel, renewable diesel, alternative fuel and alternative fuel mixture credits, and the SAF refund route, ended for sales, uses or removals after 2024, so those lines are reserved.