- Who files
- TTB permittees, manufacturers, importers and taxpayers
- Due
- 6 months for losses; 3 years for overpayments
- Filed with
- TTB online claims, or NRC Suite 8970, Cincinnati
- Form revision
- 07/2025
- Pages
- 1, plus instructions
At a glance
TTB F 5620.8 is the claim form for the federal excise taxes the Alcohol and Tobacco Tax and Trade Bureau collects: distilled spirits, wine, beer, tobacco products, and firearms and ammunition. TTB describes its purpose as claims “for the payment (refund or allowance of credit) of Federal excise taxes paid on beverage alcohol or tobacco products lost, rendered unmarketable, or condemned by a duly authorized official under various circumstances”, plus tax collected in error and drawback on spirits used in nonbeverage products. Our TTB claims and drawback guide explains when each claim applies; this page walks the form.
- Who files. The permittee, manufacturer, proprietor, importer or taxpayer that paid or owes the tax. Remission claims only by the person liable for the tax.
- When. Generally within 6 months for losses and destructions, and within 3 years (2 years in some cases) for overpayments (see deadlines).
- Where. Online through TTB's online claim submission, or by mail to TTB's National Revenue Center at Suite 8970, Cincinnati (see filing).
- Form revision. TTB F 5620.8 (07/2025), OMB No. 1513-0030, with the item instructions on page 2. The 07/2025 edition added direct deposit (item 10).
The claim types
Item 2 names the claim. The definitions below are the form's own, shortened; the form adds a caution that taxpaid spirits, wine, beer or tobacco lost or made unmerchantable by accident, disaster, fire, casualty or act of God are claimed as an allowance of credit or a refund.
| Type (item 2) | What it covers |
|---|---|
| Remission of tax | Spirits (including distilling material and denatured spirits) or tobacco products lost or destroyed in bond before the tax was paid or determined; also beer lost in transit between breweries and wine lost in transit to export. |
| Allowance of loss | Denatured spirits, wine or beer lost or destroyed on bonded premises (or wine lost in transit to them) before the tax was paid or determined. |
| Drawback, MNBP | A manufacturer of nonbeverage products: drawback on taxpaid spirits used in an approved formula for medicines, food products, flavors and the like. |
| Allowance of credit for tax | The approved amount is applied as a credit against unpaid or future tax. |
| Allowance of tax | Tobacco products lost (other than by theft) or destroyed by fire, casualty or act of God after removal but before the tax was due. |
| Drawback, export | Drawback of tax on taxpaid spirits, wine or beer exported; not for tobacco products (those use TTB F 5620.7). |
| Abatement of tax | Tax on firearms, ammunition, spirits, wine, beer or tobacco assessed, or assessed excessively, that the taxpayer believes is not due. |
| Refund of tax | Taxes illegally, erroneously or excessively collected. |
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
Items 1 to 14
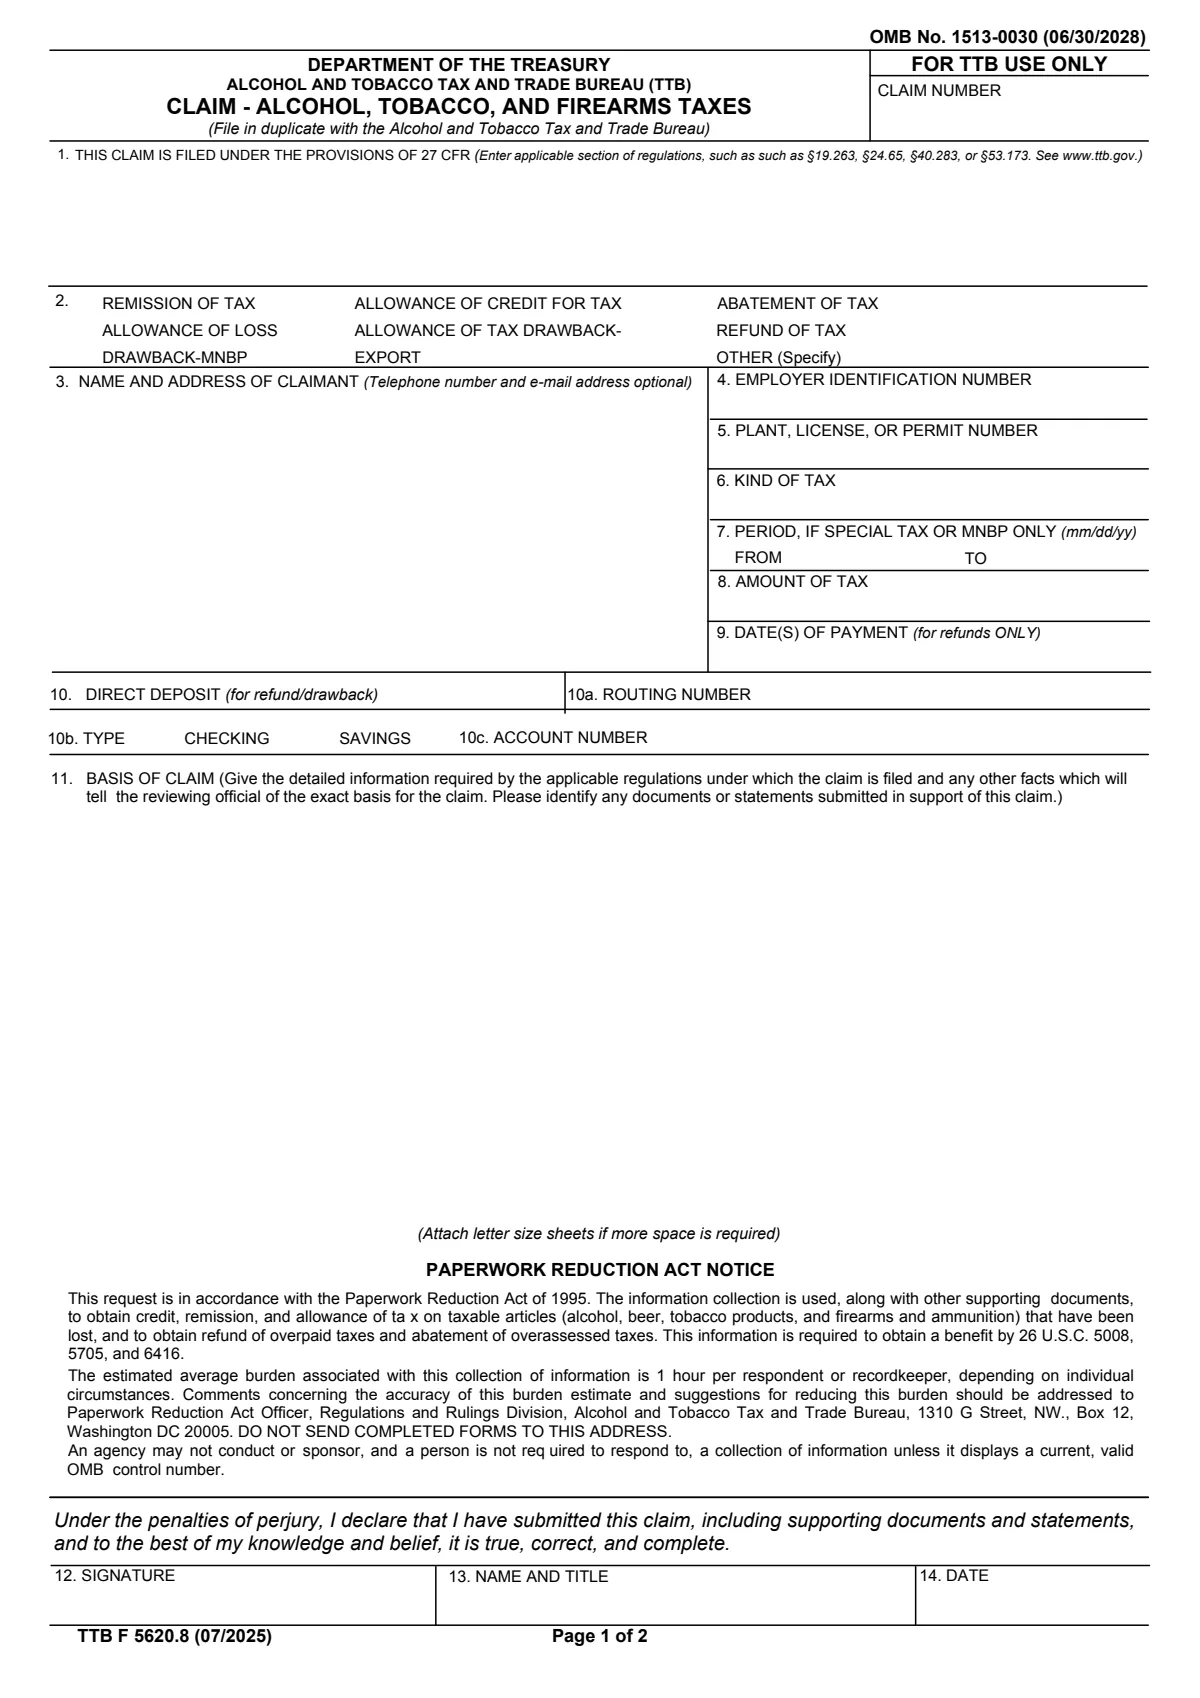
Page 1 is the claim; page 2 gives the item instructions, a sample check for the banking items and the mailing address. Item 11 carries the substance: the regulation in item 1 decides what it must show.
| Item | Label | What goes there |
|---|---|---|
| TTB-use | FOR TTB USE ONLY | TTB's claim number. Leave it blank; quote it later when you ask about the claim. |
| 1 | 1. THIS CLAIM IS FILED UNDER THE PROVISIONS OF 27 CFR | “Enter the section of the regulations under which you are” filing this claim. The form's own examples are sections 19.263 (spirits), 24.65 (wine), 40.283 (tobacco) and 53.173 (firearms and ammunition); the regulation sets what the claim must show. |
| 2 | ALLOWANCE OF CREDIT FOR TAX | Check the claim type. The eight types and what each covers are in the table above the form. A claim for a loss filed as credit is applied against tax; a refund comes back by direct deposit. |
| 3 | 3. NAME AND ADDRESS OF CLAIMANT | “Enter the claimant's name and address.” Telephone and email are optional but speed up questions. |
| 4 | 4. EMPLOYER IDENTIFICATION NUMBER | “Enter the claimant's employer identification number.” |
| 5 | 5. PLANT, LICENSE, OR PERMIT NUMBER | “Enter the claimant's plant, license, or registry number.” Retailers filing a disaster claim may have none. |
| 6 | 6. KIND OF TAX | “Enter the kind of tax (excise tax, special tax).” TTB's tobacco FAQ: for an overpayment or product withdrawn from the market, enter "Excise Tax". |
| 7 | 7. PERIOD, IF SPECIAL TAX OR MNBP ONLY | “Enter the period of which the tax was due (this only applies to special tax or nonbeverage claims).” Use mm/dd/yy. |
| 8 | 8. AMOUNT OF TAX | “Enter the total amount of tax being claimed.” Show the computation in item 11 (quantity times the rate that was paid). |
| 9 | 9. DATE(S) OF PAYMENT (for refunds ONLY) | “Enter the date the tax was paid (if paid) by the claimant.” |
| 10 | 10. DIRECT DEPOSIT (for refund/drawback) | Item 10 is new on the 07/2025 edition. TTB says “Effective September 30, 2025, TTB will cease issuing paper checks for disbursements, including tax refunds and drawback.” Without banking information, a refund is delayed. |
| 10a | 10a. ROUTING NUMBER | “The routing number must be nine digits.” |
| 10b | 10b. TYPE CHECKING SAVINGS | “Check the appropriate box for the type of account. Do not check more than one box.” |
| 10c | 10c. ACCOUNT NUMBER | “The account number can be up to 17 characters (both numbers and letters).” Leave out hyphens, spaces and symbols. |
| 11 | 11. BASIS OF CLAIM | “Provide detailed information that may be required by the applicable regulations pertaining to the claim along with any other necessary facts.” Identify every document attached. Nonbeverage drawback claims attach Form 5154.2, Supporting Data; disaster claims attach the insurance policy. |
| Declaration | Under the penalties of perjury, I declare that I have submitted this claim, | “All claims need to be signed by someone with signing authority (except Disaster Claims) and must be executed under the penalty of perjury clause.” |
| 12 | 12. SIGNATURE | “Enter the signature and title of a person authorized to sign on behalf of the company/claimant.” Authority is on file with TTB on Form 5100.1 (corporate and LLC officials) or Form 5000.8 (power of attorney). |
| 13 | 13. NAME AND TITLE | The signer's name and title, typed or printed. (The instructions on page 2 number the items one off from the 07/2025 form: they call the signature and title item 12 and the date item 13.) |
| 14 | 14. DATE | The date the claim was signed; deadlines are measured to the filing date, so file promptly after signing. |
Deadlines
TTB's page sets out the short deadlines: “For beer, wine or spirits; claims must be filed within 6 months of the date of return, loss, destruction or rendering unmerchantable.” Tobacco products lost, destroyed or withdrawn from the market are also 6 months, and nonbeverage drawback is due within 6 months from the end of the quarter in which the spirits were used (27 CFR 17.145)27 CFR 17.145Code of Federal Regulations, eCFR. Overpayments run longer: “A claim for overpayment of tax shall be filed by the taxpayer within 3 years from the time the return was filed or 2 years from the time the tax was paid.”
TTB Form 5620.8 page (TTB, last updated Aug. 22, 2024); TTB F 5620.8 (07/2025), Refund of tax.
Filing: online or by mail
TTB takes claims through TTB's online claim submission; CBMA importer refund claims go through myTTB instead (see the CBMA guide). On paper, the form says “File in duplicate with the Alcohol and Tobacco Tax and Trade Bureau” and gives the address “OFFICE OF PERMITTING AND TAXATION ALCOHOL AND TOBACCO TAX AND TRADE BUREAU 550 MAIN ST., STE. 8970 CINCINNATI, OH 45202-3222”, which matches the National Revenue Center's own page (“Suite 8970”). TTB's older Form 5620.8 web page (last updated Aug. 22, 2024) still shows Room 8002; use Suite 8970 or file online. Premises in Puerto Rico mail to TTB's San Juan office, as page 2 of the form says.
What to attach
- Losses in bond or in transit. Affidavits of people who know of the loss, the carrier's bill of lading for transit losses, and whether insurance paid you.
- Returns to bond and destruction. The quantities, the tax paid, the plant and the date of return or destruction (for spirits, 27 CFR 19.42 lists the details; brewers notify TTB before destroying beer off premises).
- Nonbeverage drawback. “All claimants must have Form 5154.2, Supporting Data attached to the claim.” “The drawback rate is $1.00 less than the effective tax rate on distilled spirits.”
- Disaster claims. A copy of the insurance policy and proof you were not indemnified for the tax (26 U.S.C. 5064; 27 CFR 70.603)26 U.S.C. 5064United States Code, Cornell LII27 CFR 70.603Code of Federal Regulations, eCFR.
- Imported tobacco destroyed. Prior approval on Form 5200.7 and proof of the tax paid to Customs.
After you file
TTB's service goal is in its own words: “Our customer service goal is to review and pay 85% of claims within:” 45 days. Its October 2026 medians were 13 days for CBMA importer claims, 44 days for nonbeverage drawback and 28 days for all other claims. An allowance of credit is taken on the return only after approval: “Yes, if you filed an allowance for credit claim with TTB. You cannot take the credit until the claim is approved by TTB.” A rejected claim can be reopened under the regulation: “A claimant who wishes to have a rejected claim reopened must, within the applicable statutory period of limitations, submit a written application to the officer who originally rejected the claim for reconsideration of the claim.” The application must show new and material evidence (27 CFR 70.414(k))27 CFR 70.414Code of Federal Regulations, eCFR. TTB's FAQ answer that no claim is reopened does not override the regulation.
Rules that trip filers up
- Missing the 6 months. Loss, destruction and drawback claims have short windows; the 3-year rule is only for overpayments.
- No signing authority on file. Unless it is a disaster claim, the signer needs authority on file with TTB.
- Leaving out banking details. TTB stopped paper checks on Sept. 30, 2025; item 10 is how the money arrives.
- Taking the credit before approval. An allowance of credit is adjusted on the return only after TTB approves it.
- Tobacco export drawback on this form. The export drawback box excludes tobacco products; tobacco uses TTB F 5620.7.
- The old address. Mail to Suite 8970, not Room 8002, or file online.
How it connects
- When and how to claim: TTB excise tax claims and drawback, and the claims sections of the alcohol, tobacco and firearms and ammunition hubs.
- The returns the claims adjust: TTB F 5000.24 (guide) and TTB F 5300.26.
- All TTB taxes: the TTB hub and permits and bonds.
Questions filers ask
How long do I have to file a TTB claim for lost or destroyed beer, wine or spirits?
Six months from the date of the return, loss, destruction or rendering unmerchantable, per TTB's Form 5620.8 page. Tobacco losses and withdrawals are also six months.
Where do I mail TTB F 5620.8?
To the Office of Permitting and Taxation, TTB, 550 Main St., Ste. 8970, Cincinnati, OH 45202-3222, as printed on the 07/2025 form, or file through TTB's online claim submission. Puerto Rico premises use the San Juan address on the form.
Does TTB still mail refund checks?
No. TTB stopped issuing paper checks for refunds and drawback on Sept. 30, 2025, unless an exception applies. Complete the direct deposit items 10a to 10c.
Can I take a credit on my return as soon as I file an allowance of credit claim?
No. TTB says the credit cannot be taken until the claim is approved.
Can a rejected TTB claim be reopened?
Yes, under 27 CFR 70.414(k)27 CFR 70.414Code of Federal Regulations, eCFR: apply in writing to the officer who rejected it, within the statute of limitations, with new and material evidence that was unknown or unobtainable before.
Is this form used for tobacco export drawback?
No. The form's export drawback type excludes tobacco products exported with the benefit of drawback; those claims use TTB F 5620.7.