- Who files
- Licensed nicotine products wholesalers
- Due
- Quarterly; 5% penalty if not postmarked by the 20th
- Filed with
- Wyoming Department of Revenue
- Form revision
- None printed
- Pages
- 1
At a glance
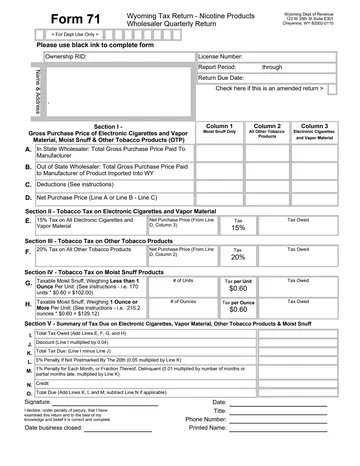
Form 71 is the Wyoming Department of Revenue's “Wholesaler Quarterly Return” for nicotine products other than cigarettes: other tobacco products, moist snuff, and electronic cigarettes and vapor material. Cigarettes are not on it; wholesalers report them monthly on Form 70-1, the “Cigarette Wholesaler's Monthly Return”.
- Who files. Licensed wholesalers, in state (line A) or out of state (line B), that buy the products from the manufacturer.
- When. Quarterly. The form's penalty line runs from a postmark after the 20th; the due date field is left blank, and the month is Not listed.
- Where. “Wyoming Dept of Revenue”, 122 W 25th St Suite E301, Cheyenne, WY 82002-0110, the address printed on the form. The form is on the Excise Tax Division's nicotine products returns page as Wholesaler Return (71). An online filing system for Form 71 is Not listed in the saved sources.
- Form. One page, no revision date printed, black ink only. No separate instructions for Form 71 are posted.
- Buyers who bypass a wholesaler. The Department's FAQ says tax is due on tobacco shipped into Wyoming, and if the customer has not paid a licensed wholesaler, “they would be responsible to self-report the tax to our office”. That is Form 72, the consumer return.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
Header
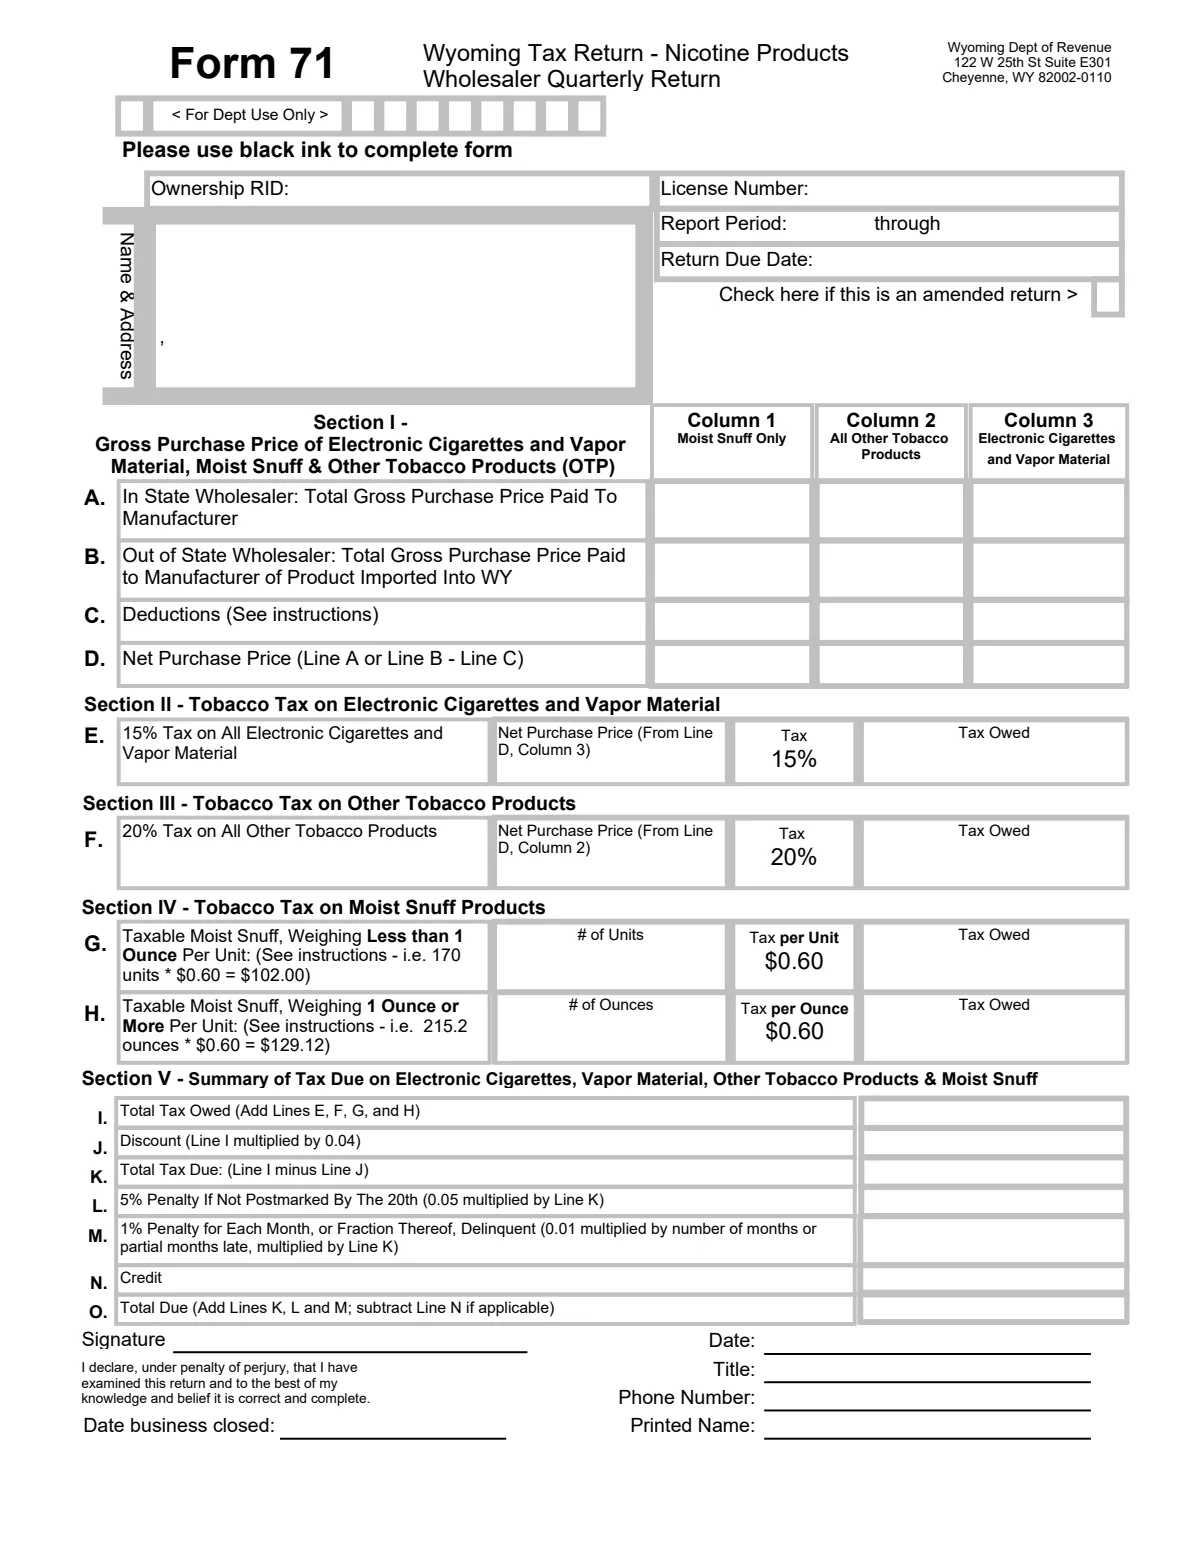
The header identifies the wholesaler, its license and the quarter.
| Line | Label | What goes there |
|---|---|---|
| Dept-use | < For Dept Use Only > | The Department's processing boxes. Leave them blank. |
| RID | Ownership RID: | The ownership record ID the Department of Revenue assigned to your account. The saved sources do not explain it further. |
| Name | Name & Address | The licensed wholesaler. The Department's FAQ says who pays: “Licensed wholesalers pay the tobacco tax from products purchased from the manufacturer.” |
| License | License Number: | Your Wyoming license number. Registration is on the Excise Tax Division's nicotine products registration page. |
| Period | Report Period: through | The first and last day of the quarter the return covers. |
| Due | Return Due Date: | The form leaves the date to be filled in. Its own penalty line sets the deadline as a postmark “By The 20th”; the month after the quarter is our reading, since the form does not name it. Due date: Not listed in the saved sources. |
| Amended | Check here if this is an amended return > | Check it when correcting a return already filed. |
Section I: net purchase price
Section I is the base. The tax on other tobacco products and on vapor products is a percentage of what the wholesaler paid the manufacturer, net of deductions; moist snuff is taxed by count or weight instead.
| Line | Label | What goes there |
|---|---|---|
| A | A. In State Wholesaler: Total Gross Purchase Price Paid To Manufacturer | In-state wholesalers enter the gross price they paid the manufacturer, split into column 1 (moist snuff only), column 2 (all other tobacco products) and column 3 (electronic cigarettes and vapor material). |
| B | B. Out of State Wholesaler: Total Gross Purchase Price Paid to Manufacturer of Product Imported Into WY | Out-of-state wholesalers enter the price paid to the manufacturer for the product they brought into Wyoming, in the same three columns. A wholesaler fills in line A or line B. |
| C | C. Deductions (See instructions) | The form refers to instructions, but the Department's returns page lists instructions only for Forms 70-1 and 70-2, none for Form 71. What may be deducted is Not listed in the saved sources; ask the Excise Tax Division. |
| D | D. Net Purchase Price (Line A or Line B - Line C) | Line A or line B, less line C, for each column. Column 2 feeds line F and column 3 feeds line E; column 1 (moist snuff) is not taxed on price, but by units or ounces on lines G and H. |
Sections II to IV: the taxes
Each section takes its base from Section I or from a count and applies the printed rate.
| Line | Label | What goes there |
|---|---|---|
| E | E. 15% Tax on All Electronic Cigarettes and Vapor Material | Net purchase price from line D, column 3, times 15%. Form 72, the consumer return, shows a different rate for the same products: “D. 7.5% Tax on All Electronic Cigarettes and Vapor” material, on the consumer's purchase price. See the rate question below. |
| F | F. 20% Tax on All Other Tobacco Products | Net purchase price from line D, column 2, times 20%. Form 72 shows “E. 10% Tax on All Other Tobacco Products” on the consumer's purchase price. |
| G | G. Taxable Moist Snuff, Weighing Less than 1 Ounce Per Unit: (See instructions - i.e. 170 units * $0.60 = $102.00) | Count the units and multiply by $0.60. The form's own example: “170 units * $0.60 = $102.00”. |
| H | H. Taxable Moist Snuff, Weighing 1 Ounce or More Per Unit: (See instructions - i.e. 215.2 ounces * $0.60 = $129.12) | Add the ounces and multiply by $0.60. The form's example: “215.2 ounces * $0.60 = $129.12”. Form 72 uses the same 60 cents for consumers. |
Form 71 or Form 72: the rate question
Wyoming's two nicotine returns print different percentage rates. The wholesaler's Form 71 shows 20 percent for other tobacco products and 15 percent for vapor, on the net purchase price paid to the manufacturer. The consumer's Form 72 shows 10 percent and 7.5 percent on the purchase price. The bases differ (a wholesaler's cost against a consumer's price), which may be the reason, but neither form says so. The Wyoming statute (W.S. 39-18) was not read for this site, so we cannot say which rate is current law. Wholesalers file at the Form 71 rates as printed; ask the Excise Tax Division before relying on either. The Wyoming excise tax page takes the same position.
Wyoming Department of Revenue Forms 71 and 72, read Nov. 22, 2026.
Section V: total due and signature
Section V totals the tax, takes the 4 percent discount, adds the late penalties when they apply and subtracts any credit.
Wyoming Form 71, Section V.
| Line | Label | What goes there |
|---|---|---|
| I | Total Tax Owed (Add Lines E, F, G, and H) | The four taxes added. |
| J | Discount (Line I multiplied by 0.04) | A 4 percent discount for the wholesaler. The form does not say whether a late return loses it; the saved sources are silent. |
| K | Total Tax Due: (Line I minus Line J) | The tax after the discount. |
| L | 5% Penalty If Not Postmarked By The 20th (0.05 multiplied by Line K) | A flat 5 percent of line K when the postmark is after the 20th. |
| M | M. 1% Penalty for Each Month, or Fraction Thereof, Delinquent (0.01 multiplied by number of months or partial months late, multiplied by Line K) | 1 percent of line K for each month or part of a month late, on top of line L. |
| N | N. Credit | A credit you are applying against this return. The saved sources do not say where a credit comes from. |
| O | O. Total Due (Add Lines K, L and M; subtract Line N if applicable) | What you pay. |
| Signature | Signature. I declare, under penalty of perjury, that I have examined this return and to the best of my knowledge and belief it is correct and complete. | The wholesaler's signature. |
| Closed | Date business closed: | The closing date, if the business has closed. |
| Signer | Date: Title: Phone Number: Printed Name: | The date, the signer's title, a phone number and the printed name. |
How it connects
- Wyoming's motor fuel, cigarette, tobacco, vapor and alcohol taxes: Wyoming excise tax.
- Other states: vapor tax by state and cigarette tax by state. Other state tobacco returns: West Virginia TPT-709 and New Jersey TPT-10.
- The federal tobacco tax paid by manufacturers and importers: tobacco excise tax. Federal excise tax does not reach e-cigarettes without tobacco; Wyoming's tax does.
Questions filers ask
Who files Wyoming Form 71?
Licensed wholesalers of other tobacco products, moist snuff, and electronic cigarettes and vapor material, quarterly. In-state wholesalers use line A, out-of-state wholesalers line B.
What are the rates on Form 71?
20 percent of the net purchase price for other tobacco products, 15 percent for electronic cigarettes and vapor material, and $0.60 per unit (under 1 ounce) or per ounce for moist snuff.
Why does Form 72 show 10 percent and 7.5 percent?
Form 72 is the consumer's return and taxes the consumer's purchase price. The forms do not explain the difference and the statute was not read here, so the site does not say which rate governs. Ask the Excise Tax Division.
When is Form 71 late?
The form adds a 5 percent penalty if it is not postmarked by the 20th and 1 percent for each month or part of a month late. The month of the 20th is not printed; we read it as the month after the quarter.
Does Form 71 include cigarettes?
No. Cigarette wholesalers buy Wyoming stamps and report monthly on Form 70-1.