- At a glance
- Form 8849, with hotspots
- Form 8849, line by line
- The Type of Use Table
- Schedule 1: nontaxable use of fuels
- Schedule 2: registered ultimate vendors
- Schedule 5: section 4081(e) and 6435 claims
- Schedule 6: other claims
- Schedule 8: credit card issuers
- Schedule 3: closed after 2024
- Rules that trip filers up
- How it connects
- Questions filers ask
- Sources
- Who files
- Fuel buyers, vendors, card issuers, other excise payers
- Mailed to
- Cincinnati (1, 6) or Covington, KY (2, 5, 8)
- Schedule 1 minimum
- $750 a claim
- Form revision
- Rev. May 2026
- Pages
- 1, plus each schedule
At a glance
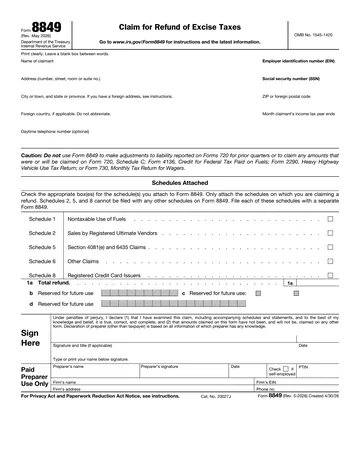
Form 8849 is the IRS claim for refund of excise taxes. Its instructions put it plainly: “Use Form 8849 to claim a refund of excise taxes.” Page 1 is a short cover with the claimant's details, a box for each schedule and the total; the claim itself is on the schedule attached. This page walks the cover and all five current schedules on the official images.
- Who files. The buyer that used fuel tax free (Schedule 1), registered ultimate vendors (Schedule 2), the payer of a second fuel tax or of tax on fuel later dyed (Schedule 5), the payer of other excise taxes on Forms 720, 2290, 730 and 11-C, and remittance senders (Schedule 6), and registered credit card issuers (Schedule 8).
- Where. “For Schedules 1 and 6, send Form 8849 to: Department of the Treasury Internal Revenue Service Cincinnati, OH 45999-0002”; Schedules 2, 5 and 8 go to “Internal Revenue Service P.O. Box 312 Covington, KY 41012-0312”, by U.S. mail, since private delivery services cannot deliver to a P.O. box. It can also be e-filed through the IRS e-file program for excise taxes.
- Which schedules together. “Schedules 2, 5, and 8 cannot be filed with any other schedules on Form 8849. File each of these schedules with a separate Form 8849.”
- Form revisions. Form 8849 (Rev. May 2026); Schedule 1 (Rev. May 2020); Schedule 2 (Rev. December 2020); Schedule 5 (Rev. May 2026); Schedule 6 (Rev. August 2013, with Instructions for Schedule 6, Rev. June 2026); Schedule 8 (October 2006). The IRS's About Form 8849 page lists no separate instructions for Form 8849: they are printed on pages 2 to 4 of the form.
- Income tax. “Include any refund of excise taxes in your gross income if you claimed the amount of the tax as an expense deduction that reduced your income tax liability.”
Form 8849 (Rev. May 2026) and its instructions; Schedules 1, 2, 5, 6 and 8 and their instructions.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
Form 8849, line by line
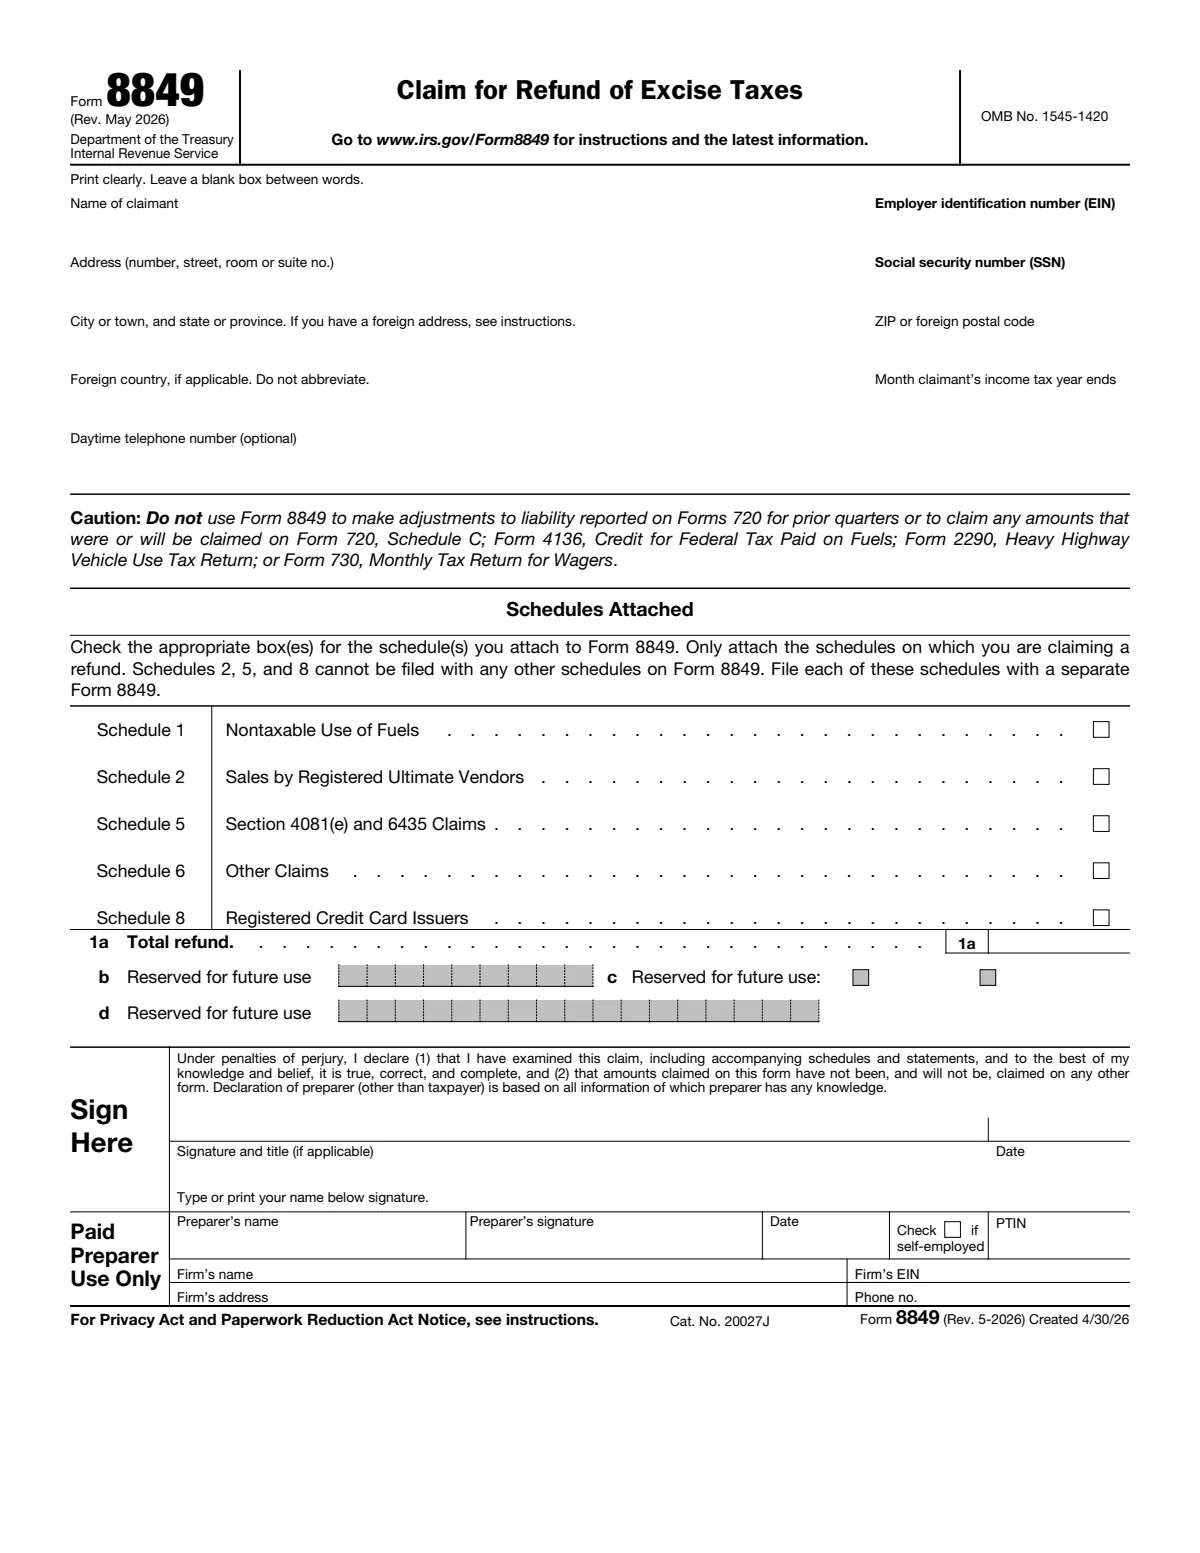
The cover is printed in boxes for machine reading. Get the EIN right and check only the schedules attached; the IRS can return a claim that is missing information. “Your refund will be delayed or Form 8849 will be returned to you if you do not follow the required procedures or do not provide all the required information.”
| Line | Label | What goes there |
|---|---|---|
| F-name | Name of claimant | “Print the information in the spaces provided. Begin printing in the first box on the left. Leave a blank box between each name and word.” |
| F-ein | Employer identification number (EIN) | “Enter your EIN in the boxes provided. If you are not required to have an EIN, enter your SSN. An incorrect or missing number will delay processing your claim.” A QSub or single-owner disregarded entity claims under its own EIN, not the owner's. |
| F-address | Address (number, street, room or suite no.) | “If your post office does not deliver mail to your street address and you have a P.O. box, show your box number instead of your street address.” |
| F-ssn | Social security number (SSN) | Only for a claimant that is not required to have an EIN, such as an individual farmer. |
| F-city | City or town, and state or province. If you have a foreign address, see instructions. | “Follow the country’s practice for entering the postal code.” |
| F-zip | ZIP or foreign postal code | The ZIP code, or the foreign postal code. |
| F-country | Foreign country, if applicable. Do not abbreviate. | Only for a foreign address. |
| F-month | Month claimant’s income tax year ends | “For example, if your income tax year ends in December, enter ‘12’ in the boxes.” The schedules' claim periods and the annual Form 4136 run off this year. |
| F-phone | Daytime telephone number (optional) | Optional, but it lets the IRS call instead of returning the claim. |
| F-caution | Caution: Do not use Form 8849 to make adjustments to liability reported on Forms 720 for prior quarters ... | “Do not use Form 8849 to make adjustments to liability reported on Forms 720 for prior quarters or to claim any amounts that were or will be claimed on Form 720, Schedule C; Form 4136, Credit for Federal Tax Paid on Fuels; Form 2290, Heavy Highway Vehicle Use Tax Return; or Form 730, Monthly Tax Return for Wagers.” Amendments go on Form 720-X. |
| F-sch1 | Schedule 1 Nontaxable Use of Fuels | Check it when Schedule 1 is attached. “Only attach the schedules on which you are claiming a refund.” |
| F-sch2 | Schedule 2 Sales by Registered Ultimate Vendors | Check it for a vendor claim. “Schedules 2, 5, and 8 cannot be filed with any other schedules on Form 8849.” |
| F-sch5 | Schedule 5 Section 4081(e) and 6435 Claims | Check it for a second-tax or dyed fuel claim, on a Form 8849 of its own. |
| F-sch6 | Schedule 6 Other Claims | Check it for refunds of Form 720, 2290, 730 or 11-C taxes and other claims not on Schedules 1, 2, 5 and 8. |
| F-sch8 | Schedule 8 Registered Credit Card Issuers | Check it for a card issuer claim, on a Form 8849 of its own. |
| F-1a | Total refund | “Enter the total refund from Schedules 1, 2, 5, 6, and 8.” In practice it is the total box of the one schedule attached, or of Schedules 1 and 6 together. |
| F-1b | b Reserved for future use; c Reserved for future use; d Reserved for future use | Blank on the May 2026 form. |
| F-sign | Sign Here: Signature and title (if applicable), Date, Type or print your name | “Form 8849 must be signed by a person with authority to sign this form for the claimant.” The declaration also says the amounts “have not been, and will not be, claimed on any other form”. |
| F-preparer | Paid Preparer Use Only: name, signature, date, PTIN, firm's name, EIN, address, phone | A preparer who was paid and is not the claimant's employee signs and enters a PTIN. “However, you cannot use the PTIN of the tax preparation firm in place of your PTIN.” |
The Type of Use Table
Schedules 1 and 2 ask for a type of use number in column (a). The numbers come from this table in the Form 8849 instructions (read from the form), and each claim line accepts only certain numbers:
| No. | Type of use |
|---|---|
| 1 | On a farm for farming purposes |
| 2 | Off-highway business use (for business use other than in a highway vehicle registered or required to be registered for highway use) (other than use in mobile machinery) |
| 3 | Export |
| 4 | In a boat engaged in commercial fishing |
| 5 | In certain intercity and local buses |
| 6 | In a qualified local bus |
| 7 | In a bus transporting students and employees of schools (school buses) |
| 8 | For diesel fuel and kerosene (other than kerosene used in aviation) used other than as a fuel in the propulsion engine of a train or diesel-powered highway vehicle (but not off-highway business use) |
| 9 | In foreign trade |
| 10 | Certain helicopter and fixed-wing aircraft uses |
| 11 | Exclusive use by a qualified blood collector organization |
| 12 | In a highway vehicle owned by the United States that is not used on a highway |
| 13 | Exclusive use by a nonprofit educational organization |
| 14 | Exclusive use by a state, political subdivision of a state, or the District of Columbia |
| 15 | In an aircraft or vehicle owned by an aircraft museum |
| 16 | In military aircraft |
For sales to a state or local government (13 and 14) and to nonprofit schools, the instructions fix who claims first: the registered credit card issuer if the buyer used its card (Schedule 8), then the registered ultimate vendor (Schedule 2), then the buyer.
Schedule 1: nontaxable use of fuels
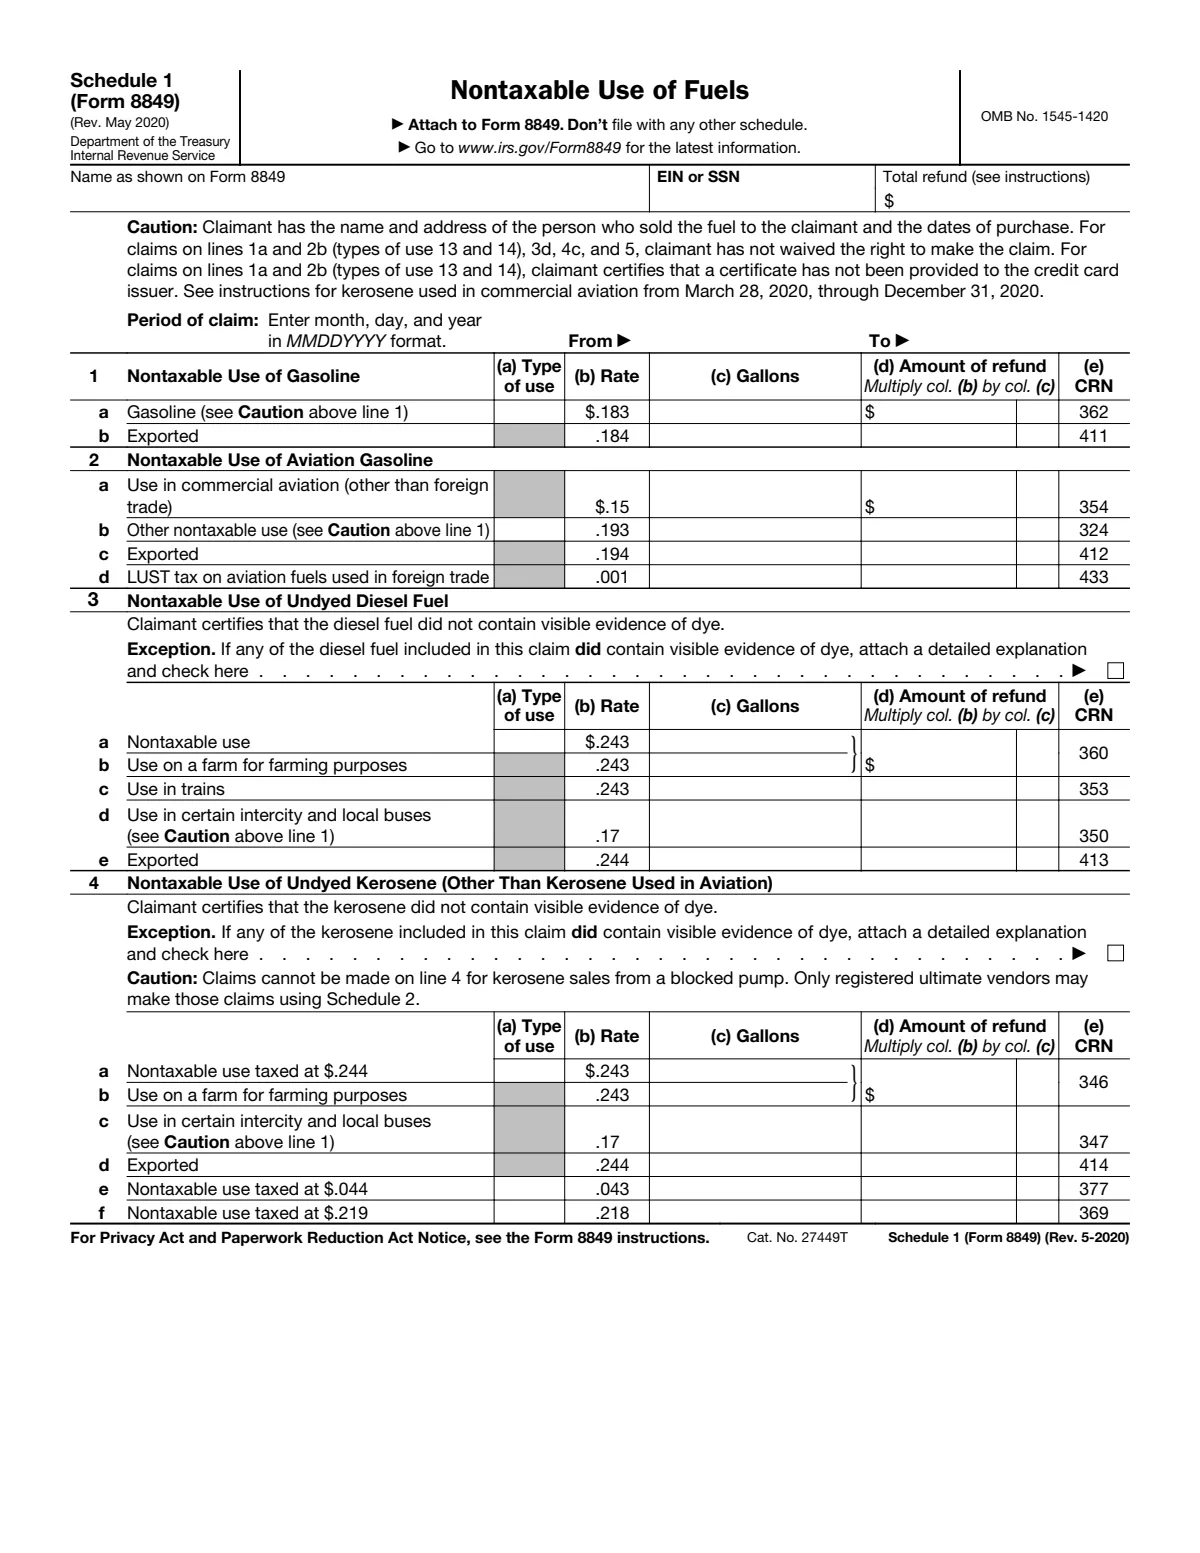
Schedule 1 belongs to the ultimate purchaser: “An ultimate purchaser of certain fuels uses Schedule 1 to make a claim for refund.” Farms, off-highway business equipment, commercial fishing boats, buses, exporters and the other listed users claim back the tax built into the fuel price. Each claim line has the rate and CRN printed; both are read from the form for the table below. Truckers' off-highway claims are covered from the carrier's side on IFTACompliance.com: Schedule 1 for truckers.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
| Line | Label | What goes there |
|---|---|---|
| S1-name | Name as shown on Form 8849 | The claimant's name, as on the Form 8849 the schedule is attached to. |
| S1-ein | EIN or SSN | As on the Form 8849. |
| S1-total | Total refund (see instructions) | “Add all amounts in column (d) and enter the result in the total refund box at the top of the schedule.” “The amount claimed on Schedule 1 must be at least $750.” |
| S1-caution | Caution: Claimant has the name and address of the person who sold the fuel to the claimant and the dates of purchase ... | Filing the schedule makes these statements. For lines 1a and 2b (types of use 13 and 14), 3d, 4c and 5, the claimant has not waived the claim to a vendor, and for 1a and 2b has not given a certificate to a credit card issuer: the order of claimants for government and school sales is card issuer, then vendor, then buyer. |
| S1-period | Period of claim: Enter month, day, and year in MMDDYYYY format. From / To | “The claim must be filed during the first quarter following the last quarter included in the claim.” “Only one claim may be filed for a quarter.” |
| S1-1 | Nontaxable Use of Gasoline | Every claim line has the same columns: (a) type of use number from the table below, (b) the printed rate, (c) gallons, (d) rate times gallons, (e) the CRN. |
| S1-2 | Nontaxable Use of Aviation Gasoline | Lines 2a to 2d. |
| S1-3 | Nontaxable Use of Undyed Diesel Fuel. Claimant certifies that the diesel fuel did not contain visible evidence of dye. | Undyed diesel only: dyed diesel was never taxed at the full rate. “Exception. If any of the diesel fuel included in this claim did contain visible evidence of dye, attach a detailed explanation and check here” |
| S1-4 | Nontaxable Use of Undyed Kerosene (Other Than Kerosene Used in Aviation) | The same no-dye statement for kerosene. “Only registered ultimate vendors may make those claims using Schedule 2.” (blocked pump sales) |
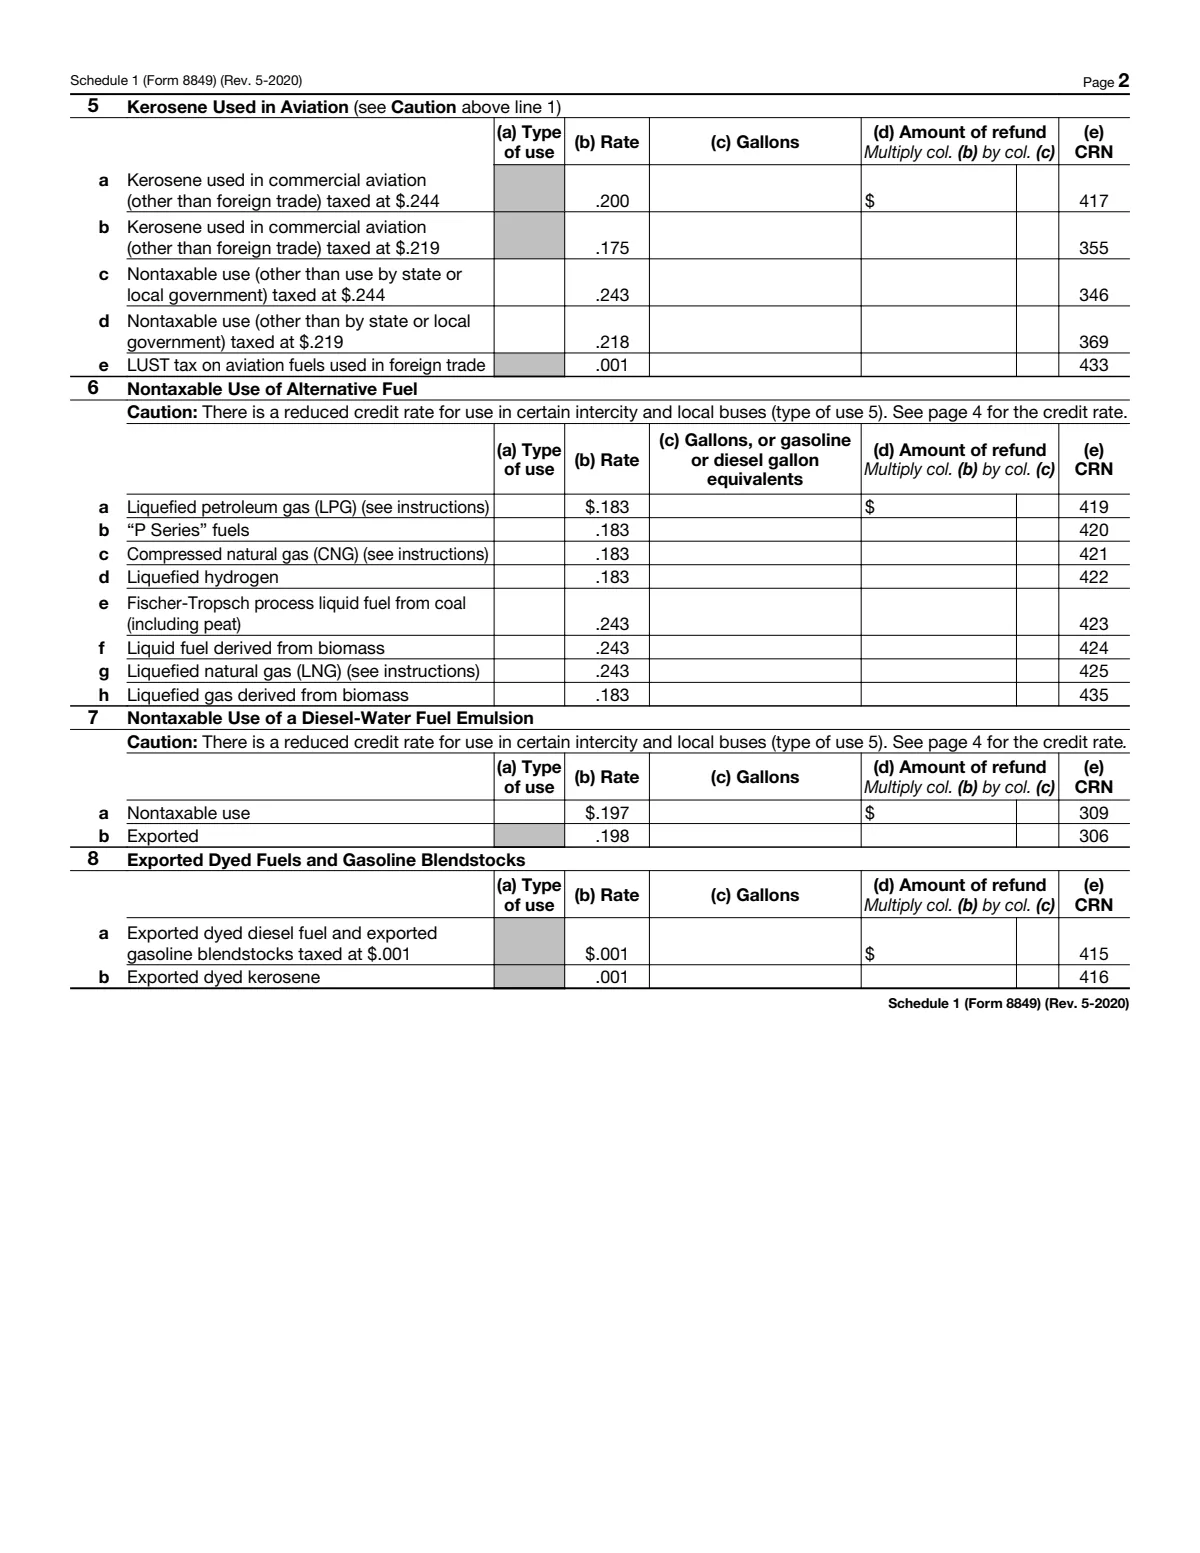
| S1-5 | Kerosene Used in Aviation (see Caution above line 1) | Lines 5a to 5e. The 2020 tax holiday wording on the form and instructions applies only to March 28 to Dec. 31, 2020. |
| S1-6 | Nontaxable Use of Alternative Fuel | “The taxed alternative fuel must have been used during the period of claim for type of use 1, 2, 4, 5, 6, 7, 11, 13, 14, or 15.” These are refunds of tax paid on alternative fuel used off the highway, not the alternative fuel credits that ended after 2024. |
| S1-7 | Nontaxable Use of a Diesel-Water Fuel Emulsion | Lines 7a and 7b. |
| S1-8 | Exported Dyed Fuels and Gasoline Blendstocks | “A claim may be made for dyed diesel fuel or dyed kerosene exported in a trade or business during the period of claim.” Blendstocks taxed at $.184 go on line 1b instead. |
| S1-1a | Gasoline (see Caution above line 1) | Claim rate printed on the form: $.183 a gallon. CRN 362. “For line 1a, the gasoline must have been used during the period of claim for type of use 2, 4, 5, 7, 11, 12, 13, 14, or 15.” “Type of use 2 does not include any personal use or use in a motorboat.” |
| S1-1b | Exported | Claim rate printed on the form: $.184 a gallon. CRN 411. Exported (type of use 3); keep proof of exportation, such as the export bill of lading. |
| S1-2a | Use in commercial aviation (other than foreign trade) | Claim rate printed on the form: $.15 a gallon. CRN 354. Aviation gasoline used in commercial aviation, other than foreign trade. |
| S1-2b | Other nontaxable use (see Caution above line 1) | Claim rate printed on the form: $.193 a gallon. CRN 324. Type of use 2, 9, 10, 11, 13, 14, 15 or 16. |
| S1-2c | Exported | Claim rate printed on the form: $.194 a gallon. CRN 412. Exported (type of use 3); keep proof of exportation, such as the export bill of lading. |
| S1-2d | LUST tax on aviation fuels used in foreign trade | Claim rate printed on the form: $.001 a gallon. CRN 433. Type of use 9, in addition to line 2b: the LUST part. |
| S1-3a | Nontaxable use | Claim rate printed on the form: $.243 a gallon. Type of use 2, 6, 7, 8, 11, 12, 13, 14 or 15. “Type of use 8 includes use as heating oil and use in a boat.” |
| S1-3b | Use on a farm for farming purposes | Claim rate printed on the form: $.243 a gallon. CRN 360. Type of use 1: on a farm for farming purposes. |
| S1-3c | Use in trains | Claim rate printed on the form: $.243 a gallon. CRN 353. Diesel used in trains. |
| S1-3d | Use in certain intercity and local buses (see Caution above line 1) | Claim rate printed on the form: $.17 a gallon. CRN 350. Type of use 5, at the bus rate. |
| S1-3e | Exported | Claim rate printed on the form: $.244 a gallon. CRN 413. Exported (type of use 3); keep proof of exportation, such as the export bill of lading. |
| S1-4a | Nontaxable use taxed at $.244 | Claim rate printed on the form: $.243 a gallon. The same uses as line 3a. “Claims cannot be made on line 4 for kerosene sales from a blocked pump.” |
| S1-4b | Use on a farm for farming purposes | Claim rate printed on the form: $.243 a gallon. CRN 346. Type of use 1. |
| S1-4c | Use in certain intercity and local buses (see Caution above line 1) | Claim rate printed on the form: $.17 a gallon. CRN 347. Type of use 5, at the bus rate. |
| S1-4d | Exported | Claim rate printed on the form: $.244 a gallon. CRN 414. Exported (type of use 3); keep proof of exportation, such as the export bill of lading. |
| S1-4e | Nontaxable use taxed at $.044 | Claim rate printed on the form: $.043 a gallon. CRN 377. Type of use 2, for kerosene taxed at $.044. |
| S1-4f | Nontaxable use taxed at $.219 | Claim rate printed on the form: $.218 a gallon. CRN 369. Type of use 2, for kerosene taxed at $.219. |
| S1-5a | Kerosene used in commercial aviation (other than foreign trade) taxed at $.244 | Claim rate printed on the form: $.200 a gallon. CRN 417. “For lines 5a and 5b, the ultimate purchaser of kerosene used in commercial aviation (other than foreign trade) is eligible to make this claim.” |
| S1-5b | Kerosene used in commercial aviation (other than foreign trade) taxed at $.219 | Claim rate printed on the form: $.175 a gallon. CRN 355. Ultimate purchaser, commercial aviation other than foreign trade. |
| S1-5c | Nontaxable use (other than use by state or local government) taxed at $.244 | Claim rate printed on the form: $.243 a gallon. CRN 346. Type of use 1, 9, 10, 11, 13, 15 or 16. |
| S1-5d | Nontaxable use (other than by state or local government) taxed at $.219 | Claim rate printed on the form: $.218 a gallon. CRN 369. Type of use 1, 9, 10, 11, 13, 15 or 16. |
| S1-5e | LUST tax on aviation fuels used in foreign trade | Claim rate printed on the form: $.001 a gallon. CRN 433. Type of use 9, in addition to lines 5c and 5d. |
| S1-6a | Liquefied petroleum gas (LPG) (see instructions) | Claim rate printed on the form: $.183 a gallon. CRN 419. Type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15; bus use takes a lower rate. For type of use 5, write Bus to the left of column (a) and use $.109 per gasoline gallon equivalent. “10,000 gallons of LPG ÷ 1.353 = 7,391 GGE x $0.109 = $805.62 claim amount.” |
| S1-6b | "P Series" fuels | Claim rate printed on the form: $.183 a gallon. CRN 420. Type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15; bus use takes a lower rate. For type of use 5, write Bus to the left of column (a) and use $.110. |
| S1-6c | Compressed natural gas (CNG) (see instructions) | Claim rate printed on the form: $.183 a gallon. CRN 421. Type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15; bus use takes a lower rate. For type of use 5, write Bus to the left of column (a) and use $.109 per gasoline gallon equivalent. |
| S1-6d | Liquefied hydrogen | Claim rate printed on the form: $.183 a gallon. CRN 422. Type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15; bus use takes a lower rate. For type of use 5, write Bus to the left of column (a) and use $.110. |
| S1-6e | Fischer-Tropsch process liquid fuel from coal (including peat) | Claim rate printed on the form: $.243 a gallon. CRN 423. Type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15; bus use takes a lower rate. For type of use 5, write Bus to the left of column (a) and use $.17. |
| S1-6f | Liquid fuel derived from biomass | Claim rate printed on the form: $.243 a gallon. CRN 424. Type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15; bus use takes a lower rate. For type of use 5, write Bus to the left of column (a) and use $.17. |
| S1-6g | Liquefied natural gas (LNG) (see instructions) | Claim rate printed on the form: $.243 a gallon. CRN 425. Type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15; bus use takes a lower rate. For type of use 5, write Bus to the left of column (a) and use $.169 per diesel gallon equivalent. |
| S1-6h | Liquefied gas derived from biomass | Claim rate printed on the form: $.183 a gallon. CRN 435. Type of use 1, 2, 4, 5, 6, 7, 11, 13, 14 or 15; bus use takes a lower rate. For type of use 5, write Bus to the left of column (a) and use $.110. |
| S1-7a | Nontaxable use | Claim rate printed on the form: $.197 a gallon. CRN 309. Type of use 1, 2, 5, 6, 7, 8, 11, 12, 13, 14 or 15. The bus rate is “The credit rate for type of use 5 is $.124 per gallon.” |
| S1-7b | Exported | Claim rate printed on the form: $.198 a gallon. CRN 306. Exported (type of use 3); keep proof of exportation, such as the export bill of lading. |
| S1-8a | Exported dyed diesel fuel and exported gasoline blendstocks taxed at $.001 | Claim rate printed on the form: $.001 a gallon. CRN 415. Exported dyed diesel and gasoline blendstocks taxed at $.001. |
| S1-8b | Exported dyed kerosene | Claim rate printed on the form: $.001 a gallon. CRN 416. Exported dyed kerosene. |
Miss the window or the $750 and the gallons are not lost: if the three requirements are not met, the schedule says to “see Annual Claims under Additional Information for Schedules 1, 2, and 3 in the Form 8849 instructions.” That annual claim is generally Form 4136 with the income tax return, except that the United States, states and their subdivisions, and most tax-exempt organizations file their annual claim on Schedule 1 “within the 3 years following the close of the taxable year”.
Schedule 2: registered ultimate vendors
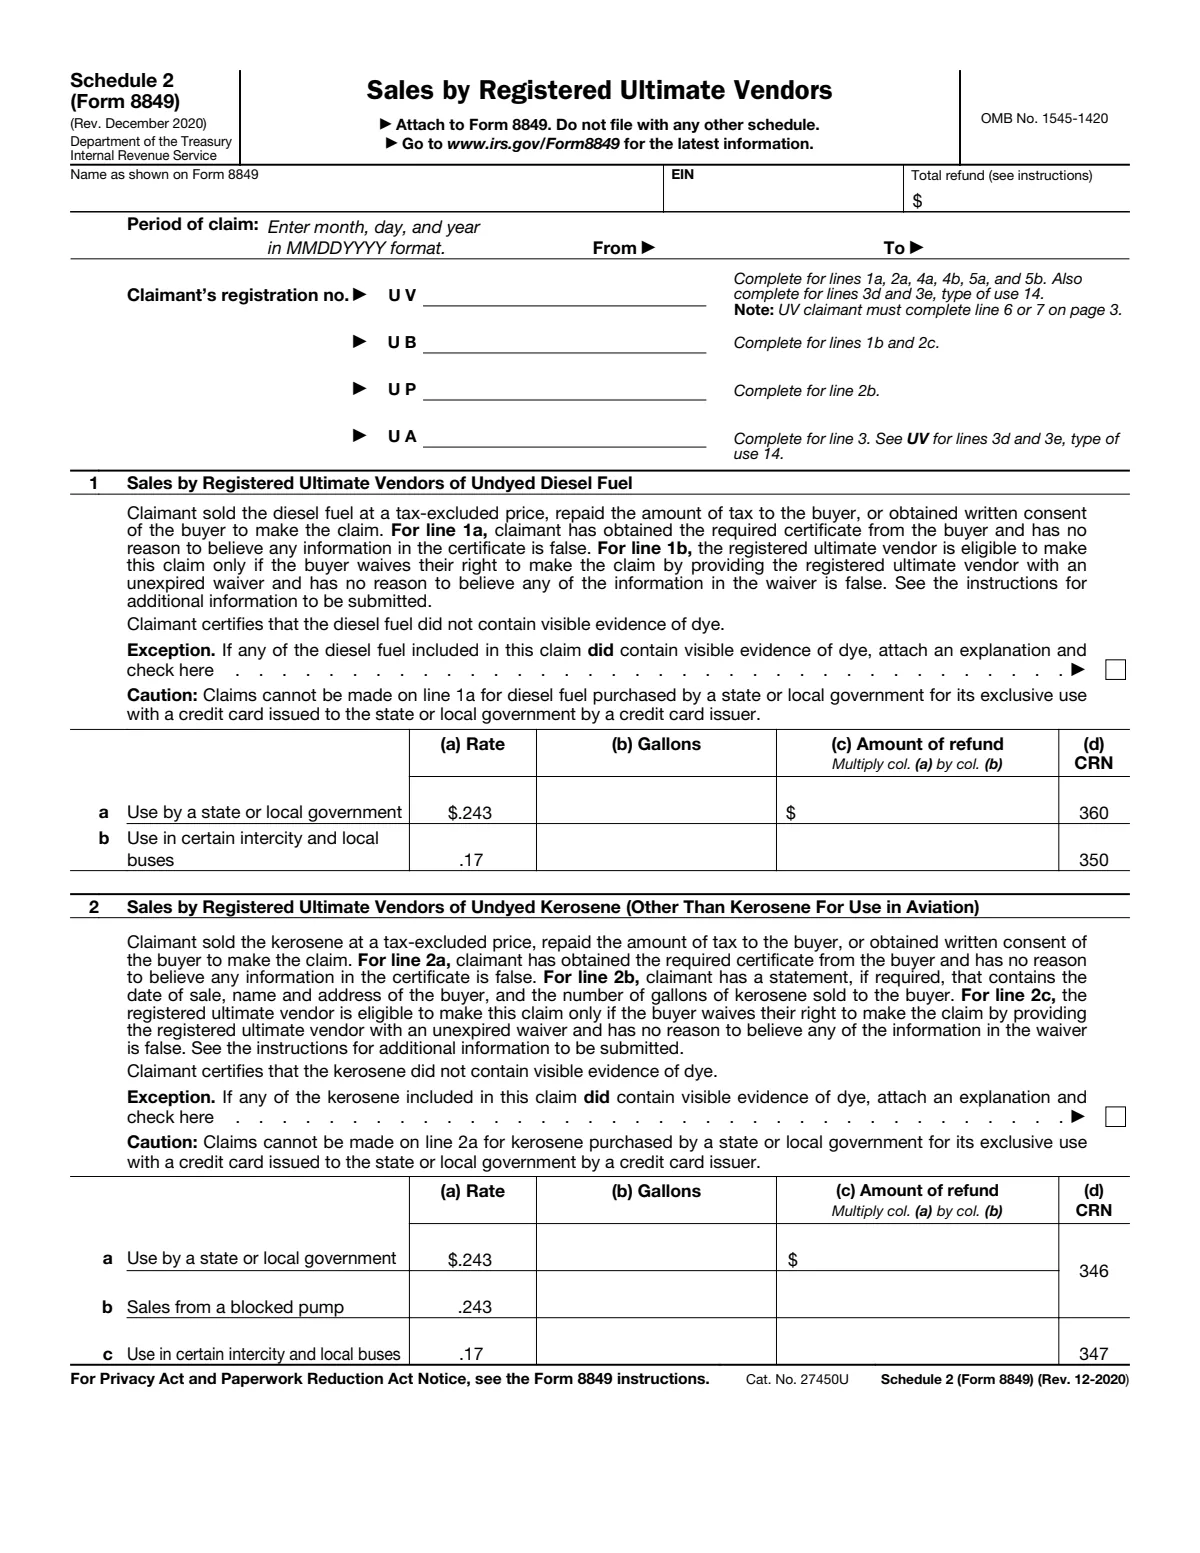
Schedule 2 is the seller's claim, for fuel sold to governments, nonprofit schools, bus operators and aviation buyers who gave the vendor a certificate or waiver. “A registered ultimate vendor of undyed diesel fuel, undyed kerosene, kerosene sold for use in aviation, gasoline, or aviation gasoline uses Schedule 2 to make a claim for refund.” Every line needs the right registration letter in the boxes at the top, issued on Form 637. These are interest-bearing claims: the Code pays interest if the IRS “has not paid pursuant to a claim filed under this section within 45 days of the date of the filing of such claim (20 days in the case of an electronic claim)”.
Schedule 2 (Form 8849) instructions, line 1a, for a calendar-year claimant; IRC 6427(i)(4)IRC 6427Internal Revenue Code, Cornell LII.
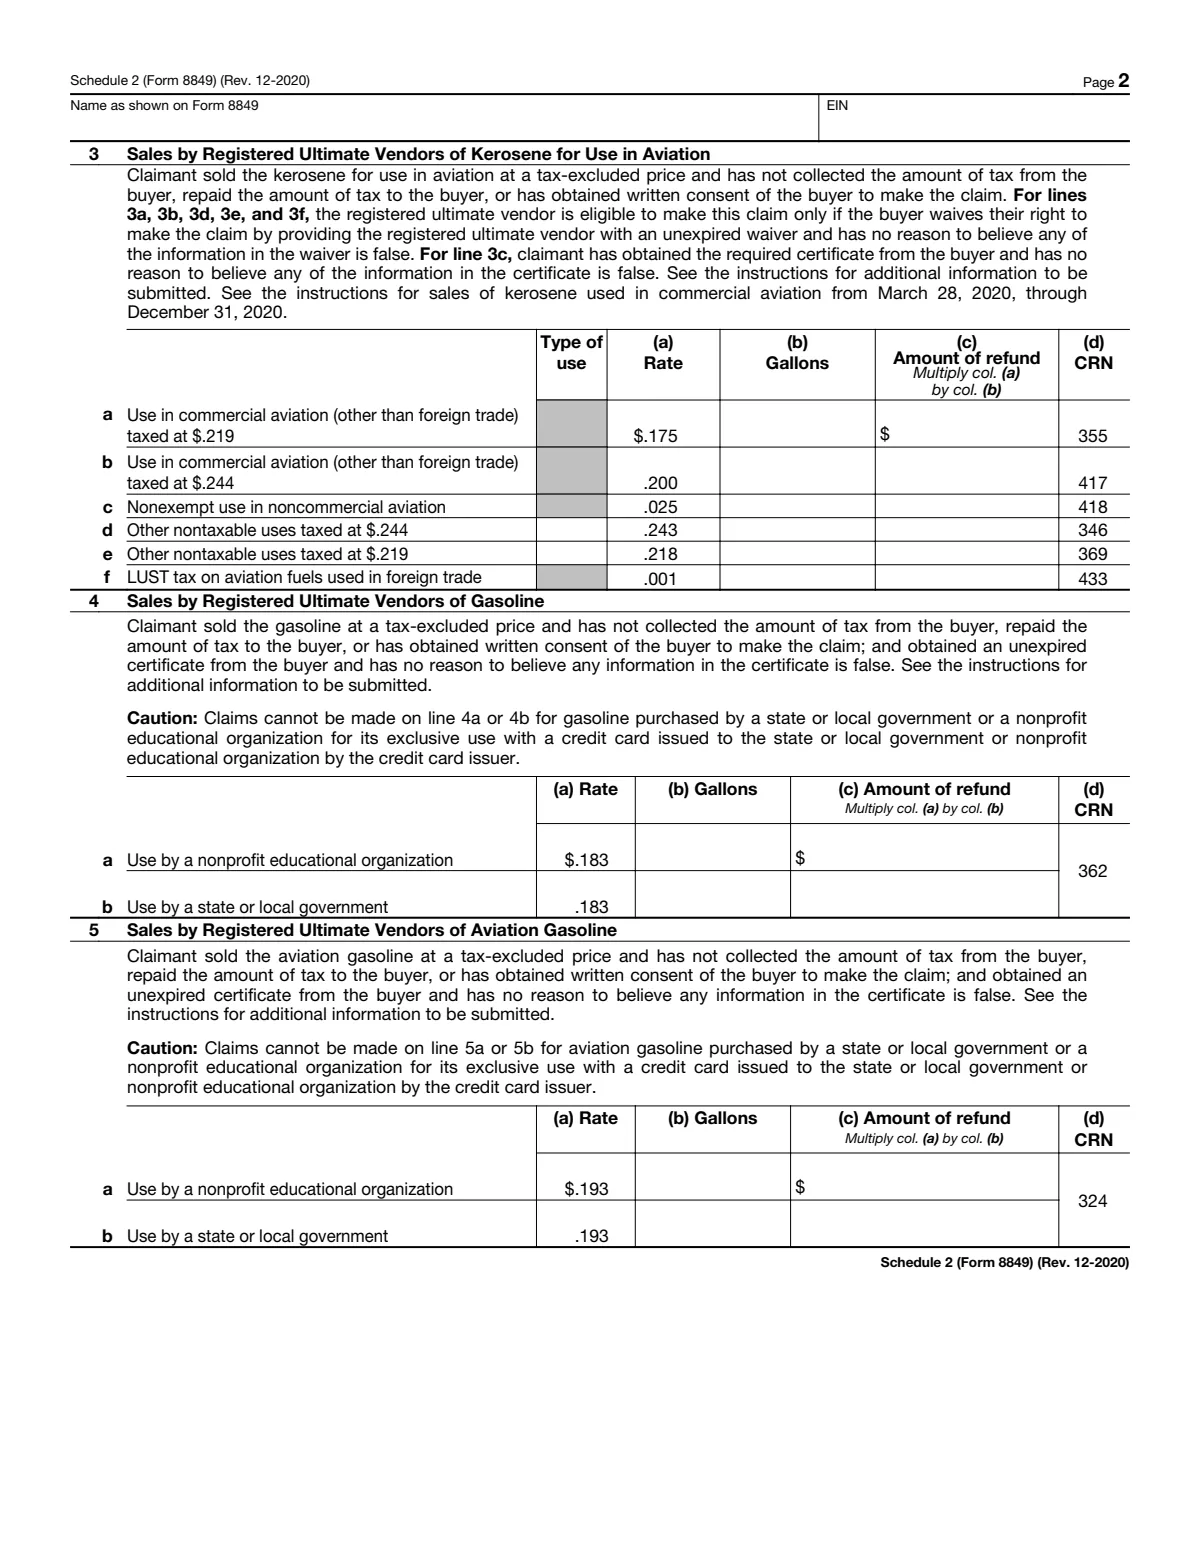
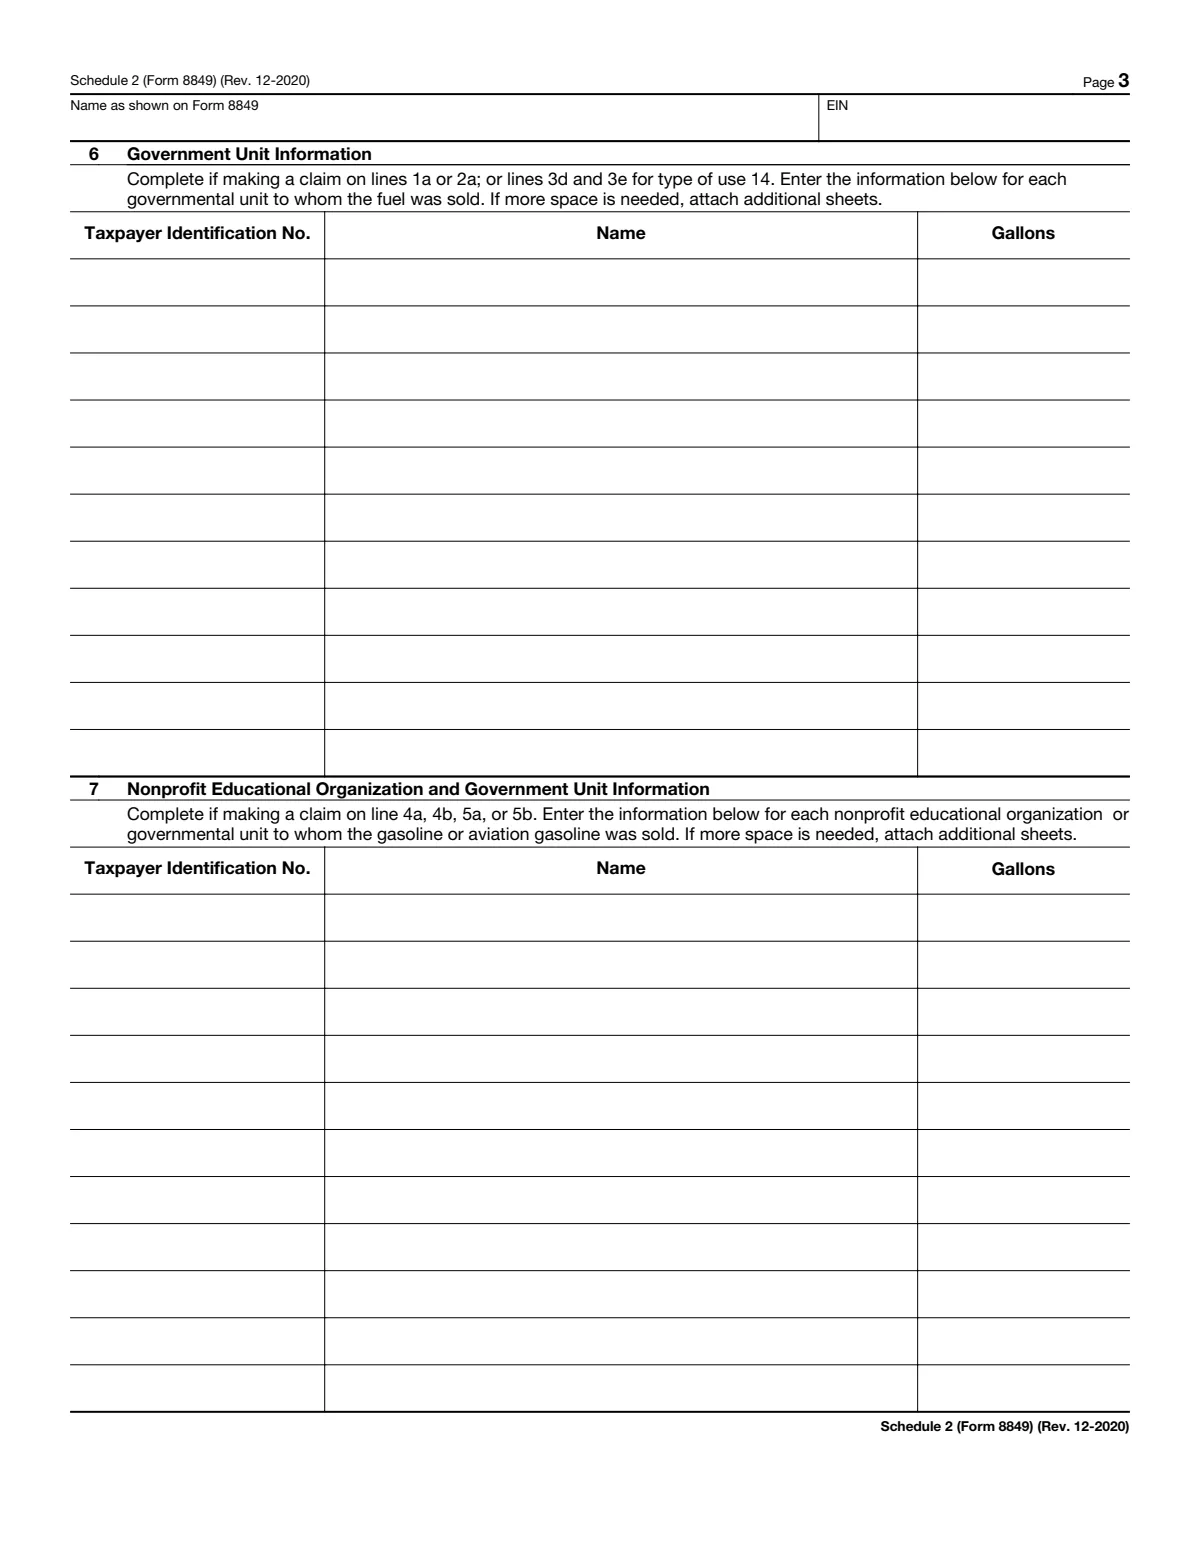
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
| Line | Label | What goes there |
|---|---|---|
| S2-name | Name as shown on Form 8849 | As on the Form 8849; Schedule 2 goes on a Form 8849 of its own. |
| S2-ein | EIN | The registered vendor's EIN. |
| S2-total | Total refund (see instructions) | “Add all amounts in column (c) and enter the result in the total refund box at the top of the schedule.” |
| S2-period | Period of claim: Enter month, day, and year in MMDDYYYY format. From / To | Each claim covers at least a week. “The claim must be filed by the last day of the first quarter following the earliest quarter of the claimant’s income tax year included in the claim.” |
| S2-UV | Claimant's registration no. UV | The UV number, for the government and school lines. “You are registered if you received a letter of registration with a registration number from the IRS that has not been revoked or suspended.” “If you do not have a registration number, you cannot make this claim.” Apply on Form 637. The UV claimant must complete line 6 or 7. |
| S2-UB | UB: Complete for lines 1b and 2c. | The UB number, for bus fuel sold with the buyer's waiver. |
| S2-UP | UP: Complete for line 2b. | The UP number, for kerosene sold from a blocked pump. |
| S2-UA | UA: Complete for line 3. See UV for lines 3d and 3e, type of use 14. | The UA number, for kerosene sold for use in aviation. |
| S2-1 | Sales by Registered Ultimate Vendors of Undyed Diesel Fuel | By filing, the vendor states it “sold the diesel fuel at a tax-excluded price, repaid the amount of tax to the buyer, or obtained written consent of the buyer to make the claim”, holds the certificate or waiver, and the fuel had no visible dye (check the exception box and explain if some did). |
| S2-2 | Sales by Registered Ultimate Vendors of Undyed Kerosene (Other Than Kerosene For Use in Aviation) | The same statements for kerosene, with the blocked pump statement for line 2b. Lines 2 and 3 combine for the $100 minimum. |
| S2-name2 | Name as shown on Form 8849, EIN (page 2) | Repeat the name and EIN at the top of page 2. |
| S2-3 | Sales by Registered Ultimate Vendors of Kerosene for Use in Aviation | Waivers (Model Waiver L) for 3a, 3b and 3d to 3f, and the ultimate purchaser's certificate (Model Certificate Q) for 3c; Model Certificate P for a government buyer (type 14). |
| S2-4 | Sales by Registered Ultimate Vendors of Gasoline | “The registered ultimate vendor of the gasoline or aviation gasoline is eligible to make a claim on lines 4a, 4b, 5a, and 5b if the ultimate purchaser waives his or her right to make the claim by providing the registered ultimate vendor with an unexpired certificate.” |
| S2-5 | Sales by Registered Ultimate Vendors of Aviation Gasoline | The same rules as line 4. Amounts on lines 4a, 4b, 5a and 5b combine for the $200 minimum. |
| S2-name3 | Name as shown on Form 8849, EIN (page 3) | Repeat the name and EIN at the top of page 3. |
| S2-6 | Government Unit Information | “Complete if making a claim on lines 1a or 2a; or lines 3d and 3e for type of use 14.” One row per governmental unit: TIN, name and gallons. Attach sheets if needed. |
| S2-7 | Nonprofit Educational Organization and Government Unit Information | “Complete if making a claim on line 4a, 4b, 5a, or 5b.” TIN, name and gallons for each school or government buyer. |
| S2-1a | Use by a state or local government $.243 | Claim rate printed on the form: $.243 a gallon. CRN 360. “The registered ultimate vendor of the diesel fuel is the only person eligible to make this claim and has obtained the required certificate from the buyer and has no reason to believe any information in the certificate is false.” Model Certificate P is in Pub. 510. List each governmental unit on line 6. A sale paid with the government's own fuel card goes to the card issuer instead (Schedule 8). |
| S2-1b | Use in certain intercity and local buses .17 | Claim rate printed on the form: $.17 a gallon. CRN 350. UB registrant; intercity and local buses; buyer's waiver (Model Waiver N); $200 minimum. The CRN is 350; “If you downloaded Schedule 2 (Form 8849) before December 4, 2020, please note the following:” the CRN on line 1b “should be 350”. |
| S2-2a | Use by a state or local government $.243 | Claim rate printed on the form: $.243 a gallon. UV registrant; kerosene for a state or local government; Model Certificate P; $100 minimum. |
| S2-2b | Sales from a blocked pump .243 | Claim rate printed on the form: $.243 a gallon. CRN 346. UP registrant; kerosene sold from a blocked pump; $100 minimum. “For line 2b, claimant has a statement, if required, that contains the date of sale, name and address of the buyer, and the number of gallons of kerosene sold to the buyer.” |
| S2-2c | Use in certain intercity and local buses .17 | Claim rate printed on the form: $.17 a gallon. CRN 347. UB registrant; kerosene for buses; Model Waiver N; $100 minimum. |
| S2-3a | Use in commercial aviation (other than foreign trade) taxed at $.219 | Claim rate printed on the form: $.175 a gallon. CRN 355. UA registrant; commercial aviation, kerosene taxed at $.219; Model Waiver L. |
| S2-3b | Use in commercial aviation (other than foreign trade) taxed at $.244 | Claim rate printed on the form: $.200 a gallon. CRN 417. UA registrant; commercial aviation, kerosene taxed at $.244; Model Waiver L. |
| S2-3c | Nonexempt use in noncommercial aviation | Claim rate printed on the form: $.025 a gallon. CRN 418. UA registrant; nonexempt noncommercial aviation; Model Certificate Q. “For line 3c, the kerosene must have been sold during the period of claim for a nonexempt use in noncommercial aviation.” |
| S2-3d | Other nontaxable uses taxed at $.244 | Claim rate printed on the form: $.243 a gallon. CRN 346. UA registrant (UV for type 14); other nontaxable uses, taxed at $.244. |
| S2-3e | Other nontaxable uses taxed at $.219 | Claim rate printed on the form: $.218 a gallon. CRN 369. UA registrant (UV for type 14); other nontaxable uses, taxed at $.219. |
| S2-3f | LUST tax on aviation fuels used in foreign trade | Claim rate printed on the form: $.001 a gallon. CRN 433. UA registrant; LUST tax, foreign trade (type 9). |
| S2-4a | Use by a nonprofit educational organization | Claim rate printed on the form: $.183 a gallon. UV registrant; gasoline for a nonprofit educational organization; Model Certificate M; $200 minimum. List each school or government buyer, its TIN and the gallons on line 7. Lines 4 and 5 combine for the $200 minimum. |
| S2-4b | Use by a state or local government | Claim rate printed on the form: $.183 a gallon. CRN 362. UV registrant; gasoline for a state or local government; Model Certificate M. |
| S2-5a | Use by a nonprofit educational organization | Claim rate printed on the form: $.193 a gallon. UV registrant; aviation gasoline for a nonprofit educational organization. |
| S2-5b | Use by a state or local government | Claim rate printed on the form: $.193 a gallon. CRN 324. UV registrant; aviation gasoline for a state or local government. |
On the envelope, write Registered Ultimate Vendor Claim. Interest aside, the e-filed claim is also the faster one to process, since the IRS's 20-day clock applies only to electronic claims.
Schedule 5: section 4081(e) and 6435 claims
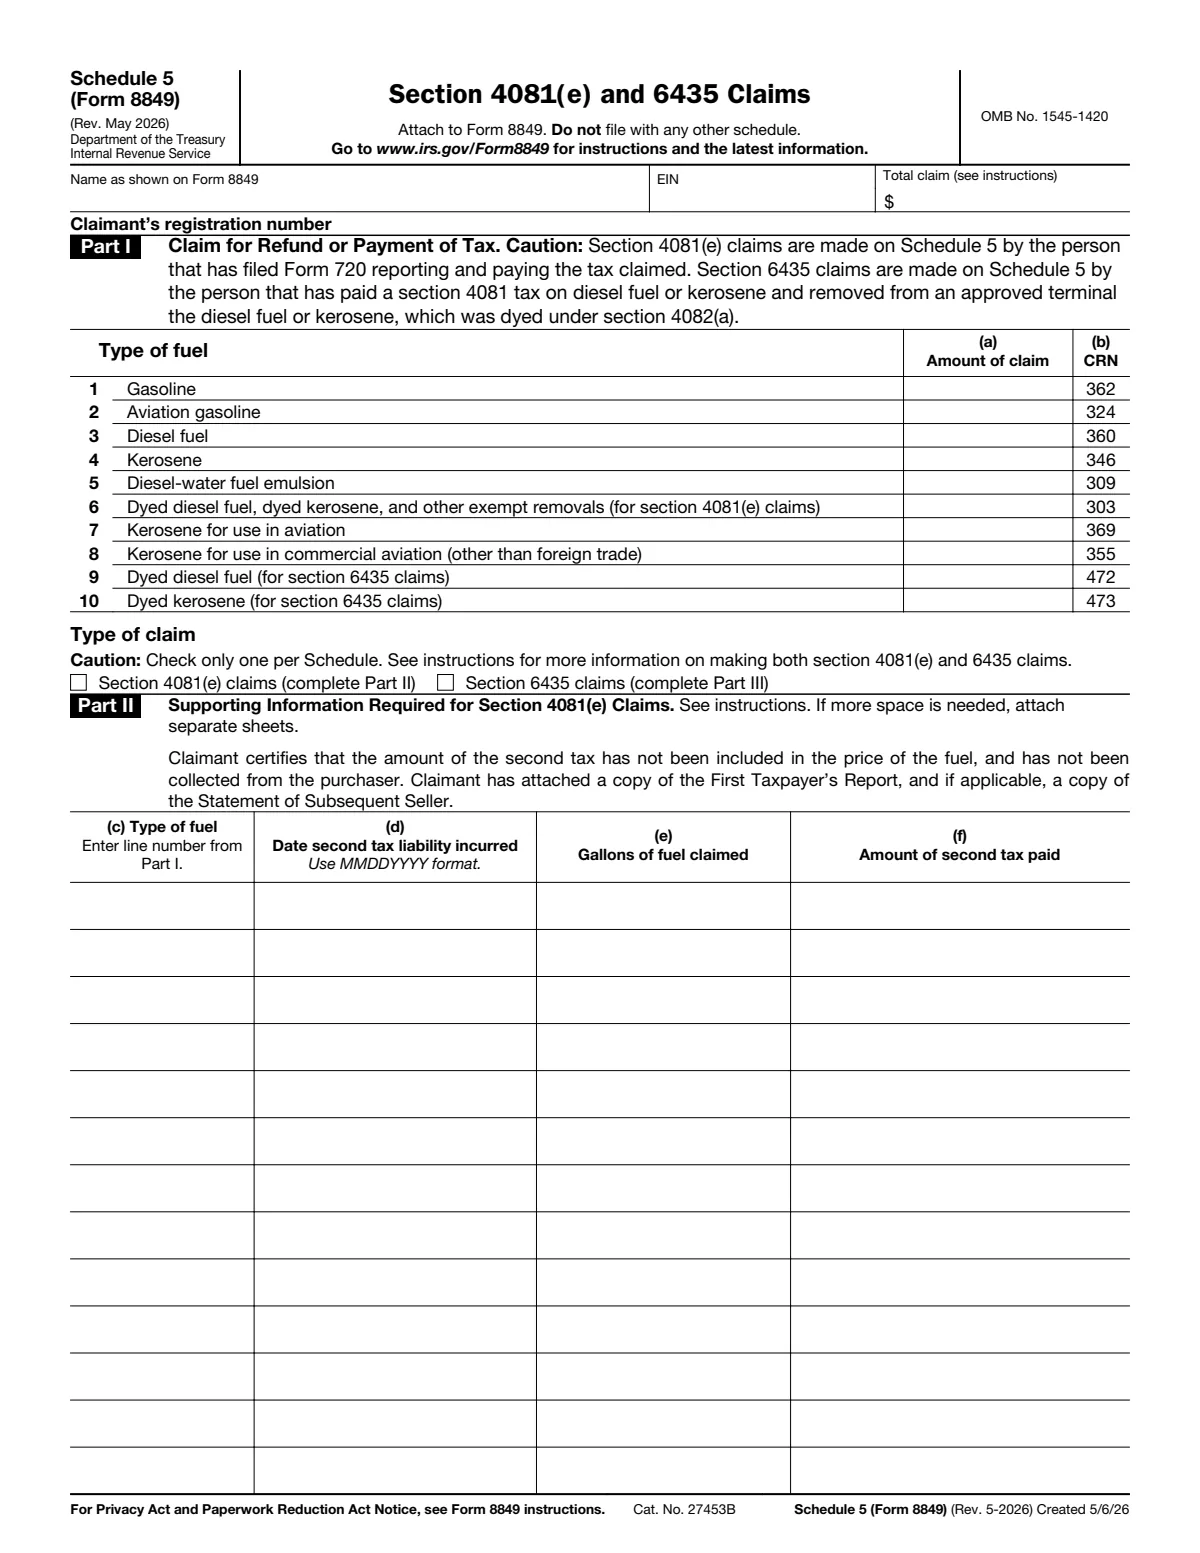
Schedule 5 carries two different claims. Lines 1 to 8 are section 4081(e) claims: when the same gallons are taxed twice in the bulk system, the person that paid the second tax gets it back, with the First Taxpayer's Report as proof. Lines 9 and 10, new on the May 2026 schedule, are section 6435 claims: tax already paid on diesel or kerosene that is later dyed and removed from a terminal for a nontaxable use, for “dyed fuel removed on or after December 31, 2025”. Section 6435 pays “without interest”.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
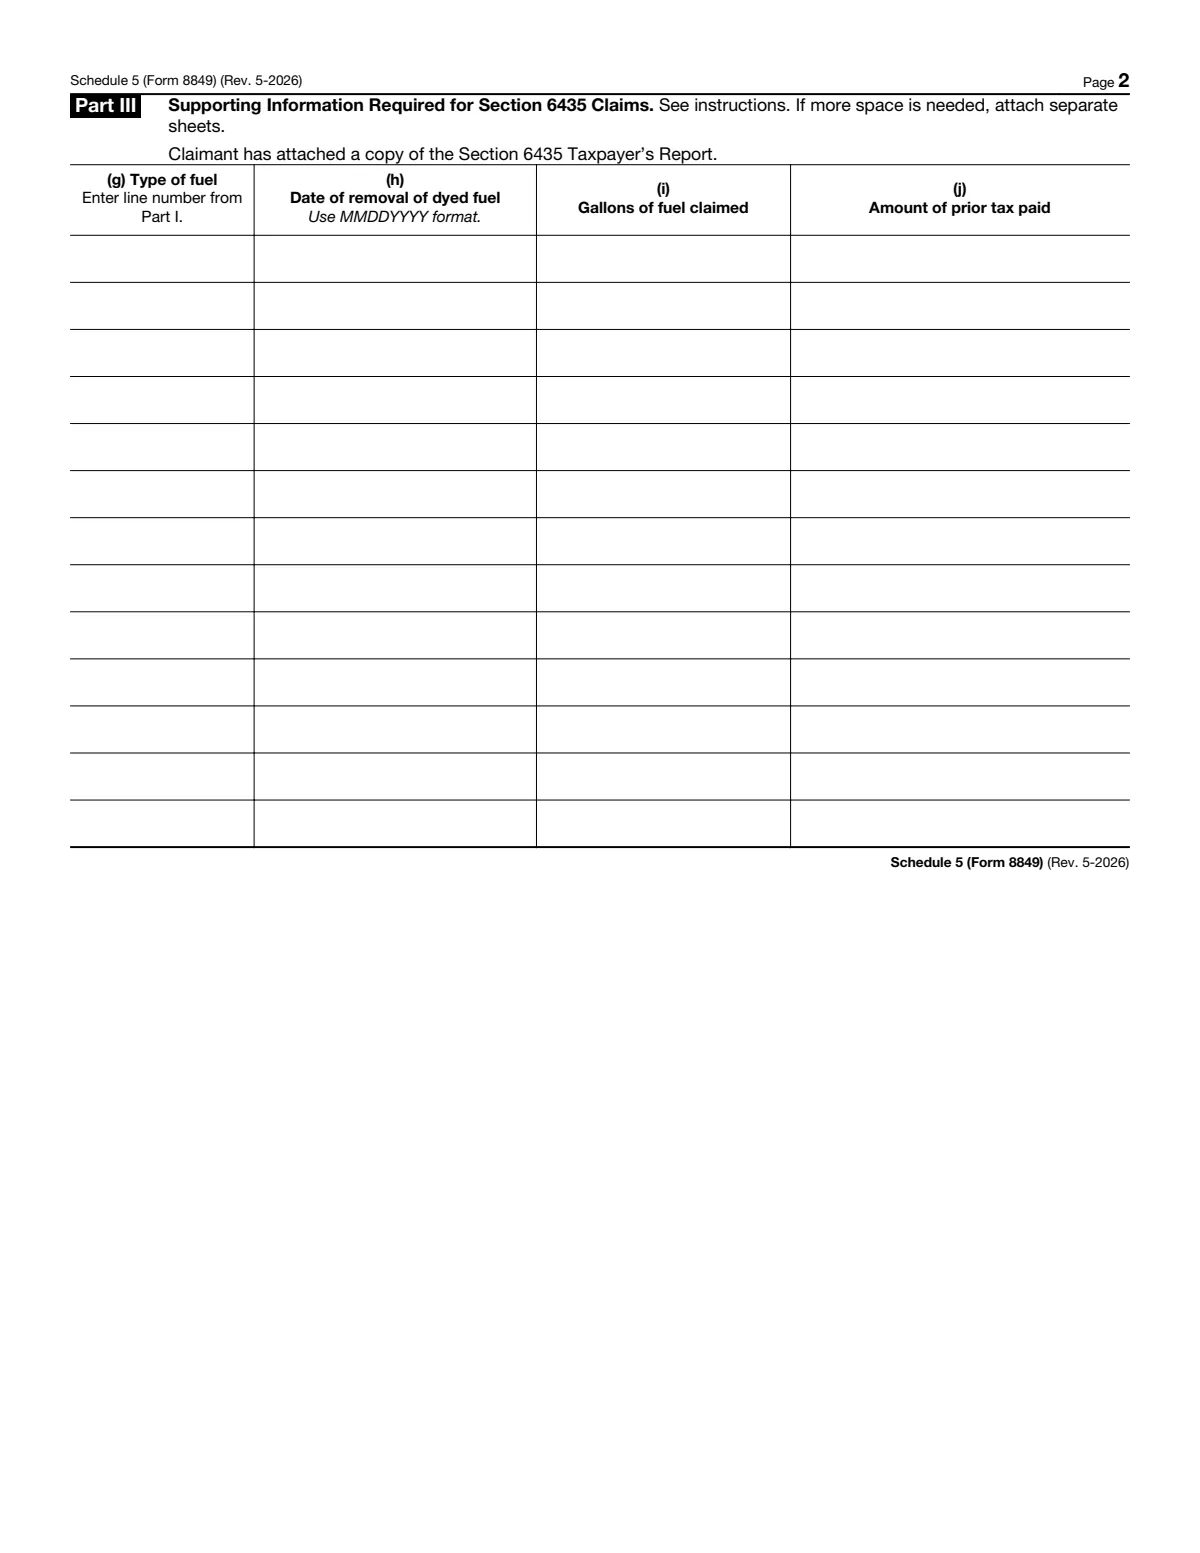
| Line | Label | What goes there |
|---|---|---|
| S5-name | Name as shown on Form 8849 | Schedule 5 goes on a Form 8849 of its own, and 4081(e) and 6435 claims on separate copies. |
| S5-ein | EIN | The claimant's EIN. |
| S5-total | Total claim (see instructions) | “Add all amounts in column (a) and enter the result in the total claim box at the top of the Schedule.” |
| S5-reg | Claimant’s registration number | The claimant's IRS registration number. The examples in the instructions are taxable fuel registrants (activity letter S on Form 637). |
| S5-I | Part I Claim for Refund or Payment of Tax. Caution: ... | “The person that reports on Form 720 and pays the second tax to the government on the same fuel is the only person eligible to make a section 4081(e) claim.” For section 6435, the only claimant is the person that paid the 4081 tax not otherwise credited or refunded and removed the fuel from an approved terminal dyed. |
| S5-1 | Gasoline | CRN 362. A section 4081(e) claim: refund of the second tax paid on the same fuel. Column (a) is the total of column (f) in Part II for this fuel. |
| S5-2 | Aviation gasoline | CRN 324. A section 4081(e) claim: refund of the second tax paid on the same fuel. Column (a) is the total of column (f) in Part II for this fuel. |
| S5-3 | Diesel fuel | CRN 360. A section 4081(e) claim: refund of the second tax paid on the same fuel. Column (a) is the total of column (f) in Part II for this fuel. |
| S5-4 | Kerosene | CRN 346. A section 4081(e) claim: refund of the second tax paid on the same fuel. Column (a) is the total of column (f) in Part II for this fuel. |
| S5-5 | Diesel-water fuel emulsion | CRN 309. A section 4081(e) claim: refund of the second tax paid on the same fuel. Column (a) is the total of column (f) in Part II for this fuel. |
| S5-6 | Dyed diesel fuel, dyed kerosene, and other exempt removals (for section 4081(e) claims) | CRN 303. “Section 4081(e) claims can be made on line 6 for the tax on the following fuels: dyed diesel fuel, dyed kerosene, and other exempt removals (gasoline blendstocks, kerosene used for a feedstock, and diesel fuel or kerosene used in Alaska).” |
| S5-7 | Kerosene for use in aviation | CRN 369. A section 4081(e) claim for kerosene the claimant reported on IRS No. 69 when a prior 4081 tax was also paid. |
| S5-8 | Kerosene for use in commercial aviation (other than foreign trade) | CRN 355. A section 4081(e) claim for kerosene reported on IRS No. 77 (commercial aviation) when a prior 4081 tax was also paid. |
| S5-9 | Dyed diesel fuel (for section 6435 claims) | CRN 472. A section 6435 claim, new on the May 2026 schedule: “Use line 9 for section 6435 claims for dyed diesel fuel, effective December 31, 2025, and later.” Column (a) is the total of column (j) in Part III. See the hold below. |
| S5-10 | Dyed kerosene (for section 6435 claims) | CRN 473. A section 6435 claim for dyed kerosene, on the same terms as line 9. Column (a) is the total of column (j) in Part III. See the hold below. |
| S5-type | Type of claim: Section 4081(e) claims (complete Part II) / Section 6435 claims (complete Part III) | “Caution: Check only one per Schedule.” “If you are making both section 4081(e) claims and section 6435 claims, file separate copies of Form 8849 and Schedule 5 with the appropriate checkbox in Part I marked for each set of claims.” |
| S5-II | Part II Supporting Information Required for Section 4081(e) Claims | The claimant certifies the second tax was not included in the price or collected from the buyer, and attaches the First Taxpayer's Report and, if the fuel was bought from someone other than the first taxpayer, the Statement of Subsequent Seller (Model Certificates A and B in Pub. 510). “Generally, a section 4081(e) claim must be filed within 3 years from the time the return for the second tax was filed or 2 years from the time the second tax was paid to the government, whichever is later.” |
| S5-c | (c) Type of fuel: Enter line number from Part I. | “For each payment of a second tax, complete all the information required.” |
| S5-d | (d) Date second tax liability incurred. Use MMDDYYYY format. | The date of the taxable event that created the second tax, such as the rack removal. |
| S5-e | (e) Gallons of fuel claimed | Gallons that bore both taxes. |
| S5-f | (f) Amount of second tax paid | The second tax on those gallons. The instructions' example: 10,000 gallons of gasoline, $1,840.00, the same figure entered in column 1(a). |
| S5-III | Part III Supporting Information Required for Section 6435 Claims. Claimant has attached a copy of the Section 6435 Taxpayer's Report. | Attach a Section 6435 Taxpayer's Report with “all the information as shown in the model in the Treasury Regulation 48.6435-1T(e)(2).” (26 CFR 48.6435-1T). |
| S5-g | (g) Type of fuel: Enter line number from Part I. | 9 for dyed diesel, 10 for dyed kerosene. “For each removal of a dyed fuel eligible for a section 6435 claim, complete all the information required.” |
| S5-h | (h) Date of removal of dyed fuel. Use MMDDYYYY format. | The date the dyed fuel left the approved terminal. |
| S5-i | (i) Gallons of fuel claimed | Gallons dyed and removed. |
| S5-j | (j) Amount of prior tax paid | The 4081 tax paid earlier on those gallons, including the LUST part. The instructions' example: 5,000 of 10,000 taxed gallons dyed and removed, $1,220 of the $2,440 paid. |
The section 6435 hold. The schedule and the temporary regulation (T.D. 10047) are out, but the IRS is not paying yet. In Announcement 2026-1 the IRS asked “that taxpayers hold any § 6435 claims until this guidance is issued” and said “The IRS will not process any § 6435 claims until such guidance is issued.” Its campus manual, revised July 16, 2026, still says “These claims should be held in suspense until further notice.” (IRM 4.24.22.3.2). As of November 2026 we found no IRS notice lifting the hold. The deadline is the general refund period: a claim may be filed “any time after the removal of the dyed fuel and before the end of the period prescribed by section 6511”. The Form 8849 guide follows the hold, and the section 6435 refund guide explains how to file the claim. On the envelope, write Section 4081(e) Claim or Section 6435 Claim.
Schedule 6: other claims
Schedule 6 is the catch-all: “Use Schedule 6 for claims not reportable on Schedules 1, 2, 3, 5, and 8, including refunds of excise taxes reported on:” Form 720, Form 2290, Form 730 and Form 11-C. Each line names a tax, its amount and its CRN, and the explanation space (or attached sheets) carries what the instructions require for that CRN. The Form 720 taxes that can be claimed here, with their CRNs, read from the Schedule 6 instructions:
| Tax (Form 720) | CRN |
|---|---|
| Ozone-depleting chemicals | 398 |
| Truck, trailer, and semitrailer chassis and bodies, and tractors | 383 |
| Passenger vehicles (luxury tax) | 392 |
| Taxable tires other than biasply or super single tires | 396 |
| Taxable tires, biasply or super single tires | 304 |
| Taxable tires, super single tires designed for steering | 305 |
| Gas guzzler automobiles | 340 |
| Vaccines | 397 |
| Taxable medical devices | 438 |
| Sport fishing equipment | 341 |
| Fishing rods and fishing poles | 308 |
| Fishing tackle boxes | 387 |
| Electric outboard motors | 342 |
| Bows, quivers, broadheads, and points | 344 |
| Arrow shafts | 389 |
| Imported chemical substances | 317 |
| Transportation of persons by air | 326 |
| Use of international air travel facilities | 327 |
| Transportation of property by air | 328 |
| Repurchase of corporate stock | 441 |
| Chemicals (other than ODCs) | 454 |
| Remittance transfer tax | 475 |
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
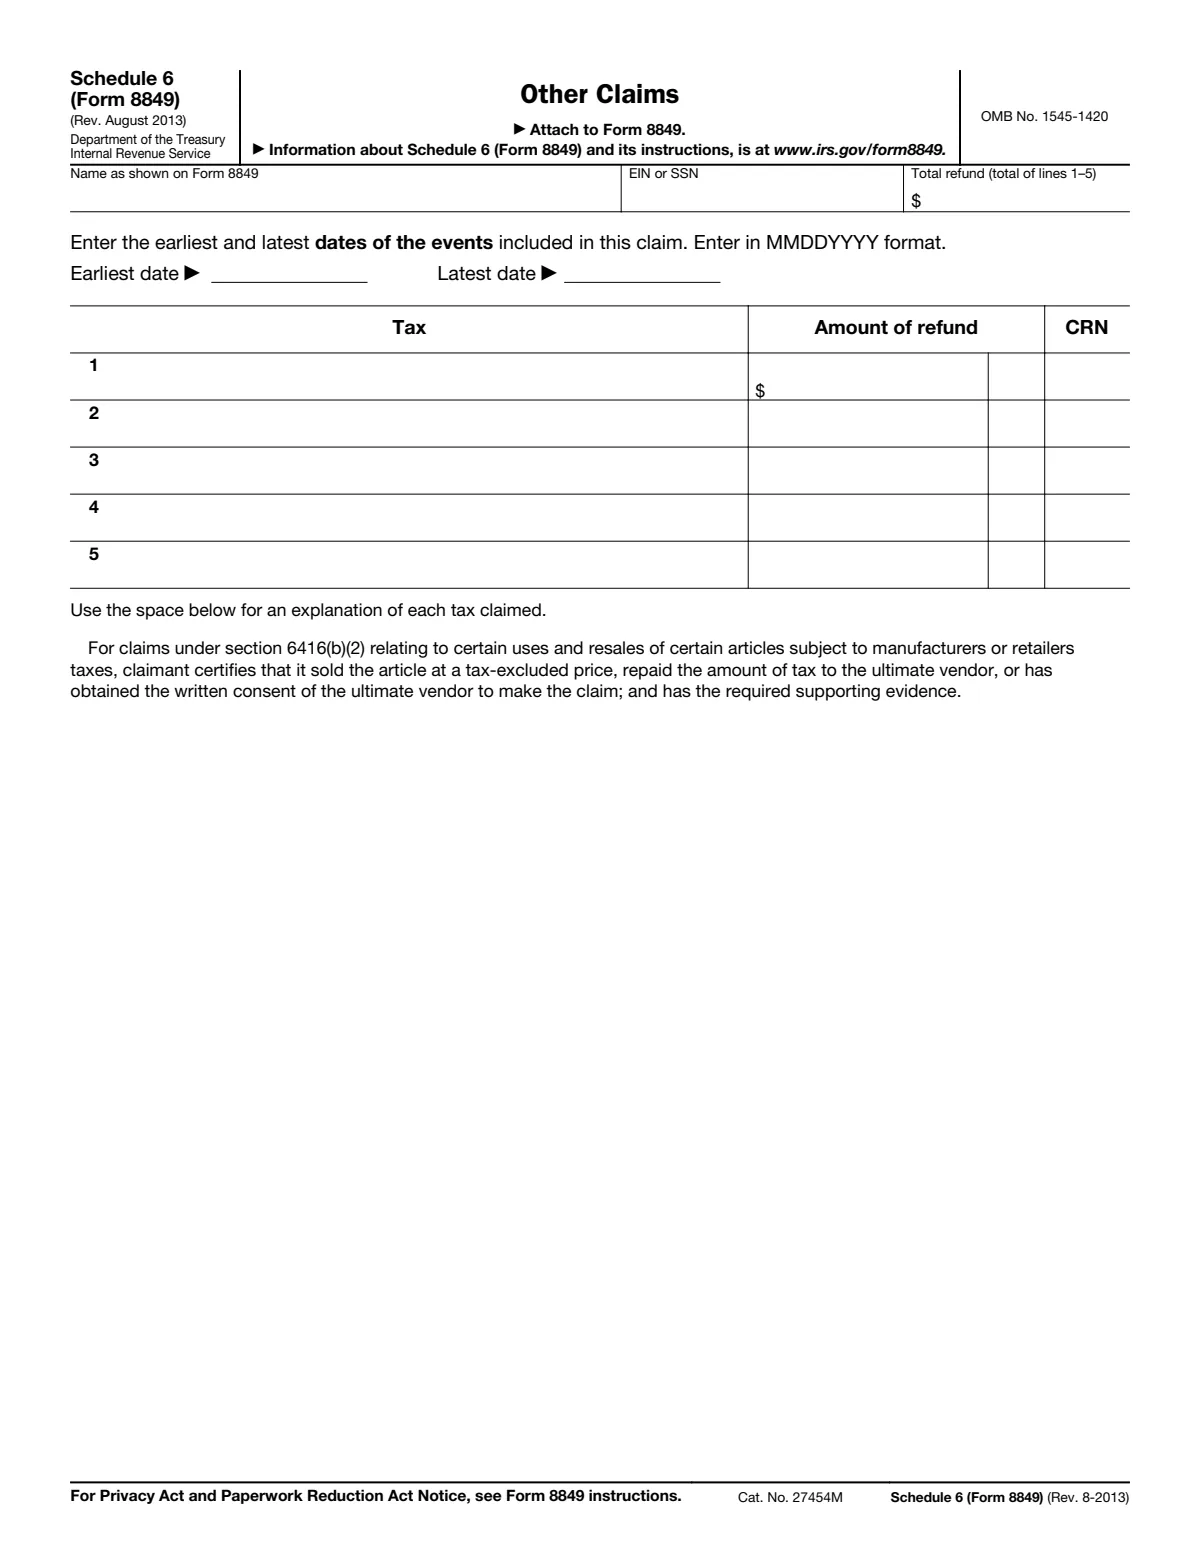
| Line | Label | What goes there |
|---|---|---|
| S6-name | Name as shown on Form 8849 | As on the Form 8849. Schedule 6 can share a Form 8849 with Schedule 1. |
| S6-ein | EIN or SSN | As on the Form 8849. |
| S6-total | Total refund (total of lines 1 to 5) | The sum of the amounts on lines 1 to 5. |
| S6-dates | Enter the earliest and latest dates of the events included in this claim. | For a Form 720 tax, the dates of the sales or uses; for a Form 2290 mileage claim, the tax period. “Generally, a claim must be filed within 3 years of the filing of the return to which the claim relates, or 2 years from when the tax reported on that return was paid, whichever is later.” |
| S6-1 | Line 1: Tax / Amount of refund / CRN | Name the tax, the amount and the CRN. For a Form 720 tax, attach “A detailed description of the claim.”, the amount by quarter and how you figured it. The CRNs are in the table below. Form 2290 refunds use CRN 365, Form 730 CRN 368 and Form 11-C CRN 367. |
| S6-2 | Line 2 | A second tax, if any, with its own CRN. |
| S6-3 | Line 3 | A third tax, if any. |
| S6-4 | Line 4 | A fourth tax, if any. |
| S6-5 | Line 5 | A fifth tax; use attached sheets for more, with your name and TIN on each. |
| S6-explain | Use the space below for an explanation of each tax claimed. | The explanation and the certification for section 6416(b)(2) claims on manufacturers and retailers taxes: “claimant certifies that it sold the article at a tax-excluded price, repaid the amount of tax to the ultimate vendor, or has obtained the written consent of the ultimate vendor to make the claim; and has the required supporting evidence.” |
Remittance transfers. New for 2026, a sender whose remittance was cancelled or expired, and who did not get the 1% tax back from the provider, claims it here under CRN 475: “The claim is made by the sender who paid the remittance transfer tax to the remittance transfer provider.” The claim needs a statement that the provider did not refund the tax and the provider's receipts. Providers themselves do not use Form 720-X for this (see the remittance transfer tax guide).
Truckers and Form 2290. CRN 365 covers a 2290 overpayment, a vehicle sold, destroyed or stolen before June 1 and not used again in the period, and a vehicle used “5,000 miles or less on public highways (7,500 or less for agricultural vehicles)”; “A claim for this mileage refund cannot be filed until after June 30 of the period.” For a vehicle sold, attach the VIN, weight category, date and computation, and the buyer's name and address. IFTACompliance.com covers this from the carrier's side: Schedule 6 and Form 2290 refunds.
Schedule 8: credit card issuers
Schedule 8 lets a registered credit card issuer claim the tax on fuel bought with its card by a state or local government or a nonprofit school. It is the first claimant in the order the Form 8849 instructions set for those sales. The form is the October 2006 revision; its instructions are on page 2.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
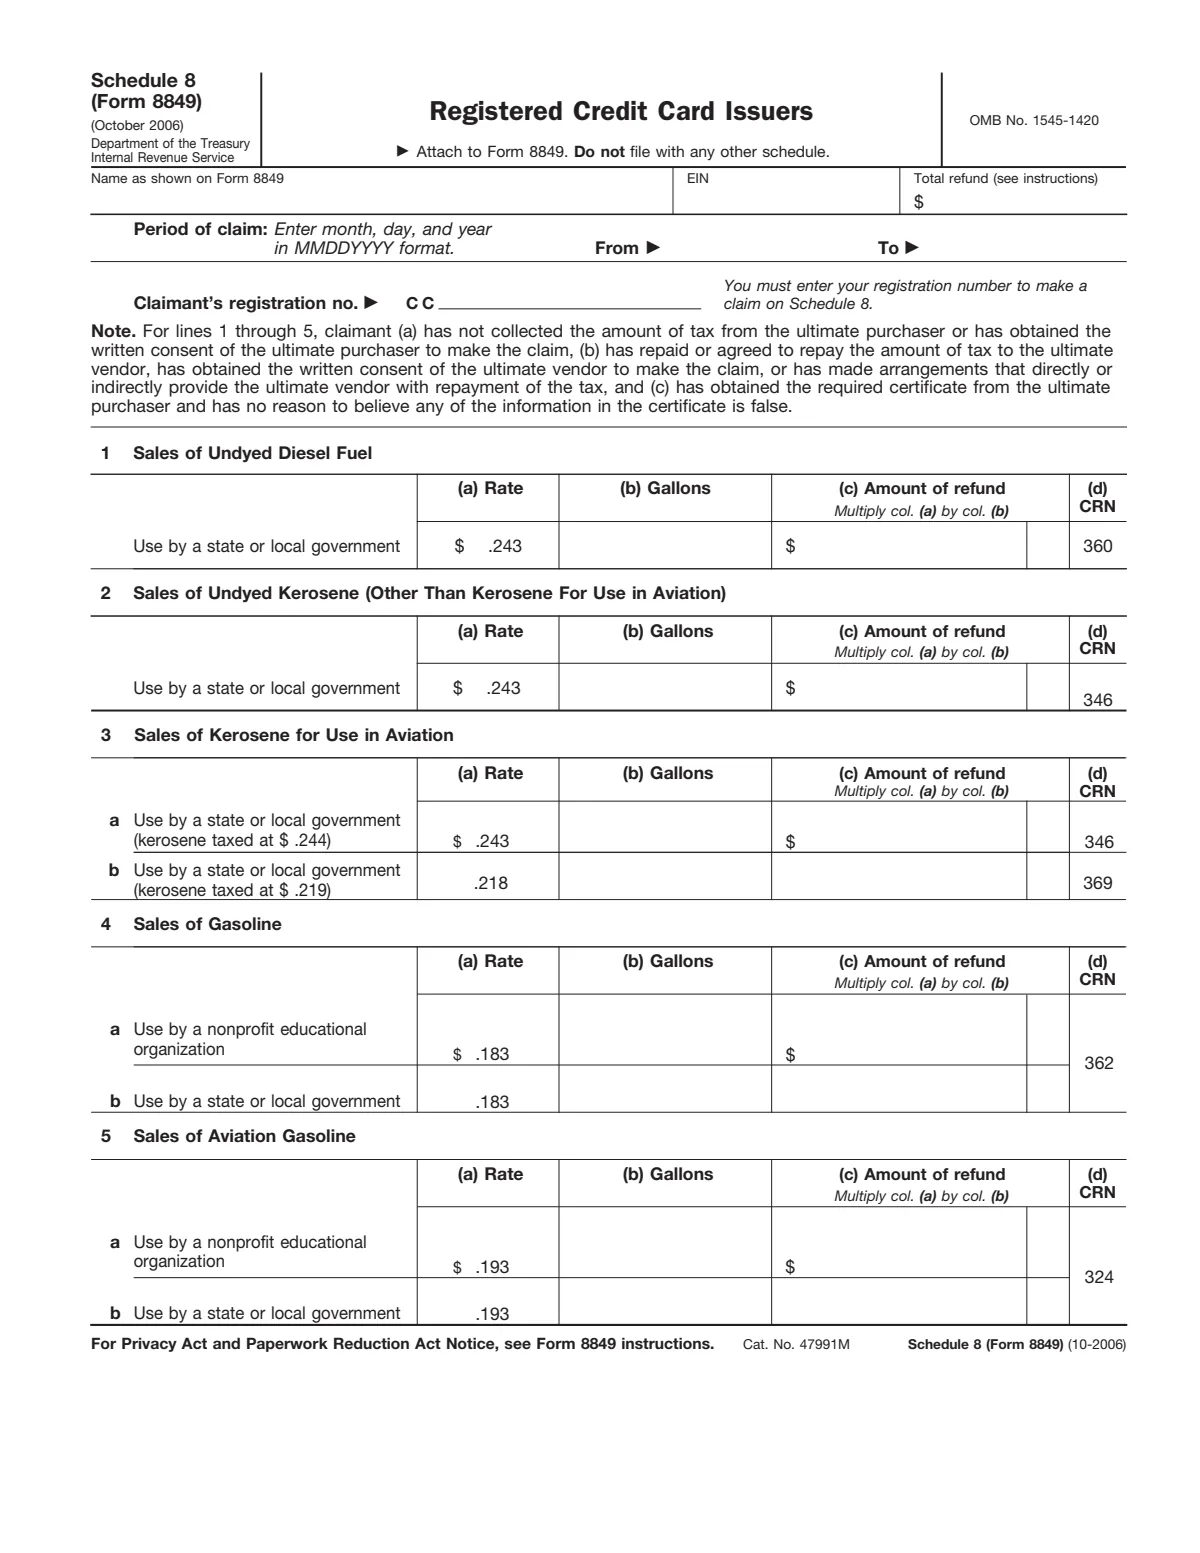
| Line | Label | What goes there |
|---|---|---|
| S8-name | Name as shown on Form 8849 | Schedule 8 goes on a Form 8849 of its own. |
| S8-ein | EIN | The card issuer's EIN. |
| S8-total | Total refund (see instructions) | “Add all amounts in column (c) and enter the result in the total refund box at the top of the schedule.” |
| S8-period | Period of claim: Enter month, day, and year in MMDDYYYY format. From / To | “The claim must be for taxable fuel sold during a period that is at least 1 week.” “The amount of the claim must be at least $200. To meet this minimum, amounts from lines 1 through 5 may be combined.” |
| S8-reg | Claimant's registration no. CC | “You must enter your registration number.” “If you do not have a registration number, you cannot make this claim.” Letter CC on Form 637. |
| S8-note | Note. For lines 1 through 5, claimant (a) has not collected the amount of tax ... (c) has obtained the required certificate | The issuer states it has not collected the tax from the buyer (or has its consent), has repaid or agreed to repay the vendor, and holds the buyer's certificate (Model Certificate R in Pub. 510). The fuel must have been bought with a card the issuer gave the government or school. |
| S8-1 | Use by a state or local government | Claim rate printed on the form: $.243 a gallon. CRN 360. Gallons sold to the government or school with the issuer's card, times the rate. |
| S8-2 | Use by a state or local government | Claim rate printed on the form: $.243 a gallon. CRN 346. Gallons sold to the government or school with the issuer's card, times the rate. |
| S8-3 | Sales of Kerosene for Use in Aviation | Two lines by the tax rate the kerosene bore: $.244 (line 3a) or $.219 (line 3b). |
| S8-3a | a Use by a state or local government (kerosene taxed at $ .244) | Claim rate printed on the form: $.243 a gallon. CRN 346. Gallons sold to the government or school with the issuer's card, times the rate. |
| S8-3b | b Use by a state or local government (kerosene taxed at $ .219) | Claim rate printed on the form: $.218 a gallon. CRN 369. Gallons sold to the government or school with the issuer's card, times the rate. |
| S8-4 | Sales of Gasoline | Gasoline for a nonprofit educational organization (4a) or a state or local government (4b). |
| S8-4a | a Use by a nonprofit educational organization | Claim rate printed on the form: $.183 a gallon. CRN 362. Gallons sold to the government or school with the issuer's card, times the rate. |
| S8-4b | b Use by a state or local government | Claim rate printed on the form: $.183 a gallon. CRN 362. Gallons sold to the government or school with the issuer's card, times the rate. |
| S8-5 | Sales of Aviation Gasoline | Aviation gasoline for the same two buyers. |
| S8-5a | a Use by a nonprofit educational organization | Claim rate printed on the form: $.193 a gallon. CRN 324. Gallons sold to the government or school with the issuer's card, times the rate. |
| S8-5b | b Use by a state or local government | Claim rate printed on the form: $.193 a gallon. CRN 324. Gallons sold to the government or school with the issuer's card, times the rate. |
On the envelope, write Registered Credit Card Issuer Claim. A card issuer claim the IRS does not pay within 20 days (e-filed) or 45 days (paper) earns interest, the same as Schedule 2.
Schedule 3: closed after 2024
Schedule 3 (Certain Fuel Mixtures and the Alternative Fuel Credit) carried the section 6427 payments for biodiesel, renewable diesel, SAF and alternative fuel mixtures. “Do not file Schedule 3 (Form 8849) for any claims related to these payments after 2024.” For sales, uses or removals on or before Dec. 31, 2024, the instructions say to use the August 2014 Form 8849 and the January 2023 Schedule 3 (the IRS notice on the January 2023 Schedule 3). Because no current claim can use it, Schedule 3 has no image or hotspots on this page.
Rules that trip filers up
- Mixing schedules. Schedules 2, 5 and 8 each need their own Form 8849, and the mailing address differs from Schedules 1 and 6.
- Claiming a gallon twice. The signature declares the amounts were not and will not be claimed on another form. A gallon claimed on Schedule 1 cannot also go on Form 720 Schedule C or Form 4136.
- Using Form 8849 to amend Form 720. That is Form 720-X. Use Schedule 6 for refunds of tax correctly reported but later refundable, such as tires sold on a taxable vehicle or articles later exported.
- A vendor claim without a live registration. The IRS manual tells staff “If the registration number provided on the schedule is not on file or is revoked or suspended, reject the claim” (IRM 4.24.22.4.5.3).
- Old schedule revisions. Schedules 1, 2, 6 and 8 are older than the May 2026 form but current: the IRS's About Form 8849 page links each one. Schedule 2 copies downloaded before Dec. 4, 2020 print the wrong CRN on line 1b.
- Waiting on section 6435. File within the section 6511 period even while the IRS holds the claims.
How it connects
- The guide behind this form: Form 8849: excise tax refund claims and schedules, with its sections on interest and the section 6435 hold.
- The other ways to get fuel tax back: Form 4136 (annual credit), Schedule C of Form 720, and the tax-free sales that avoid the tax in the first place.
- Registration for Schedules 2, 5 and 8: Form 637 line by line and the Form 637 registration guide. Dyed fuel: dyed fuel and the section 6435 refund.
- After you file: excise refund claims.
Questions filers ask
Where do I mail Form 8849?
With Schedule 1 or 6: Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0002. With Schedule 2, 5 or 8: Internal Revenue Service, P.O. Box 312, Covington, KY 41012-0312, by U.S. mail. Or e-file through the IRS e-file program for excise taxes.
What is the minimum for a Schedule 1 claim?
$750, which can combine quarters of the income tax year with no other claim. File in the first quarter after the last quarter included, one claim a quarter. Otherwise take the gallons as an annual claim, usually on Form 4136.
Can I file Schedules 1 and 6 together?
Yes. Schedules 2, 5 and 8 must each be filed alone on their own Form 8849, but Schedules 1 and 6 can be attached to the same Form 8849.
Is the IRS paying section 6435 dyed fuel claims on Schedule 5?
Not as of November 2026. Announcement 2026-1 asked claimants to hold them and the IRS manual revised July 16, 2026 tells staff to hold them in suspense. Lines 9 and 10 of the May 2026 Schedule 5 are for these claims; file within the section 6511 period.
What CRN do I use on Schedule 6 for a Form 2290 refund?
CRN 365, for an overpayment, a vehicle sold, destroyed or stolen, or a vehicle used 5,000 miles or less (7,500 for agricultural vehicles). The mileage claim cannot be filed until after June 30 of the period.
Do I need a registration number for Schedule 2 or 8?
Yes. You must have an unrevoked IRS letter of registration: UV, UB, UP or UA for Schedule 2, CC for Schedule 8. Without one you cannot make the claim; apply on Form 637.
Sources
- Form 8849, Claim for Refund of Excise Taxes (Rev. May 2026), with instructions, PDF
- Schedule 1 (Form 8849) (Rev. May 2020), PDF
- Schedule 2 (Form 8849) (Rev. December 2020), PDF
- Schedule 5 (Form 8849) (Rev. May 2026), PDF
- Schedule 6 (Form 8849) (Rev. August 2013), PDF
- Instructions for Schedule 6 (Form 8849) (Rev. June 2026)
- Schedule 8 (Form 8849) (October 2006), PDF
- About Form 8849 (Instructions for Schedule 5, Rev. May 2026, are linked from the IRS's Form 8849 pages)
- Announcement 2026-1, Section 6435 dyed fuel tax claims
- 26 U.S.C. 6427 and 6435
- IRM 4.24.22, Campus Procedures for Excise Taxes