- Who files
- Covered corporations and certain affiliates
- Filed with
- Form 720, first full quarter after year end
- Rate
- 1% of net repurchases (IRC 4501)IRC 4501Internal Revenue Code, Cornell LII
- Form revision
- June 2024 (instructions Rev. December 2025)
- Pages
- 2
At a glance
Form 7208 figures the 1% excise tax on stock buybacks. “Use Form 7208 to figure the excise tax on stock repurchases.” The tax applies to repurchases after 2022 by domestic corporations whose stock trades on an established securities market, and by certain affiliates of foreign publicly traded corporations and surrogate foreign corporations. It is an annual return attached to a quarterly one.
- Who files. A covered corporation, an applicable specified affiliate of an applicable foreign corporation, or an expatriated entity with respect to a covered surrogate foreign corporation. “A covered corporation that is a regulated investment company (RIC), as defined in section 851, a real estate investment trust (REIT), as defined in section 856(a), or a non-RIC '40 Act fund (as described in Regulations section 58.4501-3(h)), does not need to file Form 7208.”
- When. Once a year: “Attach your Form 7208 to the Form 720, due for the first full quarter after the close of your tax year.” A calendar-year corporation files with the first-quarter Form 720, due April 30.
- Paid how. With the Form 720. IRS No. 150 is a Part II tax, and the Form 720 instructions list among the no-deposit cases “The liability is for taxes listed in Form 720, Part II, except the floor stocks tax, which generally requires a single deposit.”
- Form revision. Form 7208 (June 2024) with the Instructions for Form 7208 (Rev. December 2025). Two pages, five parts. The IRS added a When to File Form 7208 notice on Aug. 11, 2026.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
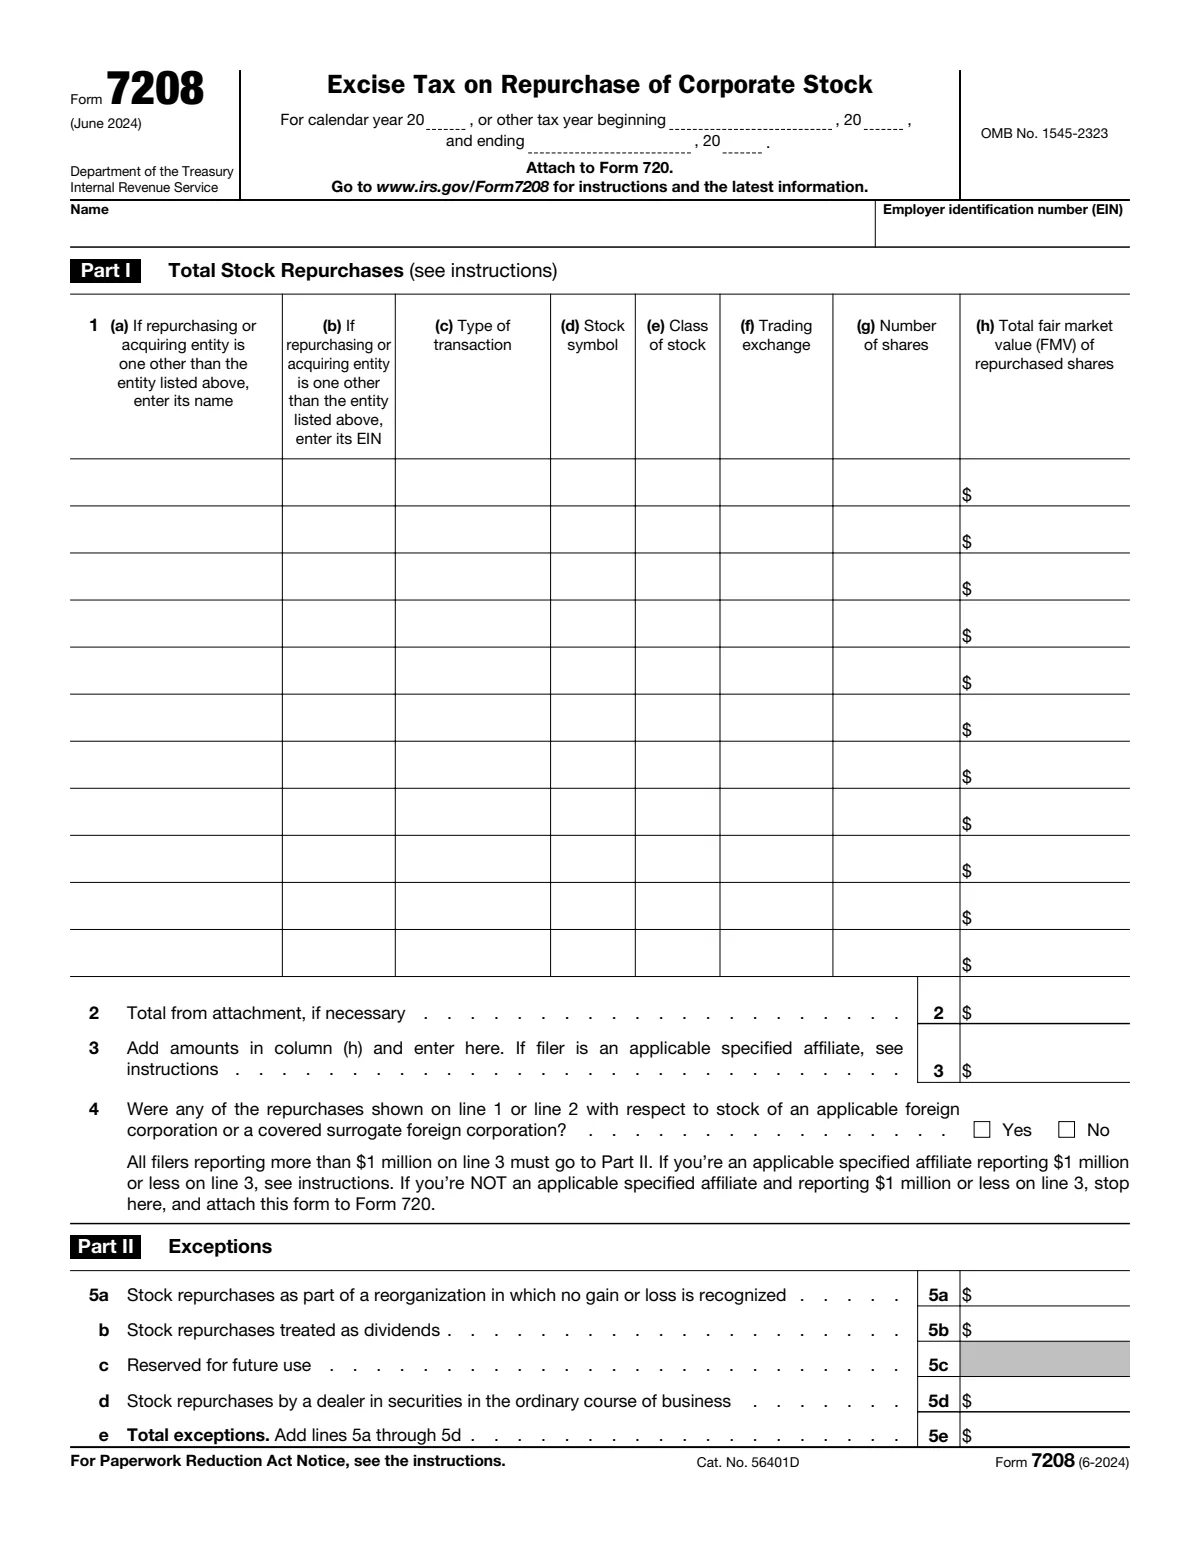
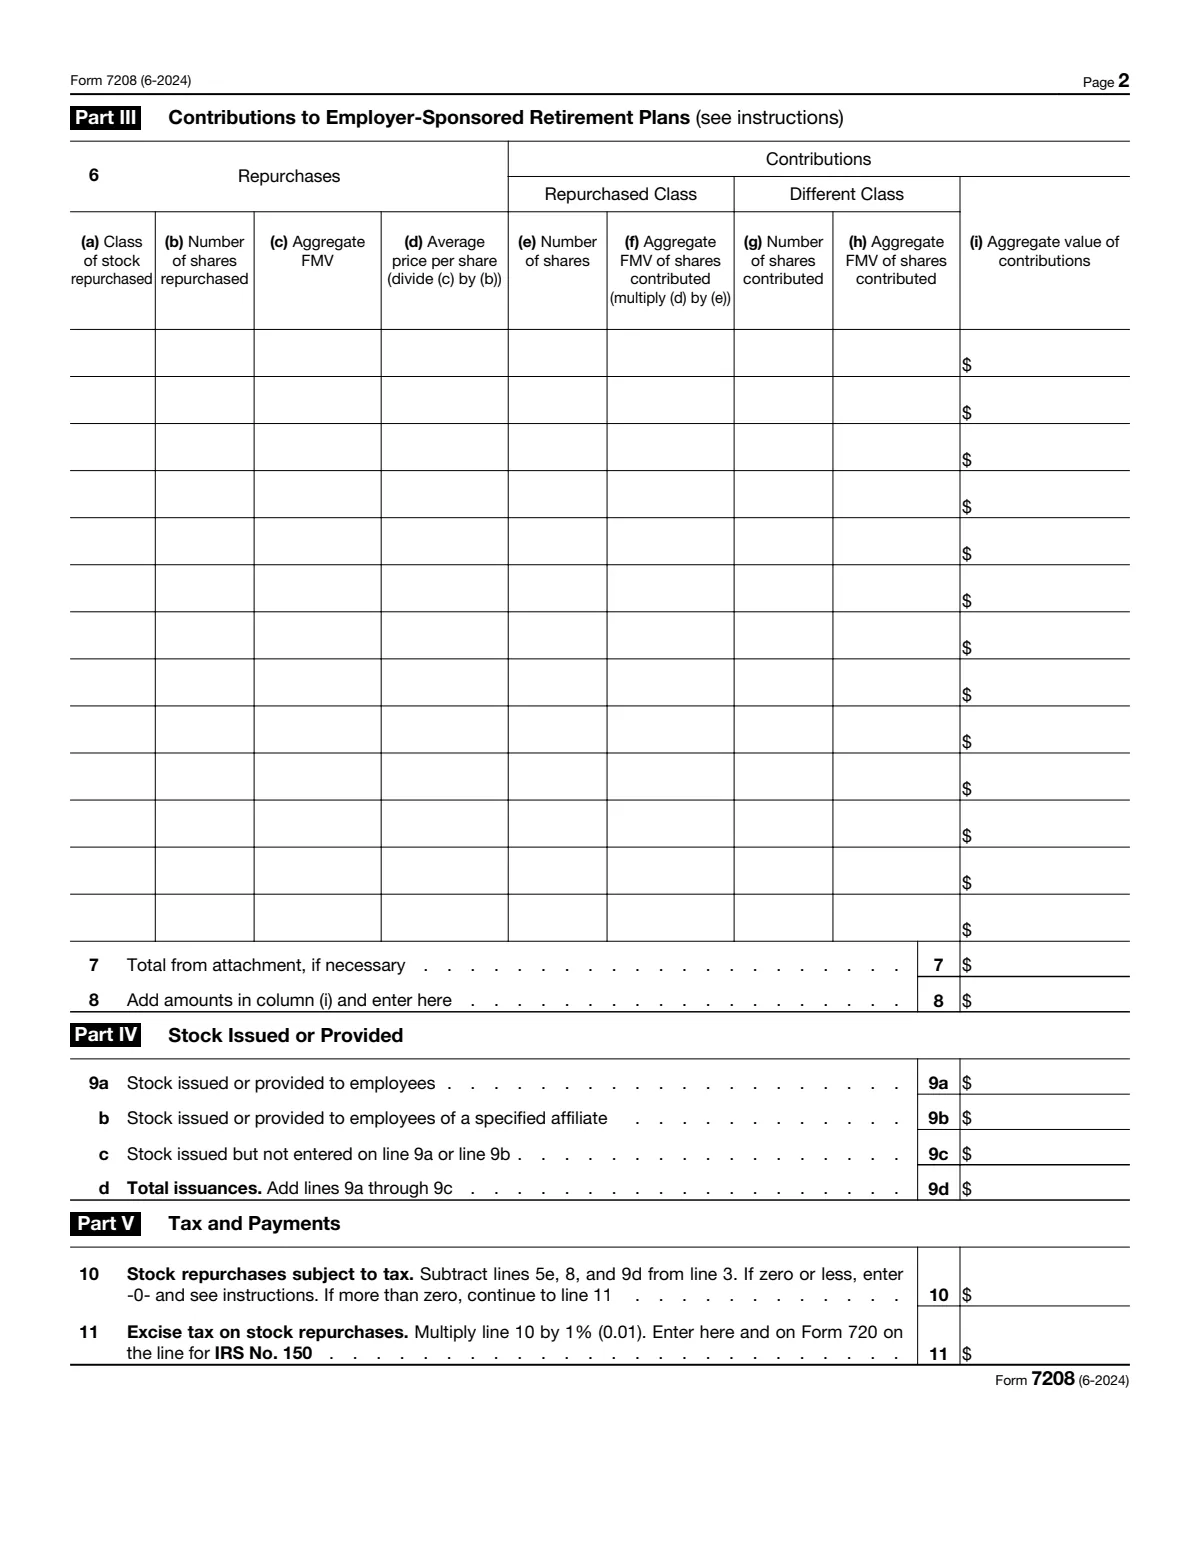
Form 7208 (June 2024) and its instructions (Rev. December 2025); 26 U.S.C. 450126 U.S.C. 4501United States Code, Cornell LII.
Tax year, name and EIN
| Line | Label | What goes there |
|---|---|---|
| 7208-year | For calendar year 20__, or other tax year beginning ____, 20__, and ending ____, 20__ | “Enter your tax year for which you’re filing Form 7208.” “File Form 7208 annually to report and pay the excise tax.” |
| 7208-name | Name | The filer: a covered corporation, an applicable specified affiliate of an applicable foreign corporation, or an expatriated entity. |
| 7208-ein | Employer identification number (EIN) | “Enter your name and EIN.” |
Part I: total stock repurchases
Part I lists every repurchase of the year, one transaction or one plan per line, with the FMV in column (h). For this form, acquisitions by a specified affiliate count: “In completing Form 7208, acquisitions of stock by a specified affiliate or applicable specified affiliate are ‘repurchases.’” Line 4 then routes the filer: under the $1 million floor most filers stop after Part I and still attach the form.
| Line | Label | What goes there |
|---|---|---|
| 1a | Line 1, column (a) If repurchasing or acquiring entity is one other than the entity listed above, enter its name | “Use a separate line on the table for each transaction in which stock was repurchased.” Open-market buys under one plan go on one line. Column (a) names the specified affiliate or other entity that bought the stock, if it was not the filer. |
| 1b | Column (b) ... enter its EIN | That entity's EIN. An applicable specified affiliate or expatriated entity leaves it blank if the acquiring entity has no EIN. |
| 1c | Column (c) Type of transaction | “Enter the type of transaction in which the stock was repurchased.” The codes: OMR (open market), Tender Offer, ASR (accelerated share repurchase), Reorganization, Split-Off, NLF (a covered non-stock instrument) or Other. |
| 1d | Column (d) Stock symbol | “Enter the stock symbol (or ISIN/CUSIP) of the stock repurchased.” |
| 1e | Column (e) Class of stock | The class the repurchased stock belongs to. Several classes in one transaction take separate lines. |
| 1f | Column (f) Trading exchange | The established securities market, if any, where the stock trades. |
| 1g | Column (g) Number of shares | The total shares repurchased in the transaction. |
| 1h | Column (h) Total fair market value (FMV) of repurchased shares | “Enter the total FMV of the shares repurchased in the transaction.” The regulations (26 CFR 58.4501-2(h))26 CFR 58.4501-2Code of Federal Regulations, eCFR govern FMV. |
| 2 | Total from attachment, if necessary | The FMV total from continuation sheets for line 1. |
| 3 | Add amounts in column (h) and enter here. If filer is an applicable specified affiliate, see instructions | The tax year's repurchases. The statute's floor: no tax “in any case in which the total value of the stock repurchased during the taxable year does not exceed $1,000,000” (IRC 4501(e)(3))IRC 4501Internal Revenue Code, Cornell LII. |
| 4 | Were any of the repurchases shown on line 1 or line 2 with respect to stock of an applicable foreign corporation or a covered surrogate foreign corporation? Yes / No | Yes or No. Then the form's routing: “All filers reporting more than $1 million on line 3 must go to Part II.” A filer that is not an applicable specified affiliate and reports $1 million or less stops and attaches the form to Form 720. Applicable specified affiliates test the $1 million across all of them. |
Part II: exceptions
Part II takes out the statutory exceptions that the form carries as dollar amounts. The regulations (26 CFR 58.4501-3 and 58.4501-7(l))26 CFR 58.4501-3Code of Federal Regulations, eCFRTreas. Reg. 58.4501-7Treasury regulations, eCFR set the detail.
| Line | Label | What goes there |
|---|---|---|
| 5a | Stock repurchases as part of a reorganization in which no gain or loss is recognized | The form's label follows IRC 4501(e)(1)IRC 4501Internal Revenue Code, Cornell LII. The instructions describe the entry as “the FMV of any stock repurchased from a shareholder in a split-off in exchange for property permitted by section 355 to be received without the recognition of gain or loss”. |
| 5b | Stock repurchases treated as dividends | Only repurchases treated as a dividend under section 301(c)(1) or 356(a)(2), and only with sufficient evidence that the shareholder treats it so. “Don’t attach to the Form 7208 the evidence establishing that the shareholder treats the repurchase as a dividend.” |
| 5c | Reserved for future use | Blank. |
| 5d | Stock repurchases by a dealer in securities in the ordinary course of business | The dealer exception of IRC 4501(e)(4)IRC 4501Internal Revenue Code, Cornell LII. |
| 5e | Total exceptions. Add lines 5a through 5d | Carried to line 10. |
Part III: retirement plan contributions
Stock contributed to an employer-sponsored retirement plan reduces the base, class by class, at the average price of the repurchased class. The plan must be a qualified plan maintained by the covered corporation or a specified affiliate, including an ESOP.
| Line | Label | What goes there |
|---|---|---|
| 6a | Line 6, column (a) Class of stock repurchased | Use the line 6 table to figure the FMV of stock contributed to an employer-sponsored retirement plan. Contributions count for the year “if contributed by the filing deadline for the Form 720 to which the Form 7208 must be attached”. |
| 6b | Column (b) Number of shares repurchased | The net shares of the class from lines 1 and 2, less those counted in Part II. |
| 6c | Column (c) Aggregate FMV | The net FMV of the class, less amounts counted in Part II. |
| 6d | Column (d) Average price per share (divide (c) by (b)) | Column (c) divided by column (b). |
| 6e | Column (e) Number of shares (Contributions, Repurchased Class) | Shares of the repurchased class contributed to the plan. |
| 6f | Column (f) Aggregate FMV of shares contributed (multiply (d) by (e)) | The average price times the shares contributed. |
| 6g | Column (g) Number of shares contributed (Different Class) | Shares of another class contributed. |
| 6h | Column (h) Aggregate FMV of shares contributed (Different Class) | The sum of their FMVs at the time contributed. |
| 6i | Column (i) Aggregate value of contributions | “Enter the sum of column (f) and column (h). This amount may not exceed the amount reported in column (c).” |
| 7 | Total from attachment, if necessary | Contributions from continuation sheets. |
| 8 | Add amounts in column (i) and enter here | Carried to line 10. |
Parts IV and V: issuances and the tax
Part IV is the netting rule: stock the company issued or provided in the year, including to employees and on option exercises, reduces the repurchases subject to tax. Part V nets everything and applies 1%.
| Line | Label | What goes there |
|---|---|---|
| 9a | Stock issued or provided to employees | The netting rule of IRC 4501(c)(3)IRC 4501Internal Revenue Code, Cornell LII: repurchases are “reduced by the fair market value of any stock issued by the covered corporation during the taxable year”. Include option exercises; leave out stock already on lines 6 and 7. |
| 9b | Stock issued or provided to employees of a specified affiliate | “Enter -0- on line 9b in the case of a Form 7208 filed by an applicable specified affiliate or an expatriated entity.” |
| 9c | Stock issued but not entered on line 9a or line 9b | For a covered corporation, other stock issued in the year (for example, in an offering or an acquisition). Applicable specified affiliates and expatriated entities enter zero. |
| 9d | Total issuances. Add lines 9a through 9c | Carried to line 10. |
| 10 | Stock repurchases subject to tax. Subtract lines 5e, 8, and 9d from line 3. If zero or less, enter -0- and see instructions. | “If the resulting amount is zero or less, enter -0- and attach the Form 7208 to Form 720.” |
| 11 | Excise tax on stock repurchases. Multiply line 10 by 1% (0.01). Enter here and on Form 720 on the line for IRS No. 150 | The tax: “There is hereby imposed on each covered corporation a tax equal to 1 percent of the fair market value of any stock of the corporation which is repurchased by such corporation during the taxable year.” Carried to IRS No. 150. |
A year worked out
A calendar-year covered corporation repurchased $50,000,000 of its stock in 2026 (line 3). $2,000,000 of that was a split-off repurchase that qualifies on line 5a (line 5e). It contributed stock of the repurchased class worth $3,000,000 to its 401(k) plan by April 30, 2027 (line 8), and issued $10,000,000 of stock to employees under its equity plan (line 9a, line 9d). Line 10 is $50,000,000 minus $2,000,000, $3,000,000 and $10,000,000: $35,000,000. Line 11 is 1% of that, $350,000, which goes on IRS No. 150 of the first-quarter 2027 Form 720 and is paid with it.
Instructions for Form 7208 (Rev. December 2025), When To File; IRS, When to File Form 7208 (Aug. 11, 2026). April 30, 2027 is a Friday.
When and how to file
The instructions' table matches the tax year's last month to the Form 720 that carries Form 7208:
| Tax year ends in | Attach Form 7208 to | Due by |
|---|---|---|
| Jan., Feb., Mar. | 2nd quarter Form 720 | July 31 (same year) |
| Apr., May, June | 3rd quarter Form 720 | October 31 (same year) |
| July, Aug., Sept. | 4th quarter Form 720 | January 31 (following year) |
| Oct., Nov., Dec. | 1st quarter Form 720 | April 30 (following year) |
The IRS's August 2026 notice adds a warning on dates: “Caution: Form 7208 is an annual return. Form 720 is a quarterly return.” On the Form 720, enter the quarter ending date of the quarter you file with, not the tax year end. File where the Form 720 is filed (Ogden, UT, on paper, or e-file). “The Form 720 to which this form is attached must be signed under penalties of perjury.” Late filing and late payment draw the usual penalties, 5% and 1/2 of 1% a month up to 25% each, unless there is reasonable cause; see Form 720 penalties.
Amending. “To amend your previously filed Form 7208, you must file a corrected Form 7208 (enter ‘Amended’ at the top of it) and attach it to your Form 720-X, Amended Quarterly Federal Excise Tax Return, for the quarter to which your previously filed Form 7208 was attached.” See the Form 720-X page. A refund of the stock buyback tax for another reason can be claimed on Form 8849, Schedule 6, CRN 441.
Rules that trip filers up
- Filing with the wrong quarter. It is the first full quarter after the tax year ends, not the quarter in which the year ends.
- Not filing under $1 million. The tax is zero, but Part I is still completed and attached to Form 720.
- Counting plan contributions twice. Stock on lines 6 and 7 is left out of line 9a.
- Netting above the class total. Column (i) may not exceed column (c).
- Making deposits. IRS No. 150 is paid with the return, not deposited.
- Attaching the dividend evidence. Keep it; do not attach it.
How it connects
- The guide behind this form: the stock buyback excise tax guide.
- Where the total goes: Form 720 line by line (IRS No. 150), the Form 720 guide and due dates.
- Corrections and refunds: Form 720-X and Form 8849. Every federal excise tax: federal excise taxes.
Questions filers ask
When is Form 7208 due?
With the Form 720 for the first full quarter after your tax year ends. For a calendar-year corporation that is the first-quarter Form 720, due April 30 of the next year.
Do I file Form 7208 if repurchases were under $1 million?
Yes, Part I, attached to Form 720. If line 3 is $1 million or less and you are not an applicable specified affiliate, you stop after Part I and owe no tax.
Is the stock buyback excise tax deposited?
No. IRS No. 150 is a Form 720 Part II tax, paid with the return. The instructions call Form 7208 an annual return attached to the quarterly Form 720.
What reduces the stock buyback base on Form 7208?
The Part II exceptions (reorganization repurchases, repurchases treated as dividends, dealer repurchases), stock contributed to an employer-sponsored retirement plan (Part III), and stock issued or provided during the year, including to employees (Part IV).
How do I amend Form 7208?
File a corrected Form 7208 marked Amended and attach it to a Form 720-X for the quarter whose Form 720 carried the original Form 7208.