- Who files
- FAET sellers and tax-free buyers
- When
- Before the first tax-free sale
- Filed with
- TTB National Revenue Center
- Form revision
- 06/2009
- Pages
- 2, plus a privacy notice
At a glance
TTB F 5300.28 is the application for a tax-free registration under the firearms and ammunition excise tax (FAET). TTB puts it simply: “If you want to sell an article tax-free, you must have a tax-free registration number. To obtain a tax-free registration number, you must file an Application for Registration for Tax-Free Transactions (TTB F 5300.28).” The tax itself is “10% of the sale price of pistols and revolvers; 11% of the sale price of firearms other than pistols and revolvers, shells and cartridges.” (26 U.S.C. 4181)26 U.S.C. 4181United States Code, Cornell LII, and the firearms excise tax hub explains it.
- Who files. Manufacturers, producers and importers that sell tax-free, and purchasers (first and in some cases second) that buy tax-free for further manufacture, export or a nonprofit school; state and local governments may choose to.
- When. Before the first tax-free sale or purchase: 27 CFR 53.14027 CFR 53.140Code of Federal Regulations, eCFR requires the applicant to “file TTB Form 5300.28, in duplicate” prior to making one.
- Where. Both copies to TTB's National Revenue Center in Cincinnati (address below), or to TTB's Puerto Rico office for Puerto Rico and the Virgin Islands.
- Form revision. TTB F 5300.28 (06/2009), OMB No. 1513-0095; two pages of application and instructions plus a privacy notice. It is still the edition TTB links from its FAET pages as of November 2026.
Who must register
The regulation is the rule: “Except as provided in section 53.141, tax-free sales under section 4221 of the Code may be made only if the manufacturer, first purchaser, and second purchaser, as the case may be, have registered as required by this section.” The exceptions in 53.141 are state and local governments, foreign purchasers buying for export, and buyers of supplies for vessels and aircraft. TTB's reference guide: “State and local governments (or their political subdivisions) can elect, but are not required, to be registered.” and “Anyone who purchases firearms or ammunition as supplies for vessels or aircraft does not have to be registered.”
TTB FAET Reference Guide, section VII.D; 27 CFR 53.14027 CFR 53.140Code of Federal Regulations, eCFR and 53.141.
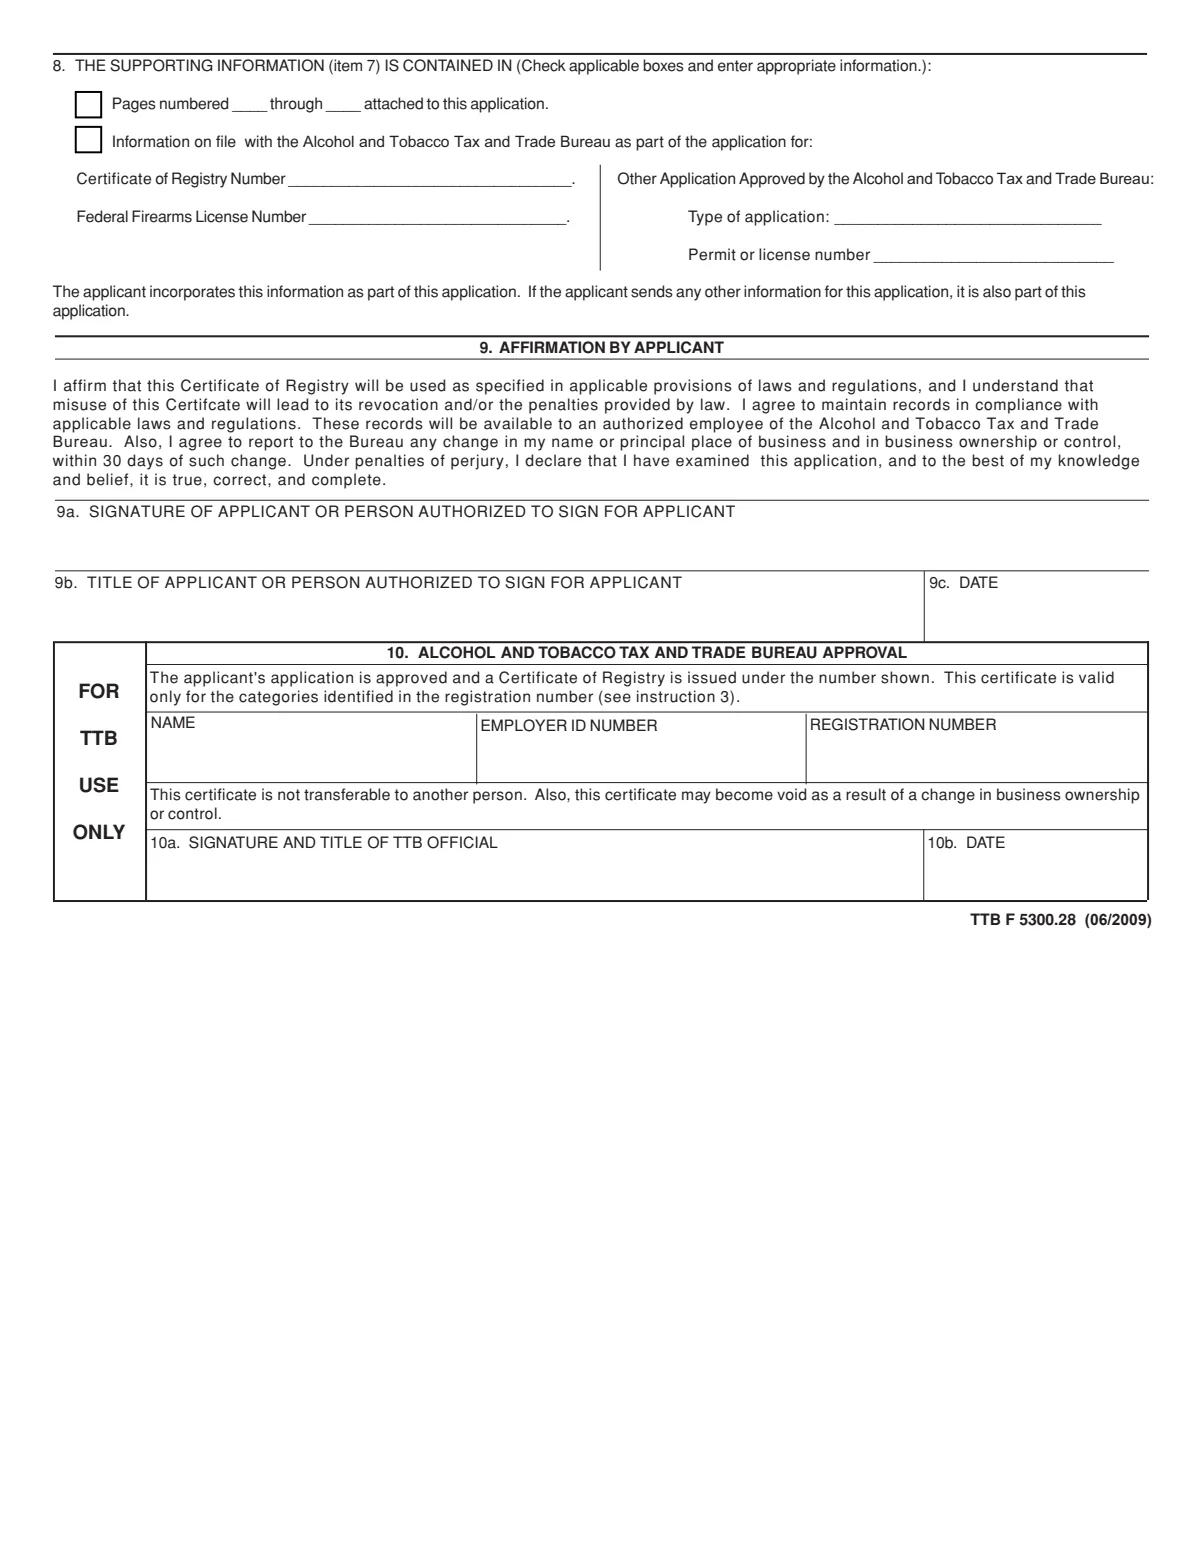
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
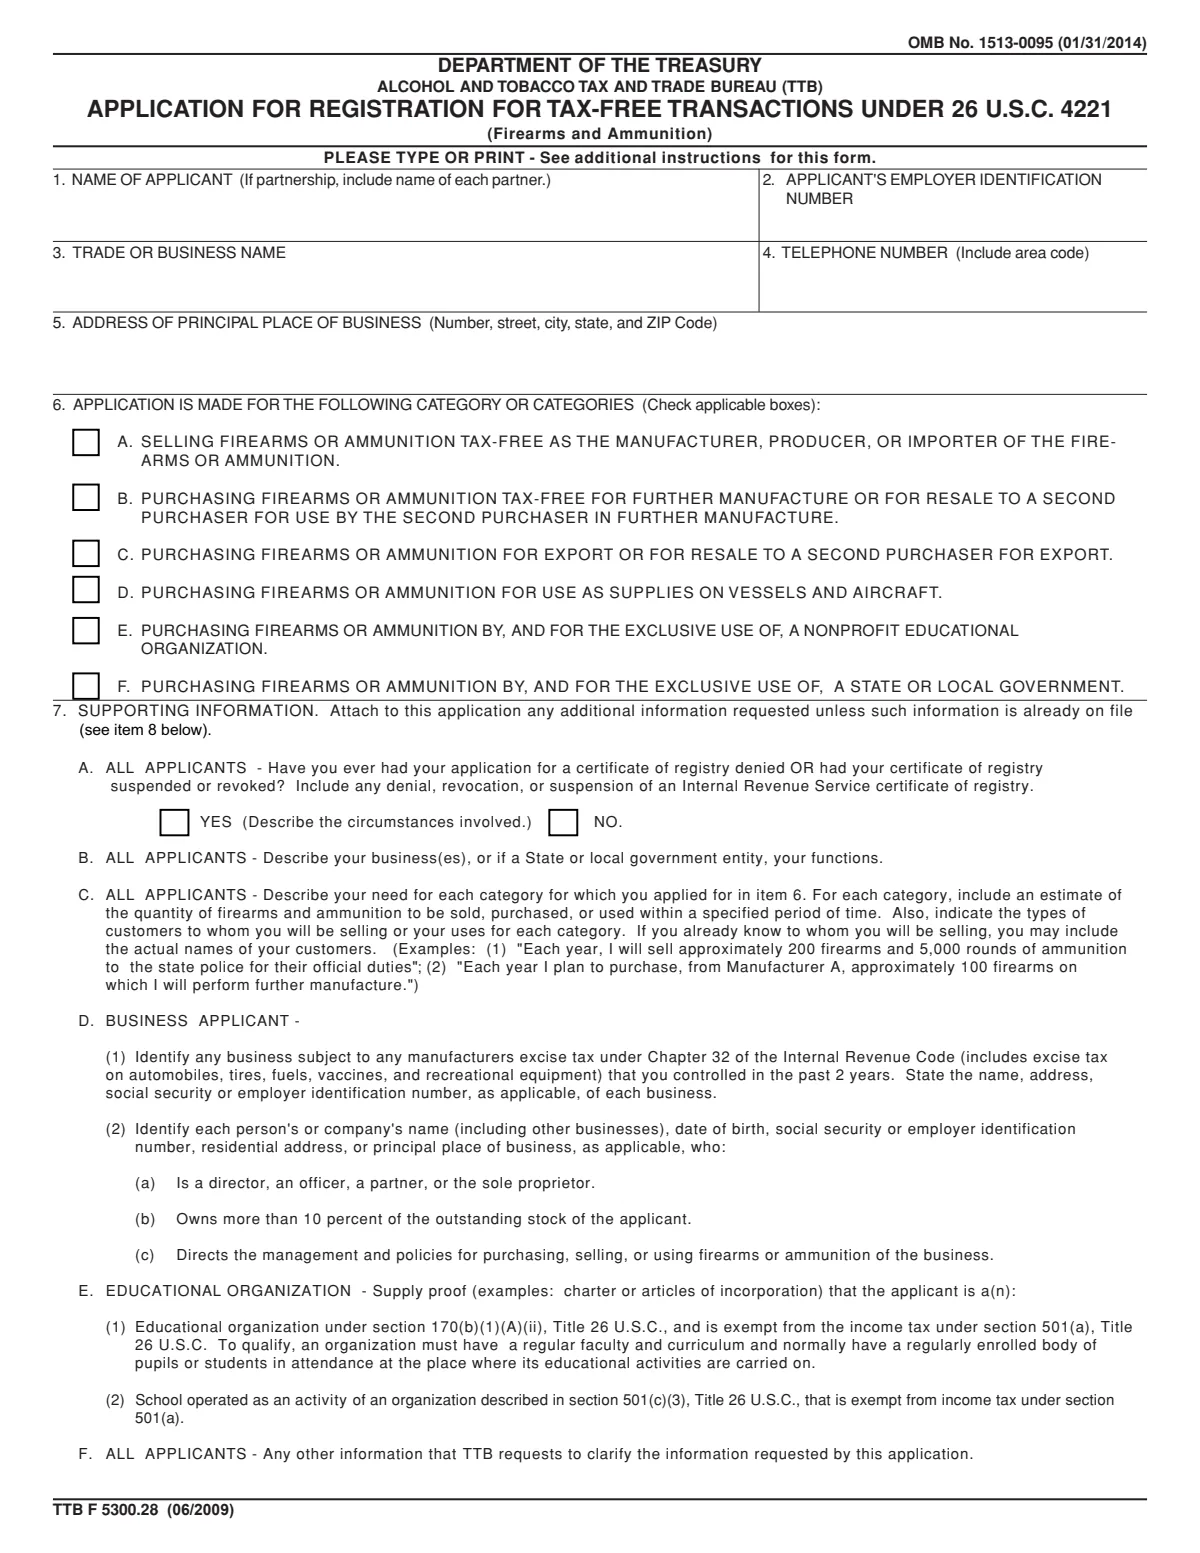
Item 6: the six categories
Item 6 is the heart of the application: check every category you need. The approved number shows them: “The letter(s) after the first six numbers in the registration number and before the dash represents the authorized category.” “Each letter corresponds to a category listed in item 6 on the form.” A buyer quoting its number to a manufacturer is therefore also telling it which tax-free purposes it is registered for.
| Category | Tax-free activity |
|---|---|
| A | Selling firearms or ammunition tax-free as the manufacturer, producer, or importer |
| B | Purchasing tax-free for further manufacture, or for resale to a second purchaser for use in further manufacture |
| C | Purchasing for export, or for resale to a second purchaser for export |
| D | Purchasing for use as supplies on vessels and aircraft |
| E | Purchasing by, and for the exclusive use of, a nonprofit educational organization |
| F | Purchasing by, and for the exclusive use of, a state or local government |
Items 1 to 10
Items 1 to 5 identify the applicant, item 6 picks the categories, item 7 is the supporting information (on separate sheets), item 8 says where it is, item 9 is the signed affirmation, and item 10 is TTB's approval. “Follow all the instructions on this form and complete this application in duplicate including additional information (see item 7 on the application).”
| Item | Label | What goes there |
|---|---|---|
| 1 | 1. NAME OF APPLICANT (If partnership, include name of each partner.) | The applicant's legal name. A partnership lists each partner. |
| 2 | 2. APPLICANT'S EMPLOYER IDENTIFICATION | The applicant's EIN. The approved certificate shows the EIN beside the registration number. |
| 3 | 3. TRADE OR BUSINESS NAME | Any trade name or DBA. |
| 4 | 4. TELEPHONE NUMBER (Include area code) | A number TTB can call about the application. |
| 5 | 5. ADDRESS OF PRINCIPAL PLACE OF BUSINESS (Number, street, city, state, and ZIP Code) | The principal place of business. A later change is reported by letter to TTB within 30 days, with the registration number. |
| 6A | A. SELLING FIREARMS OR AMMUNITION TAX-FREE AS THE MANUFACTURER, PRODUCER, OR IMPORTER OF THE FIRE- | For manufacturers, producers and importers that will sell without charging the 10% or 11% FAET. The seller's own registration is what lets it make tax-free sales under 26 U.S.C. 422126 U.S.C. 4221United States Code, Cornell LII. |
| 6B | B. PURCHASING FIREARMS OR AMMUNITION TAX-FREE FOR FURTHER MANUFACTURE OR FOR RESALE TO A SECOND | For a purchaser that will further manufacture the articles (or resell them to someone who will). Registered purchasers give the seller their registration number and the exempt purpose in writing. |
| 6C | C. PURCHASING FIREARMS OR AMMUNITION FOR EXPORT OR FOR RESALE TO A SECOND PURCHASER FOR EXPORT. | For a purchaser buying for export or for resale for export. The seller must receive proof of export within 6 months after the tax-free sale. Foreign purchasers need not register. |
| 6D | D. PURCHASING FIREARMS OR AMMUNITION FOR USE AS SUPPLIES ON VESSELS AND AIRCRAFT. | For supplies on vessels or aircraft. TTB's guide says such purchasers do not have to be registered, but the seller needs an exemption certificate (TTB F 5600.34). |
| 6E | E. PURCHASING FIREARMS OR AMMUNITION BY, AND FOR THE EXCLUSIVE USE OF, A NONPROFIT EDUCATIONAL | For a nonprofit educational organization; item 7E asks for proof of its status under section 170(b)(1)(A)(ii) or as a school run by a 501(c)(3) organization. |
| 6F | F. PURCHASING FIREARMS OR AMMUNITION BY, AND FOR THE EXCLUSIVE USE OF, A STATE OR LOCAL GOVERNMENT. | For a state or local government. Registration is optional; an unregistered government gives the seller an exemption certificate (TTB F 5600.35) or a purchase order instead. |
| 7 | 7. SUPPORTING INFORMATION. | Attach the answers to items 7A to 7F on separate pages, unless the information is already on file (item 8). |
| 7A | A. ALL APPLICANTS - Have you ever had your application for a certificate of registry denied OR had your certificate of registry | “Have you ever had your application for a certificate of registry denied OR had your certificate of registry suspended or revoked?” Include IRS certificates as well as TTB ones. |
| 7B | B. ALL APPLICANTS - Describe your business(es), or if a State or local government entity, your functions. | A plain description of the business, or a government's functions. |
| 7C | C. ALL APPLICANTS - Describe your need for each category for which you applied for in item 6. For each category, include an estimate of | For each category checked in item 6: why you need it, an estimate of the firearms and ammunition over a stated period, and your customers or uses. The form's example: about 200 firearms and 5,000 rounds a year to the state police. |
| 7D | D. BUSINESS APPLICANT - | (1) Any business subject to a chapter 32 manufacturers excise tax that you controlled in the past 2 years, with name, address and EIN or SSN. (2) Each director, officer, partner or sole proprietor, each owner of more than 10% of the stock, and each person directing the firearms purchasing, selling or use, with date of birth, number and address. |
| 7E | E. EDUCATIONAL ORGANIZATION - Supply proof (examples: charter or articles of incorporation) that the applicant is a(n): | Proof that the applicant is an educational organization exempt under section 501(a). “To qualify, an organization must have a regular faculty and curriculum” and a regularly enrolled student body. |
| 7F | F. ALL APPLICANTS - Any other information that TTB requests to clarify the information requested by this application. | Any other information TTB asks for. “An incomplete application causes delay, and you may not receive a Certificate of Registry.” |
| 8 | 8. THE SUPPORTING INFORMATION (item 7) IS CONTAINED IN (Check applicable boxes and enter appropriate information.): | Check whether the item 7 answers are on attached numbered pages, or already on file with TTB under a certificate of registry, a Federal firearms license or another approved application (give its number and type). |
| 9 | 9. AFFIRMATION BY APPLICANT | The applicant affirms the certificate will be used as the law allows and that misuse leads to revocation or penalties. “I agree to report to the Bureau any change in my name or principal place of business and in business ownership or control, within 30 days of such change.” |
| 9a | 9a. SIGNATURE OF APPLICANT OR PERSON AUTHORIZED TO SIGN FOR APPLICANT | Signed under penalties of perjury by the applicant or an authorized signer. |
| 9b | 9b. TITLE OF APPLICANT OR PERSON AUTHORIZED TO SIGN FOR APPLICANT | The signer's title. |
| 9c | 9c. DATE | The date signed. |
| 10 | 10. ALCOHOL AND TOBACCO TAX AND TRADE BUREAU APPROVAL | Leave it blank. “Your tax-free registration number is reflected in Item 10 and is effective on the date that your application is signed by the Director of the National Revenue Center (NRC) in Item 10(b).” “This certificate is not transferable to another person.” |
After approval
TTB returns one approved copy, which is the certificate of registry. Changes are made through TTB, in writing:
- Adding or dropping a category. Send the current certificate and a new, complete application. “Changes are effective when TTB approves the application.”
- New name, address, ownership or control. A letter to TTB within 30 days with the registration number; a change in ownership or control can void the certificate.
- Cancelling. Send the certificate with a written request.
- Denial and revocation. “Applications for tax-free registration can be denied. Approved tax-free registrations can be revoked or suspended.” (26 U.S.C. 4222(c))26 U.S.C. 4222United States Code, Cornell LII.
The form's instructions send applications to “National Revenue Center 550 Main St, Ste 8002 Cincinnati, OH 45202-5215”. That address dates from the 2009 edition; the National Revenue Center's own page now gives “Suite 8970”, Cincinnati, OH 45202-3222, the same address as the newer TTB F 5620.8. Use the current NRC address, or call the NRC at the number on its page before mailing.
Making tax-free sales
A registration does not make every sale tax-free; each sale needs its evidence. A registered buyer gives the seller its purpose and number in writing: under 27 CFR 53.131(c)27 CFR 53.131Code of Federal Regulations, eCFR, every registered purchaser “shall furnish to the seller, as evidence in support of each tax-free sale made by the seller to such purchaser, the exempt purpose for which the article or articles are being purchased and the registration number of the purchaser.” Unregistered buyers in the exempt groups give exemption certificates (TTB F 5600.34 for vessel and aircraft supplies, 5600.35 for state and local governments) or a purchase order. For a sale for further manufacture and export, the seller needs proof of export: “The manufacturer, importer or producer must receive this proof within 6 months after the article is sold tax-free.” Tax-free sales are then reported on the quarterly TTB F 5300.26.
Rules that trip filers up
- Selling before approval. The number is effective when the NRC Director signs item 10(b); a sale before that is taxable.
- Selling in a category you do not hold. The letters in the number limit the certificate to those categories.
- Thin item 7C answers. TTB asks for estimated quantities and customers per category; a vague answer delays approval.
- Missing the 30-day change letter. Name, address, ownership and control changes go to TTB within 30 days.
- Transferring the certificate. It belongs to the applicant and is not transferable with a business sale.
How it connects
- The tax: the firearms and ammunition excise tax hub, including exemptions and tax-free sales.
- The return where tax-free sales are reported: TTB F 5300.26 line by line.
- When tax was paid on a sale that should have been tax-free: TTB F 5620.8 and TTB claims.
- All TTB taxes: the TTB hub.
Questions filers ask
Do I need TTB F 5300.28 to sell firearms to a police department tax-free?
The seller needs its own registration (category A). The police department, as a state or local government, may register but does not have to; if it is not registered, the seller gets an exemption certificate (TTB F 5600.35) or a purchase order from it.
How do I read the registration number?
The letters after the first six numbers and before the dash are the categories from item 6 that TTB approved.
When does the registration take effect?
On the date the Director of the National Revenue Center signs item 10(b) of the approved application.
Where do I send TTB F 5300.28?
Both copies go to TTB's National Revenue Center in Cincinnati (Puerto Rico and Virgin Islands applicants use the San Juan office). The 2009 form prints Ste 8002; the NRC's current page gives Suite 8970, Cincinnati, OH 45202-3222.
What if my business changes ownership?
Send TTB a letter within 30 days with the registration number and the details. A change in ownership or control can void the certificate, so a new application may be needed.