- Who files
- Car manufacturers and importers
- Filed with
- Form 720 (IRS No. 40)
- Tax per car
- $1,000 to $7,700
- Form revision
- Rev. October 2023
- Pages
- 1, plus instructions
At a glance
Form 6197 figures the gas guzzler tax. “Use Form 6197 to figure the gas guzzler tax.” The tax is “imposed on the sale, use, or lease by the manufacturer or importer of an automobile of a model type that does not meet certain standards for fuel economy”, and the form is one page: Part I counts the cars by fuel economy range and multiplies by the tax for that range, and Part II lists the model types.
- Who files. Manufacturers and importers, including a business that lengthens cars (“The lengthening of existing automobiles is considered manufacture.”), and an individual who imports a gas guzzler for personal use.
- When. “The tax liability is figured each quarter and reported on Form 720.” With the quarterly Form 720: April 30, July 31, October 31 and January 31.
- How. Attached to Form 720; the total goes on IRS No. 40.
- Form revision. Form 6197 (Rev. October 2023). The IRS's About Form 6197 page lists “None at this time” under recent developments. The instructions are on page 2 of the form.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
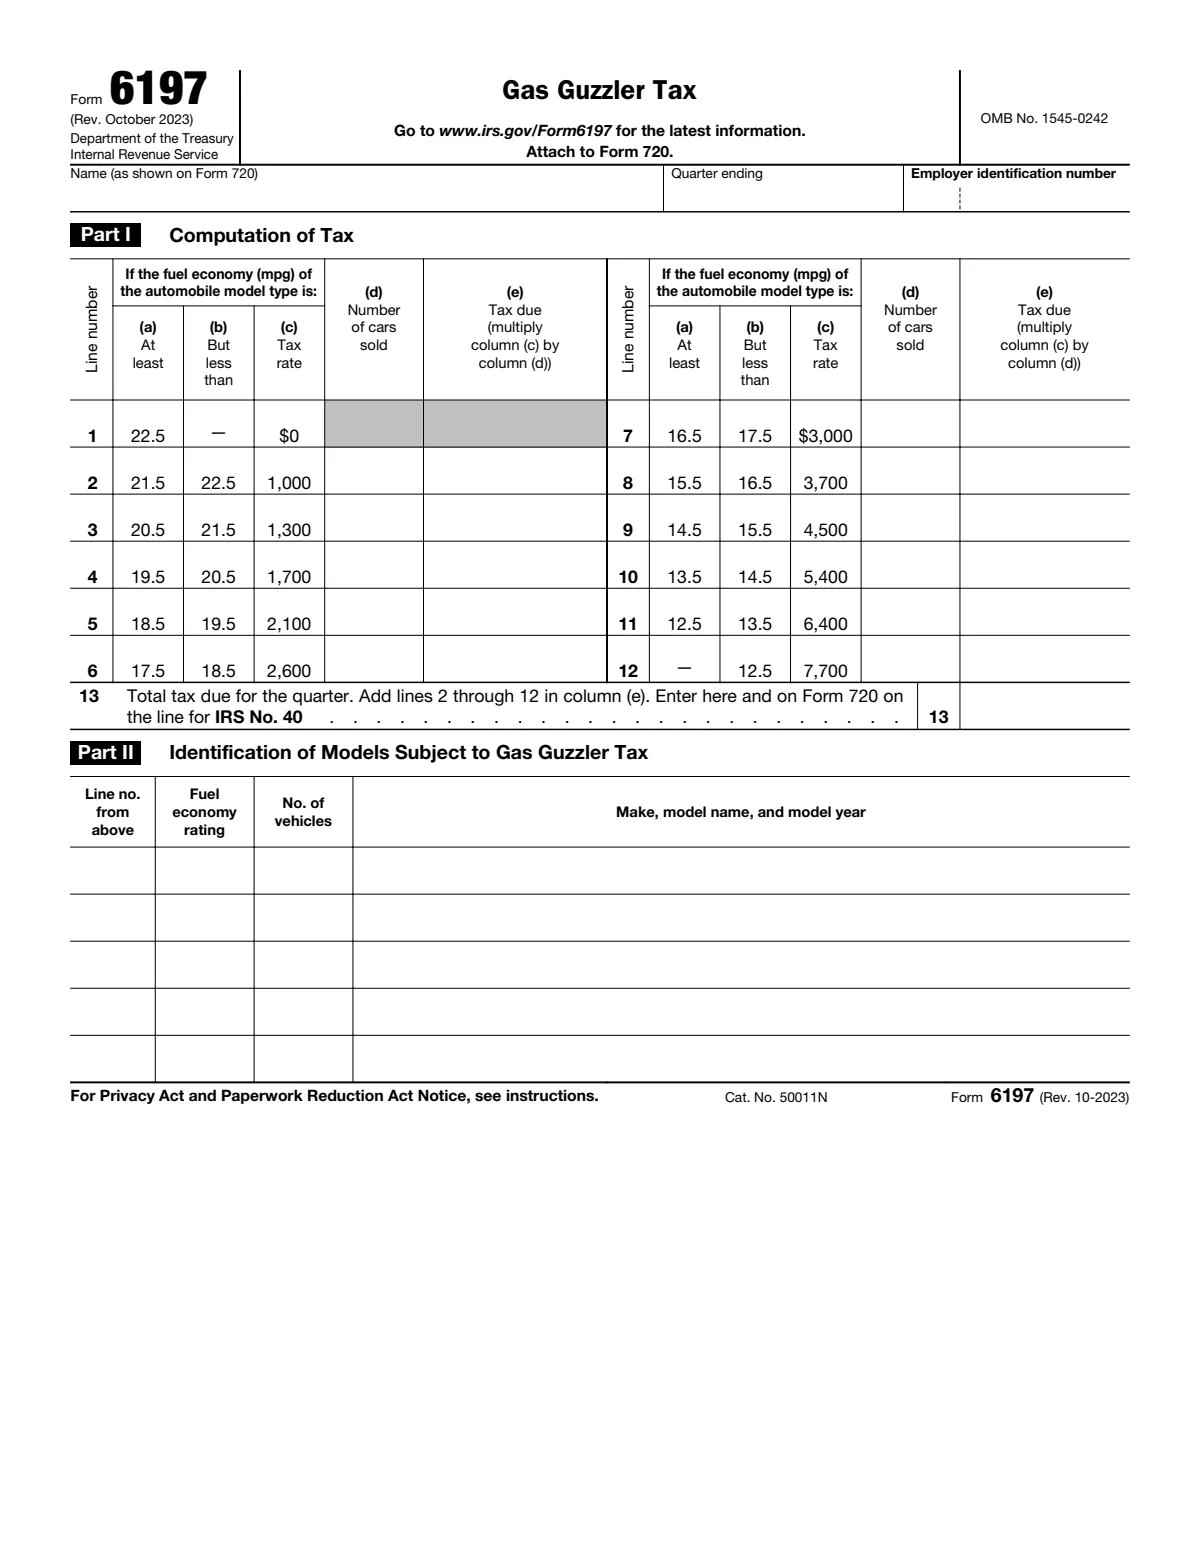
Name, quarter and EIN
| Line | Label | What goes there |
|---|---|---|
| 6197-name | Name (as shown on Form 720) | Form 6197 is attached to Form 720, so it carries the same name, quarter and EIN. |
| 6197-quarter | Quarter ending | The calendar quarter in which you sold, first used or first leased the cars. |
| 6197-ein | Employer identification number | The manufacturer's or importer's EIN. For a one-time filing, an individual without an EIN enters an SSN or ITIN on Form 720 and Form 720-V; Form 6197's box asks for the same number. |
Part I: computation of tax
Part I prints the 12 fuel economy ranges and the tax per car for each. The ranges and amounts come from the Code, “on the sale by the manufacturer of each automobile” (IRC 4064(a)), and do not change with inflation. Each row below is read from the form and checked against the statute's table when the page is built; all 12 agree, so the form can be used as printed. A range includes its lower number: a model type rated exactly 21.5 mpg is on line 2, and one rated 21.4 on line 3. “If you sold two or more models that fall within one category, enter the total number of cars for all models in that category”.
| Line | Label | What goes there |
|---|---|---|
| 1 | Line 1: (a) at least 22.5, (b) but less than (none), (c) tax rate $0 | A model type rated at 22.5 mpg or more owes no tax. The line carries no entry; the instructions say to complete lines 2 through 13. |
| 2 | Line 2: (a) at least 21.5, (b) but less than 22.5, (c) tax rate $1,000 | Cars of model types rated at least 21.5 but less than 22.5 mpg, in column (d); column (e) is $1,000 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. “Each line indicates a rating category based on the fuel economy (mpg) of the model type.” |
| 3 | Line 3: (a) at least 20.5, (b) but less than 21.5, (c) tax rate $1,300 | Cars of model types rated at least 20.5 but less than 21.5 mpg, in column (d); column (e) is $1,300 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. |
| 4 | Line 4: (a) at least 19.5, (b) but less than 20.5, (c) tax rate $1,700 | Cars of model types rated at least 19.5 but less than 20.5 mpg, in column (d); column (e) is $1,700 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. The form's own example falls here: “Enter $23,800 ($1,700 × 14) in column (e), line 4.” |
| 5 | Line 5: (a) at least 18.5, (b) but less than 19.5, (c) tax rate $2,100 | Cars of model types rated at least 18.5 but less than 19.5 mpg, in column (d); column (e) is $2,100 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. |
| 6 | Line 6: (a) at least 17.5, (b) but less than 18.5, (c) tax rate $2,600 | Cars of model types rated at least 17.5 but less than 18.5 mpg, in column (d); column (e) is $2,600 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. |
| 7 | Line 7: (a) at least 16.5, (b) but less than 17.5, (c) tax rate $3,000 | Cars of model types rated at least 16.5 but less than 17.5 mpg, in column (d); column (e) is $3,000 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. |
| 8 | Line 8: (a) at least 15.5, (b) but less than 16.5, (c) tax rate $3,700 | Cars of model types rated at least 15.5 but less than 16.5 mpg, in column (d); column (e) is $3,700 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. |
| 9 | Line 9: (a) at least 14.5, (b) but less than 15.5, (c) tax rate $4,500 | Cars of model types rated at least 14.5 but less than 15.5 mpg, in column (d); column (e) is $4,500 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. The one-time filing example falls here: a car rated 15 mpg owes “$4,500 (Form 6197, line 9)”. |
| 10 | Line 10: (a) at least 13.5, (b) but less than 14.5, (c) tax rate $5,400 | Cars of model types rated at least 13.5 but less than 14.5 mpg, in column (d); column (e) is $5,400 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. |
| 11 | Line 11: (a) at least 12.5, (b) but less than 13.5, (c) tax rate $6,400 | Cars of model types rated at least 12.5 but less than 13.5 mpg, in column (d); column (e) is $6,400 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. |
| 12 | Line 12: (a) at least (none), (b) but less than 12.5, (c) tax rate $7,700 | Cars of model types rated less than 12.5 mpg, in column (d); column (e) is $7,700 times that number. The range and amount match IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII. |
| 13 | Total tax due for the quarter. Add lines 2 through 12 in column (e). Enter here and on Form 720 on the line for IRS No. 40 | The quarter's total, carried to IRS No. 40 on Form 720. “Attach Form 6197 to Form 720.” |
What counts as a sale: “Sale includes the manufacturer’s first use of an automobile or first lease of an automobile.” The vehicle must be an automobile: “Automobile (including limousines) means any four-wheeled vehicle rated at 6,000 pounds or less unloaded gross weight that is propelled by an engine powered by gasoline or diesel fuel and is intended for use mainly on public streets, roads, and highways.” Vehicles run only on rails, emergency vehicles sold for and used as ambulances, police or firefighting vehicles, and nonpassenger automobiles are not automobiles for this tax.
Two quarters worked out
The form's example. In the second quarter a manufacturer sold 6 cars of a model rated 20 mpg and 8 of a model rated 19.7 mpg. Both fall on line 4 (19.5 to 20.5), so it enters 14 in column (d) and $23,800 in column (e), then $23,800 on line 13 and on IRS No. 40 of the second-quarter Form 720. Part II gets two entries, one per model.
A second example, computed from the statute table. An importer brings in and sells 3 cars of a model rated 16.0 mpg and 2 of a model rated 13.2 mpg in one quarter. The 16.0 mpg model is on line 8 (at least 15.5 but less than 16.5 mpg), at $3,700 a car: $11,100. The 13.2 mpg model is on line 11, at $6,400: $12,800. Line 13 is $23,900, which goes on IRS No. 40, and Part II lists both models with their lines, ratings and counts.
Part II: models subject to the tax
Part II is the check on Part I: one entry per model type sold, used or leased in the quarter, with its Part I line, fuel economy rating, number of vehicles, and make, model name and model year. “Model type means a particular class of automobile as determined by EPA regulations.”
| Line | Label | What goes there |
|---|---|---|
| II-line | Line no. from above | “Complete Part II by entering the information for each model type sold during a quarter.” Enter the Part I line (2 to 12) for each model type. |
| II-rating | Fuel economy rating | The EPA fuel economy of the model type, not a road test of the car. “Fuel economy means the average number of miles an automobile travels on a gallon of gasoline (or an equivalent amount of other fuel) as determined by the Environmental Protection Agency (EPA).” |
| II-vehicles | No. of vehicles | The cars of that model type, so the Part II counts add up to the Part I counts. |
| II-model | Make, model name, and model year | One line per model type. “If you need more space, attach a schedule in the same format as Part II.” |
The one-time filing
An individual who imports a gas guzzler outside a business does not become a quarterly filer. Form 6197 allows a one-time filing if “You don’t import gas guzzling automobiles in the course of your trade or business; and” “You aren’t required to file Form 720 reporting excise taxes for the calendar quarter, except for a one-time filing.”
Form 6197 (Rev. October 2023), One-Time Filing; Instructions for Form 720 (Rev. June 2026), IRS No. 40.
- File Form 720 and Form 6197 for the quarter in which you became liable for the tax.
- Pay the tax with the return. “No deposits are required.”
- If you are an individual with no EIN, enter your SSN or ITIN on Form 720 and Form 720-V in the space for the EIN.
- “Check the one-time filing box on Form 720 on the line for IRS No. 40.” See the IRS No. 40 line on Form 720.
Form 6197's example is an individual who imports a car rated 15 mpg, owes $4,500 (line 9), files Forms 720 and 6197 for that quarter and pays with the return. The gas guzzler guide covers imported cars without their own EPA rating.
Deposits and the IRS check
IRS No. 40 is in Part I of Form 720, so a manufacturer or business importer deposits it semimonthly through EFTPS with its other Part I taxes and records it on Schedule A, unless the quarter's Part I net liability is $2,500 or less. A one-time filing is the exception: the Form 720 instructions list “The gas guzzler tax is being paid on a one-time filing.” among the cases with no deposit, and Schedule A is not completed for it.
The IRS reads the attachment when it processes the return. Its code and edit manual says “If an entry of less than $1,000.00 is present on the IRS Number 40, it is in the wrong place.”, since line 2's $1,000 is the smallest tax on a car, and a missing Part I or Part II draws a letter asking for the form to be completed. A correction to an earlier quarter goes on Form 720-X with a corrected Form 6197.
Rules that trip filers up
- Splitting one range across lines. All model types in a range share one line; Part II separates them.
- Using a sticker or road test figure. Use the EPA fuel economy of the model type.
- Treating a lease as tax free. The first lease and the manufacturer's own first use are sales.
- Deposits on a one-time filing. None are required; pay with the return.
- Expecting exemptions. There are no exempt buyers. Emergency vehicles are outside the tax only when sold directly for that use with the registrations (Form 637, letters A and E); a paid tax on such a car is claimed on Form 720 Schedule C or Form 8849, Schedule 6, CRN 340.
How it connects
- The guide behind this form: the gas guzzler tax guide, Form 6197 section, with which vehicles count and emergency vehicles.
- Where the total goes: Form 720 line by line (IRS No. 40) and due dates and deposits.
- Registration for emergency vehicle sales: Form 637, letters A and E. Refunds: Form 8849, Schedule 6.
Questions filers ask
Who files Form 6197?
The manufacturer or importer of a car whose model type is rated under 22.5 mpg, every quarter it sells, first uses or first leases one, and an individual who imports such a car for personal use (with a one-time filing).
How much is the gas guzzler tax?
From $1,000 a car for model types rated at least 21.5 but less than 22.5 mpg up to $7,700 for those under 12.5 mpg, by IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII and Form 6197, Part I. Model types rated 22.5 mpg or more owe nothing.
Where does the Form 6197 total go?
Line 13 goes on IRS No. 40 in Part I of Form 720, and Form 6197 is attached to that Form 720.
Do I have to make deposits for the gas guzzler tax?
A manufacturer or business importer deposits it semimonthly like any Part I tax, unless Part I liability for the quarter is $2,500 or less. A one-time filer pays with the return, with no deposits.
Is the gas guzzler tax adjusted for inflation?
No. The ranges and amounts are fixed in IRC 4064(a)IRC 4064Internal Revenue Code, Cornell LII, and Form 6197 (Rev. October 2023) prints the same table.