- Who files
- Tobacco wholesalers and first receivers of e-liquid
- Due
- Postmarked by the 15th of the next month
- Filed with
- WV Tax Division, MyTaxes or mail
- Form revision
- rtL314 v.15
- Pages
- 3 (summary, Section 2, Schedule ECL)
At a glance
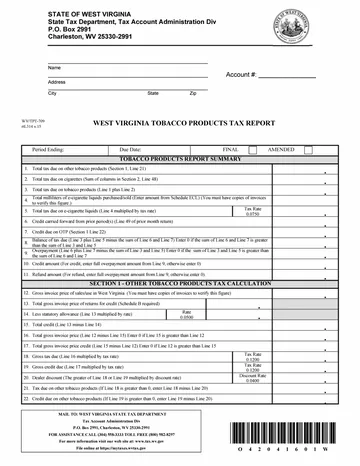
Form WV/TPT-709 is the West Virginia Tobacco Products Tax Report: one monthly return for the three taxes the Tax Division collects on tobacco. Cigarettes are taxed through stamps, and Section 2 reconciles the stamps a wholesaler bought and used against the packs it sold. Other tobacco products (cigars, pipe tobacco, snuff, chewing tobacco and the rest) are taxed on the gross invoice price in Section 1. E-cigarette liquid, taxed since July 1, 2016, is reported in milliliters on Schedule ECL and line 4.
- Who files. The wholesalers and others registered for the tobacco tax; for e-liquid, the first person in the state to receive it tax-not-paid. Out-of-state wholesalers that sell West Virginia stamped cigarettes start at line 44.
- When. Monthly, with a report even for a month with no activity, postmarked by the 15th of the next month. “Transactions for January 1st through 31st, reports are due on or before February 15th.”
- Where and how. Online in MyTaxes, or by mail to the West Virginia State Tax Department, Tax Account Administration Division, P.O. Box 2991, Charleston, WV 25330-2991. Paper filers with more than ten e-liquid invoices must file online.
- Form and schedules. WV/TPT-709 (rtL314 v.15) with its instructions, and the supporting schedules: Schedule 1, Schedule 2, Schedule 4, Schedule B, Schedule C and Schedule ECL.
WV/TPT-709 (rtL314 v.15) and its instructions; West Virginia Tax Division tobacco and e-cigarette liquid FAQs. Rates as of November 2026.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
Header
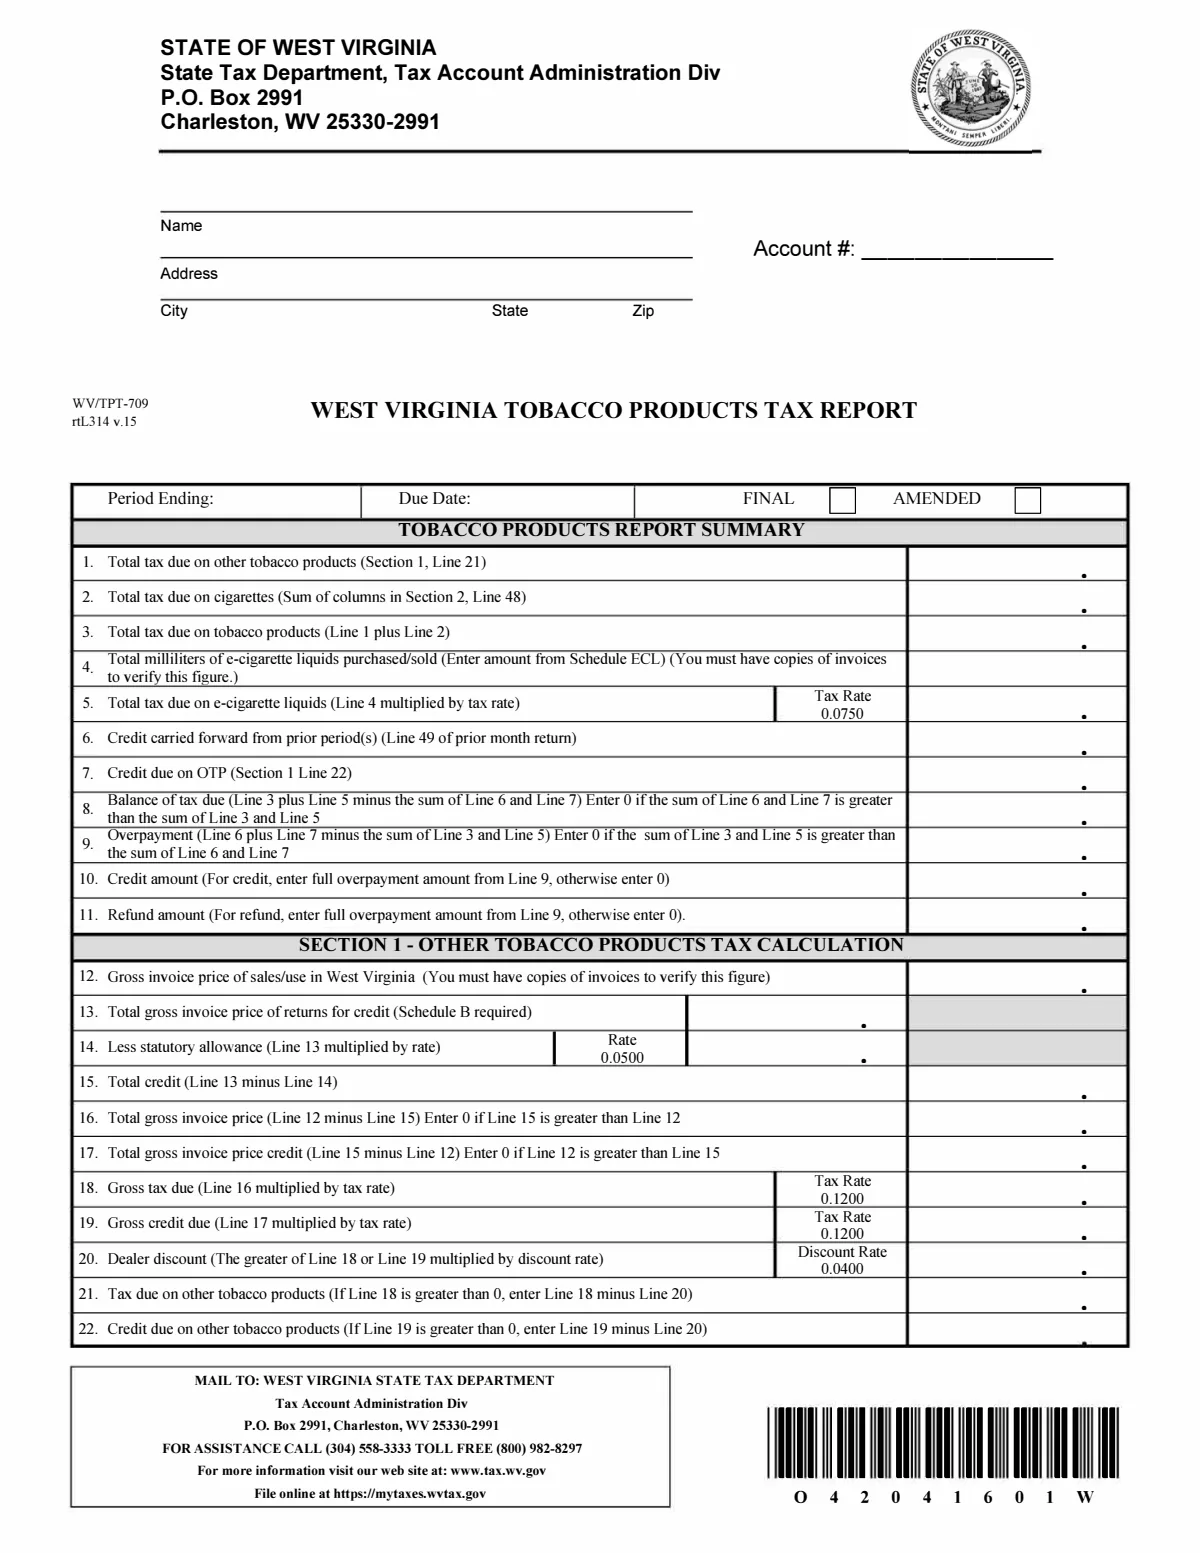
The top of page 1 identifies the filer, the account and the month. Pages 2 and 3 repeat the account number so the pages can be matched.
| Line | Label | What goes there |
|---|---|---|
| Name | Name, Address, City, State, Zip | The registered filer's name and address. The return goes to the West Virginia State Tax Department, Tax Account Administration Division, P.O. Box 2991, Charleston, WV 25330-2991, or is filed online. |
| Account | Account#: | Your Tax Division account number for the tobacco tax. |
| Period | Period Ending: | The month the report covers. “You must file this report monthly, even if no activity occurred during the month.” |
| Due | Due Date: | “Your report must be postmarked by the 15th of the month following the report month.” |
| Final-Amended | FINAL / AMENDED | Final: “Check only if this is your last report to be filed and the account should be closed.” Amended is only for a change to a report already filed. |
Summary: lines 1 to 11
The summary on page 1 brings the three taxes together. Fill it in last: line 1 comes from Section 1, line 2 from Section 2 and line 4 from Schedule ECL.
WV/TPT-709, summary lines 1 to 11, and its instructions.
| Line | Label | What goes there |
|---|---|---|
| 1 | Total tax due on other tobacco products | The other tobacco products (OTP) tax after the dealer discount, from Section 1. |
| 2 | Total tax due on cigarettes | The cigarette stamp shortfall, from line 48, both pack-size columns added. |
| 3 | Total tax due on tobacco products | Line 1 plus line 2. |
| 4 | Total milliliters of e-cigarette liquids | The milliliters of e-cigarette liquid from Schedule ECL. The tax falls on the first person to receive the liquid tax-not-paid in West Virginia: the wholesale dealer or other person “who is the first person to receive tax-not-paid e-cigarette liquid products in West Virginia”. |
| 5 | Total tax due on e-cigarette liquids | Line 4 times the printed rate, 0.0750. The Tax Division's FAQ: “The excise tax on e-cigarette liquids is at the rate of seven and one-half cents ($0.075) per milliliter of e-cigarette liquid or fraction thereof.” A part of a milliliter counts as a whole one, and the whole liquid is measured, nicotine or not. |
| 6 | Credit carried forward from prior period(s) | An overage from line 49 of an earlier return. The instructions cap it: it “Cannot exceed the amount of deficiency claimed Line 48 and Line 2 of the current return.” The form says "prior month return" for this line. |
| 7 | Credit due on OTP | The OTP credit from line 22, when returns for credit exceeded OTP sales. |
| 8 | Balance of tax due | Line 3 plus line 5, minus lines 6 and 7. Enter 0 if the credits are larger. This is what you pay. |
| 9 | Overpayment | Lines 6 and 7, minus lines 3 and 5. Enter 0 if the taxes are larger. |
| 10 | Credit amount | To take the overpayment as a credit, enter all of line 9 here. “Any credit or refund may be applied against any tax department liability.” |
| 11 | Refund amount | To ask for a refund, enter all of line 9 here. Lines 10 and 11 cannot both have amounts. |
Section 1: other tobacco products
Section 1 taxes other tobacco products on the wholesaler's gross invoice price. Returns for credit reduce the base after a 5 percent statutory allowance, and the 4 percent dealer discount comes off the tax or the credit. A month with more returns than sales ends in a credit on line 22 instead of a tax on line 21.
| Line | Label | What goes there |
|---|---|---|
| 12 | Gross invoice price of sales/use in West Virginia | The gross invoice price of OTP sold or used in West Virginia in the month, from Schedule C, which must be attached. OTP means cigars, pipe tobacco, snuff, chewing tobacco and the other tobacco products that are not cigarettes. |
| 13 | Total gross invoice price of returns for credit | The gross invoice price of OTP returned for credit, from Schedule B (attach it). |
| 14 | Less statutory allowance | Line 13 times the printed 0.0500: “Multiply line 13 by the statutory allowance of 5% (0.05).” |
| 15 | Total credit | Line 13 minus line 14. |
| 16 | Total gross invoice price | Line 12 minus line 15. Enter 0 if line 15 is larger. |
| 17 | Total gross invoice price credit | Line 15 minus line 12. Enter 0 if line 12 is larger. |
| 18 | Gross tax due | Line 16 times the printed 0.1200, that is 12 percent of the gross invoice price. The rate is printed on the form; the statute behind it was not read (the West Virginia Code site was down during research). |
| 19 | Gross credit due | Line 17 times 0.1200. |
| 20 | Dealer discount | The larger of line 18 or line 19, times 0.0400: the “statutory dealer discount 4% (0.04)”. |
| 21 | Tax due on other tobacco products | The form says Line 18 minus Line 20. The instructions word it the other way, “subtract line 18 from line 20”, which would give a negative tax. Follow the form: tax less the discount. |
| 22 | Credit due on other tobacco products | Line 19 minus line 20. “Note: You cannot have figures on both line 21 and line 22.” |
Section 2: cigarette stamps and packs
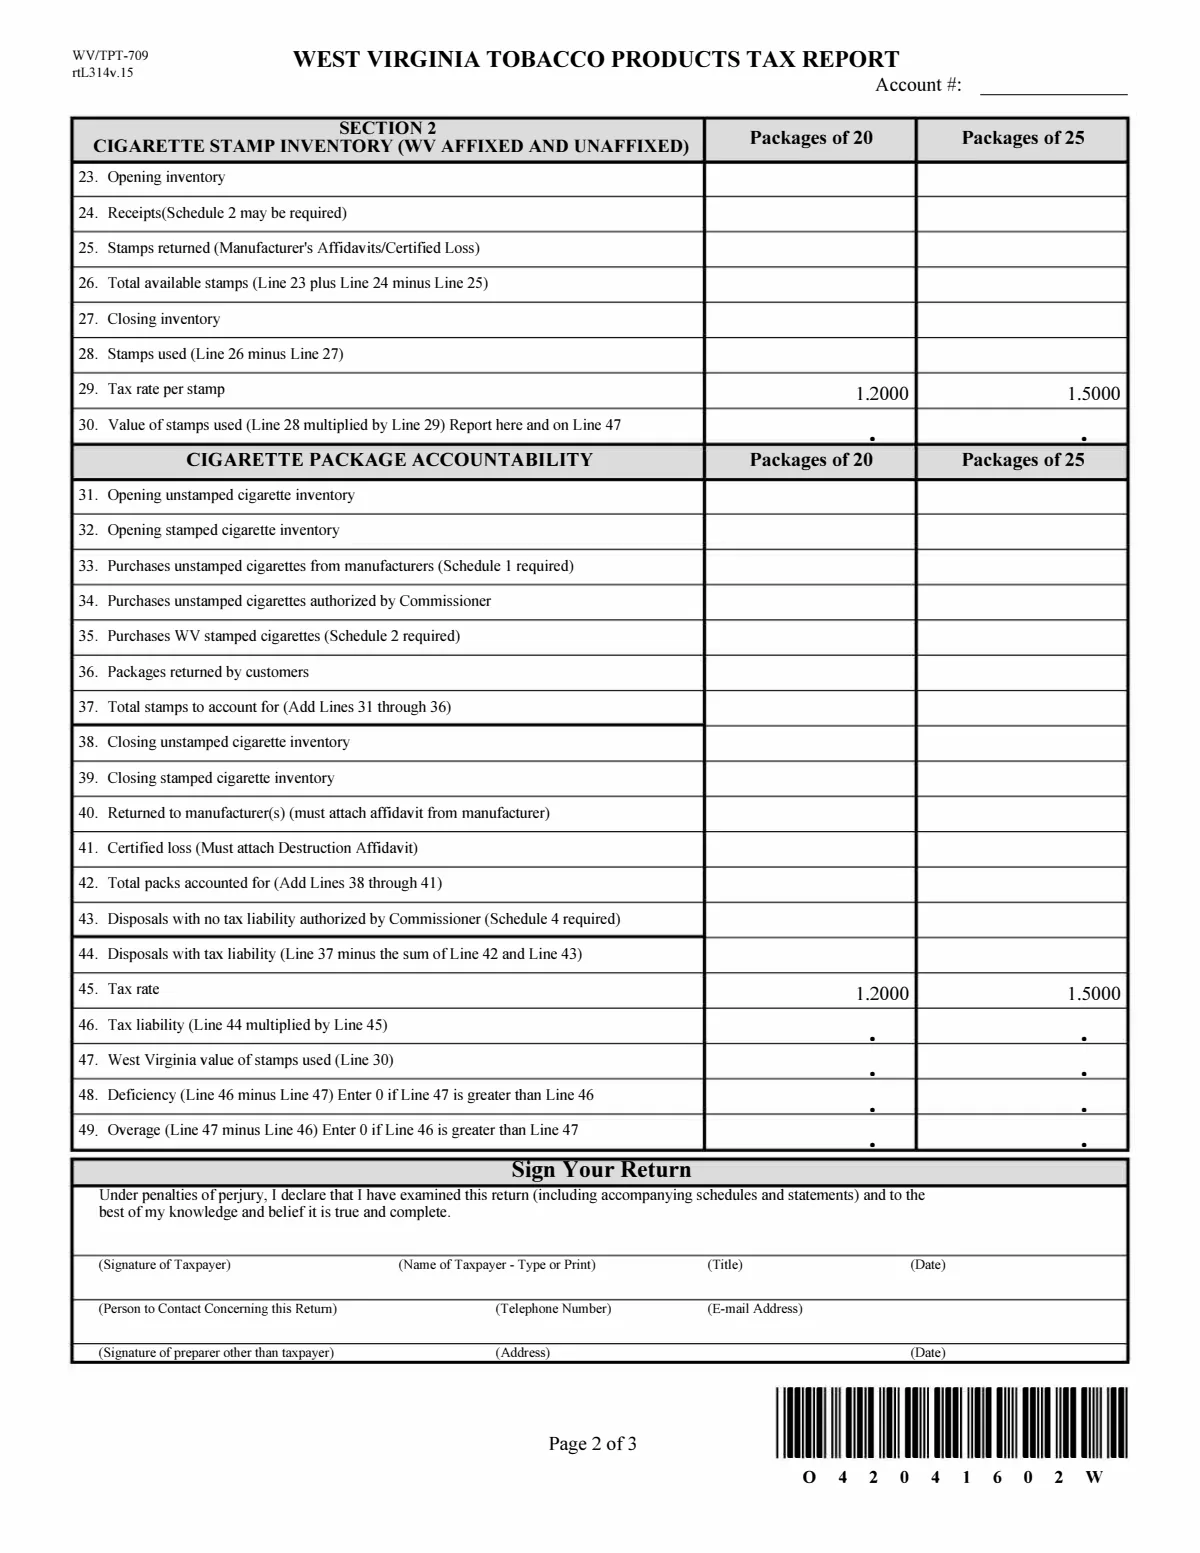
Section 2 has two parts, each with a column for packs of 20 and one for packs of 25. The stamp inventory (lines 23 to 30) works out the value of stamps used. The package accountability (lines 31 to 49) works out the tax on the packs that left your inventory taxable. The difference is either a deficiency you pay (line 48, carried to line 2) or an overage you can use later (line 49). Section 2 is for West Virginia stamps only.
| Line | Label | What goes there |
|---|---|---|
| Account-2 | Account#: (page 2) | The account number again. |
| 23 | Opening inventory | Stamps on hand on the first day, both the ones already on packs counted on line 32 and unaffixed stamps, in the column for packs of 20 or 25. “All inventories are required to be a physical count of what is on hand on the last day of each period.” |
| 24 | Receipts | Stamps received in the month: from the Commissioner, on packs returned by customers, and on stamped packs bought from another wholesaler (Schedule 2). |
| 25 | Stamps returned | Stamps returned to the Commissioner, stamps on packs returned to the manufacturer for credit, and West Virginia stamped packs lost in a certified loss. |
| 26 | Total available stamps | Line 23 plus line 24 minus line 25. |
| 27 | Closing inventory | Stamps on hand at the close of the month, affixed (line 39) and unaffixed. |
| 28 | Stamps used | Line 26 minus line 27: the stamps used in the month. |
| 29 | Tax rate per stamp | The value of each stamp: $1.20 on a pack of 20 and $1.50 on a pack of 25. The Tax Division's FAQ gives the same rates: “WV tax paid at the rates of $1.20 per package of 20 and $1.50 per package of 25”. |
| 30 | Value of stamps used | Line 28 times line 29, by pack size. Carry it to line 47. |
| 31 | Opening unstamped cigarette inventory | “Unstamped cigarettes include cigarettes with no stamps and cigarettes with other states stamps affixed.” Packs on hand on the first day. |
| 32 | Opening stamped cigarette inventory | Packs with West Virginia stamps on hand on the first day. |
| 33 | Purchases unstamped cigarettes from manufacturers | Unstamped packs bought from manufacturers in the month, from Schedule 1 (attach it). |
| 34 | Purchases unstamped cigarettes authorized by Commissioner | Unstamped packs bought from an agent the Commissioner authorized, from Schedule 1. |
| 35 | Purchases WV stamped cigarettes | West Virginia stamped packs bought from another wholesaler, from Schedule 2. |
| 36 | Packages returned by customers | Packs returned by customers and manufacturer's representatives, stamped (any state) or unstamped. |
| 37 | Total stamps to account for | Add lines 31 to 36. |
| 38 | Closing unstamped cigarette inventory | Unstamped packs on hand at the close of business on the last day. |
| 39 | Closing stamped cigarette inventory | West Virginia stamped packs on hand at the close of business on the last day. |
| 40 | Returned to manufacturer(s) | Packs returned to manufacturers for credit, stamped or not. Attach the manufacturer's affidavit. |
| 41 | Certified loss | Packs destroyed by fire, flood and similar events, claimed on a Destruction Affidavit. A loss of West Virginia stamped packs is also reported on line 25. |
| 42 | Total packs accounted for | Add lines 38 to 41. |
| 43 | Disposals with no tax liability | Sales of packs with other states' stamps, and unstamped packs sent to other wholesalers with the Commissioner's approval, from Schedule 4. |
| 44 | Disposals with tax liability | Line 37 minus lines 42 and 43. “Note: Out-of-state wholesalers begin with line 44.” They report their West Virginia stamped sales here. |
| 45 | Tax rate | The same per-pack rates as line 29. |
| 46 | Tax liability | Line 44 times line 45: the tax on the packs that left your hands taxable. |
| 47 | West Virginia value of stamps used | The value of stamps used, from line 30. |
| 48 | Deficiency | Line 46 minus line 47, when the packs you disposed of carry more tax than the stamps you used. Enter it on line 2. |
| 49 | Overage | Line 47 minus line 46, when you used more stamp value than the disposals required. It can be claimed on line 6 of a later return, up to that return's deficiency. |
| Sign | (Signature of Taxpayer) (Name of Taxpayer - Type or Print) (Title) (Date) | Signed under penalties of perjury. |
| Contact | (Person to Contact Concerning this Return) (Telephone Number) (E-mail Address) (Date) | The person the Tax Division should contact. |
| Preparer | (Signature of preparer other than taxpayer) (Address) | Completed only by a preparer who is not the taxpayer. |
Schedule ECL
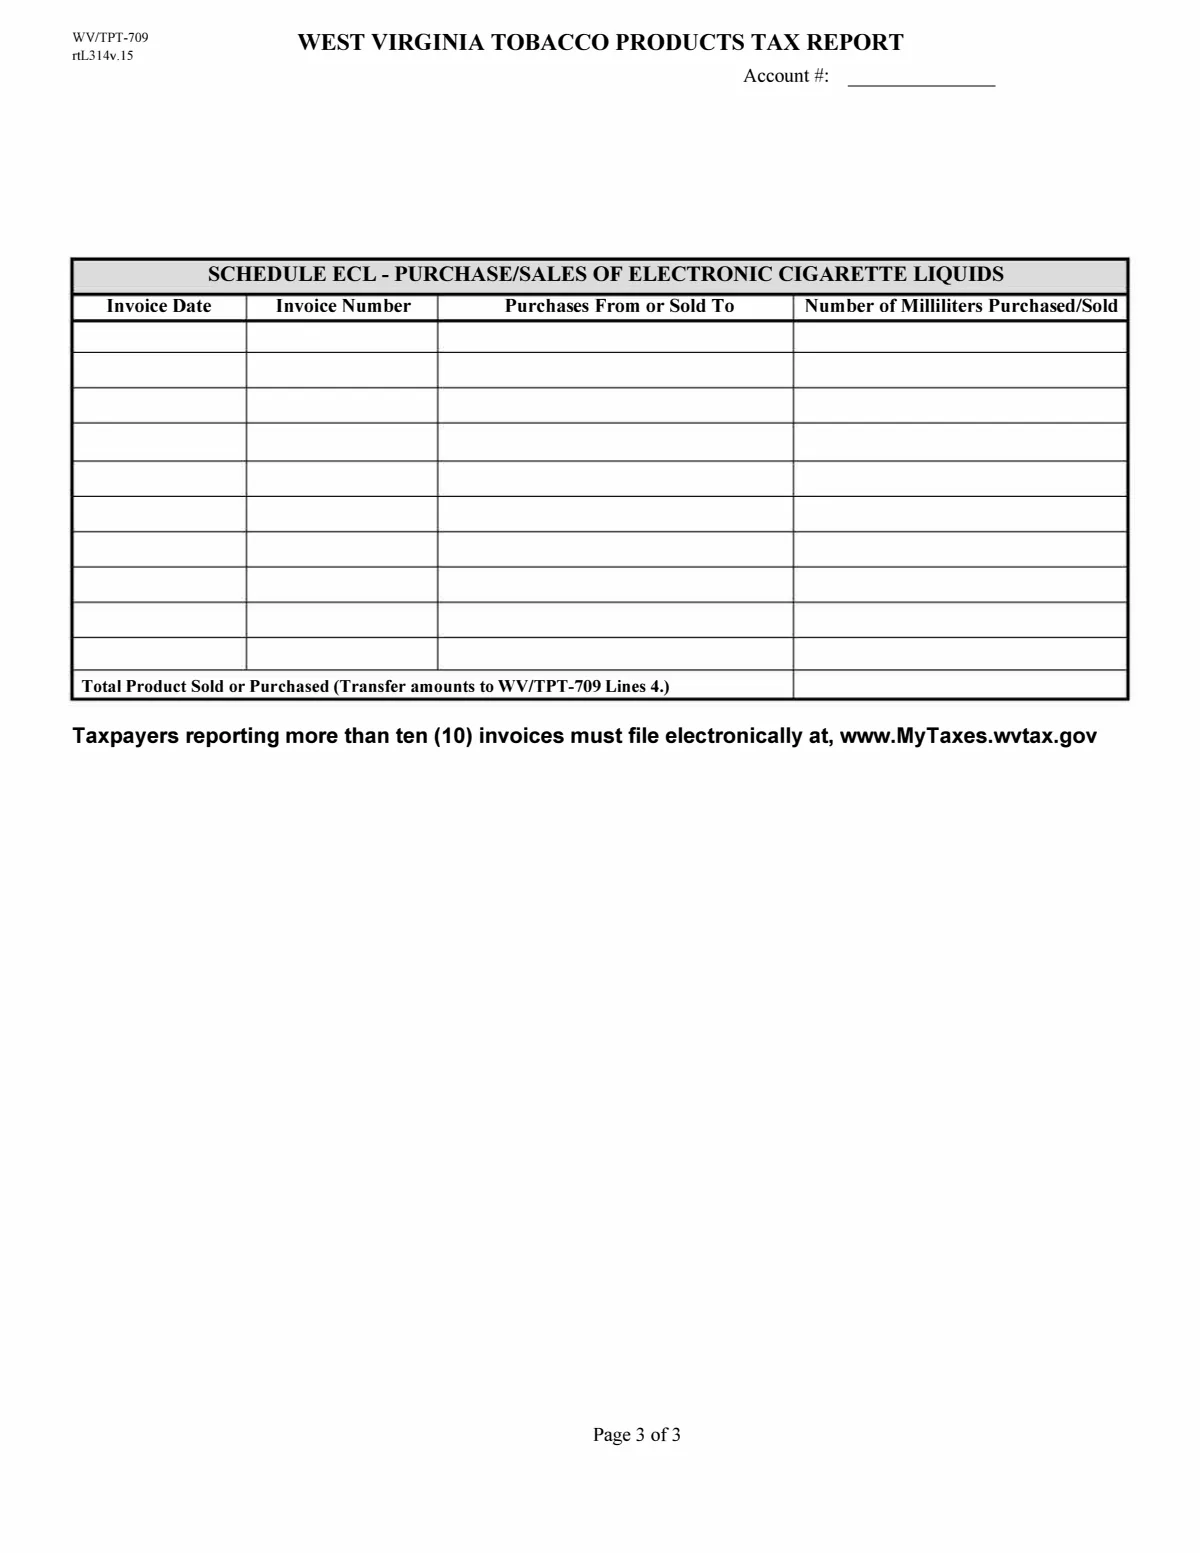
Schedule ECL lists each invoice of e-cigarette liquid bought or sold, with the milliliters. The Tax Division's FAQ explains the measure: “For example, a product that is 1.2 milliliters would be taxed as 2 milliliters with tax due being a total fifteen cents ($0.15).”
| Line | Label | What goes there |
|---|---|---|
| Account-3 | Account#: (page 3) | The account number again. |
| ECL-rows | SCHEDULE ECL - PURCHASE/SALES OF ELECTRONIC CIGARETTE LIQUIDS: Invoice Date, Invoice Number, Purchases From or Sold To, Number of Milliliters Purchased/Sold | One row per invoice. The paper schedule has ten rows: “Taxpayers reporting more than ten (1 0) invoices must file electronically at, www.MyTaxes.wvtax.gov” (the space in "1 0" is the form's). On MyTaxes, schedules go in through the import sheet or are entered one by one; attached schedules are not accepted on electronic returns. |
| ECL-total | Total Product Sold or Purchased (Transfer amounts to WV/TPT-709 Lines 4.) | The total milliliters; carry to line 4. |
Rules that trip filers up
- Skipping a month. The report is due every month, activity or not.
- Book inventories. Opening and closing inventories are physical counts on the last day of the period.
- Missing schedules. Lines 12, 13, 24, 33 to 35 and 43 each come from a schedule that must be attached on paper; on MyTaxes the schedules are imported or entered, not attached.
- Line 21 the wrong way round. Subtract the discount from the tax, as the form prints it.
- Both credit and refund. Lines 10 and 11 cannot both have amounts, and lines 21 and 22 cannot both have figures.
- Too many e-liquid invoices on paper. More than ten invoices means filing online.
When the cigarette rate rose on July 1, 2016, stamped packs and OTP already on hand owed a floor stock tax on a separate return, TPT-701, as the Tax Division's increase FAQ explains. The return for cigarette and tobacco floor stocks is not filed on TPT-709.
How it connects
- West Virginia's tobacco, vapor and other excise taxes, licenses and due dates: West Virginia excise tax, tobacco section.
- Other states: cigarette tax by state and vapor tax by state. More state tobacco returns: New Jersey TPT-10 and Wyoming Form 71.
- The federal tax on the same products, paid by manufacturers and importers to the TTB: tobacco excise tax and TTB F 5000.24.
Questions filers ask
When is the West Virginia TPT-709 due?
Monthly, postmarked by the 15th of the month after the report month. The January report is due by Feb. 15. File one even for a month with no activity.
What is West Virginia's tax on other tobacco products?
12 percent of the gross invoice price, as printed on line 18 of TPT-709, less a 4 percent dealer discount on line 20. Returns for credit reduce the base after a 5 percent statutory allowance.
How is e-cigarette liquid reported?
List each invoice on Schedule ECL with its milliliters, carry the total to line 4, and multiply by $0.075 on line 5. A fraction of a milliliter counts as a whole one. More than ten invoices means filing online in MyTaxes.
What happens to a stamp overage?
Line 49 shows it. You can claim it on line 6 of a later return, but not more than that return's cigarette deficiency.
Do out-of-state wholesalers fill in the whole Section 2?
No. The instructions say out-of-state wholesalers begin with line 44, where they report their West Virginia stamped sales.
Sources
- WV/TPT-709, West Virginia Tobacco Products Tax Report (rtL314 v.15), PDF
- WV/TPT-709 instructions, PDF
- West Virginia Tax Division, Tobacco Products (forms and schedules)
- West Virginia Tax Division, Cigarette and Other Tobacco Products Excise Tax Increase FAQ
- West Virginia Tax Division, E-cigarette Liquids Excise Tax FAQ