- Who files
- Businesses registered for the Tobacco and Vapor Products Tax
- Due
- 20th of the next month
- Filed with
- NJ Division of Taxation, online or mail
- Form revision
- rev 8/25
- Pages
- 1, plus 2 pages of instructions
At a glance
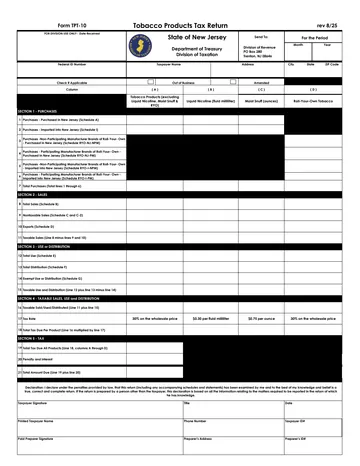
Form TPT-10 is New Jersey's monthly Tobacco Products Tax Return under the Tobacco and Vapor Products Tax. The tax “is imposed on the sale of tobacco and nicotine products, other than cigarettes, by a distributor or a wholesaler to a retail dealer or consumer”. “Cigarettes are exempt from this tax.” The return has four columns: (A) tobacco products other than liquid nicotine, moist snuff and roll-your-own; (B) liquid nicotine in fluid milliliters; (C) moist snuff in ounces; and (D) roll-your-own tobacco.
- Who files. Every business registered for the Tobacco and Vapor Products Tax, with the schedules that apply.
- When. The 20th day of the month after the report month. “If the due date falls on a weekend or holiday, the return is due the next business day.”
- Where and how. Through the Division's online filing and payment service, or on paper to the address printed on the form: Division of Revenue, PO Box 280, Trenton, NJ 08646.
- Form and schedules. Form TPT-10 (rev 8/25), one page with two pages of instructions. The schedules (A, B, C, C-2, D, E, F, G, I and the four RYO schedules) are on the Division's Tobacco and Vapor Products Tax forms page.
Form TPT-10 (rev 8/25), line 17; NJ Division of Taxation excise tax rates and tobacco pages, read Nov. 22, 2026.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
Header
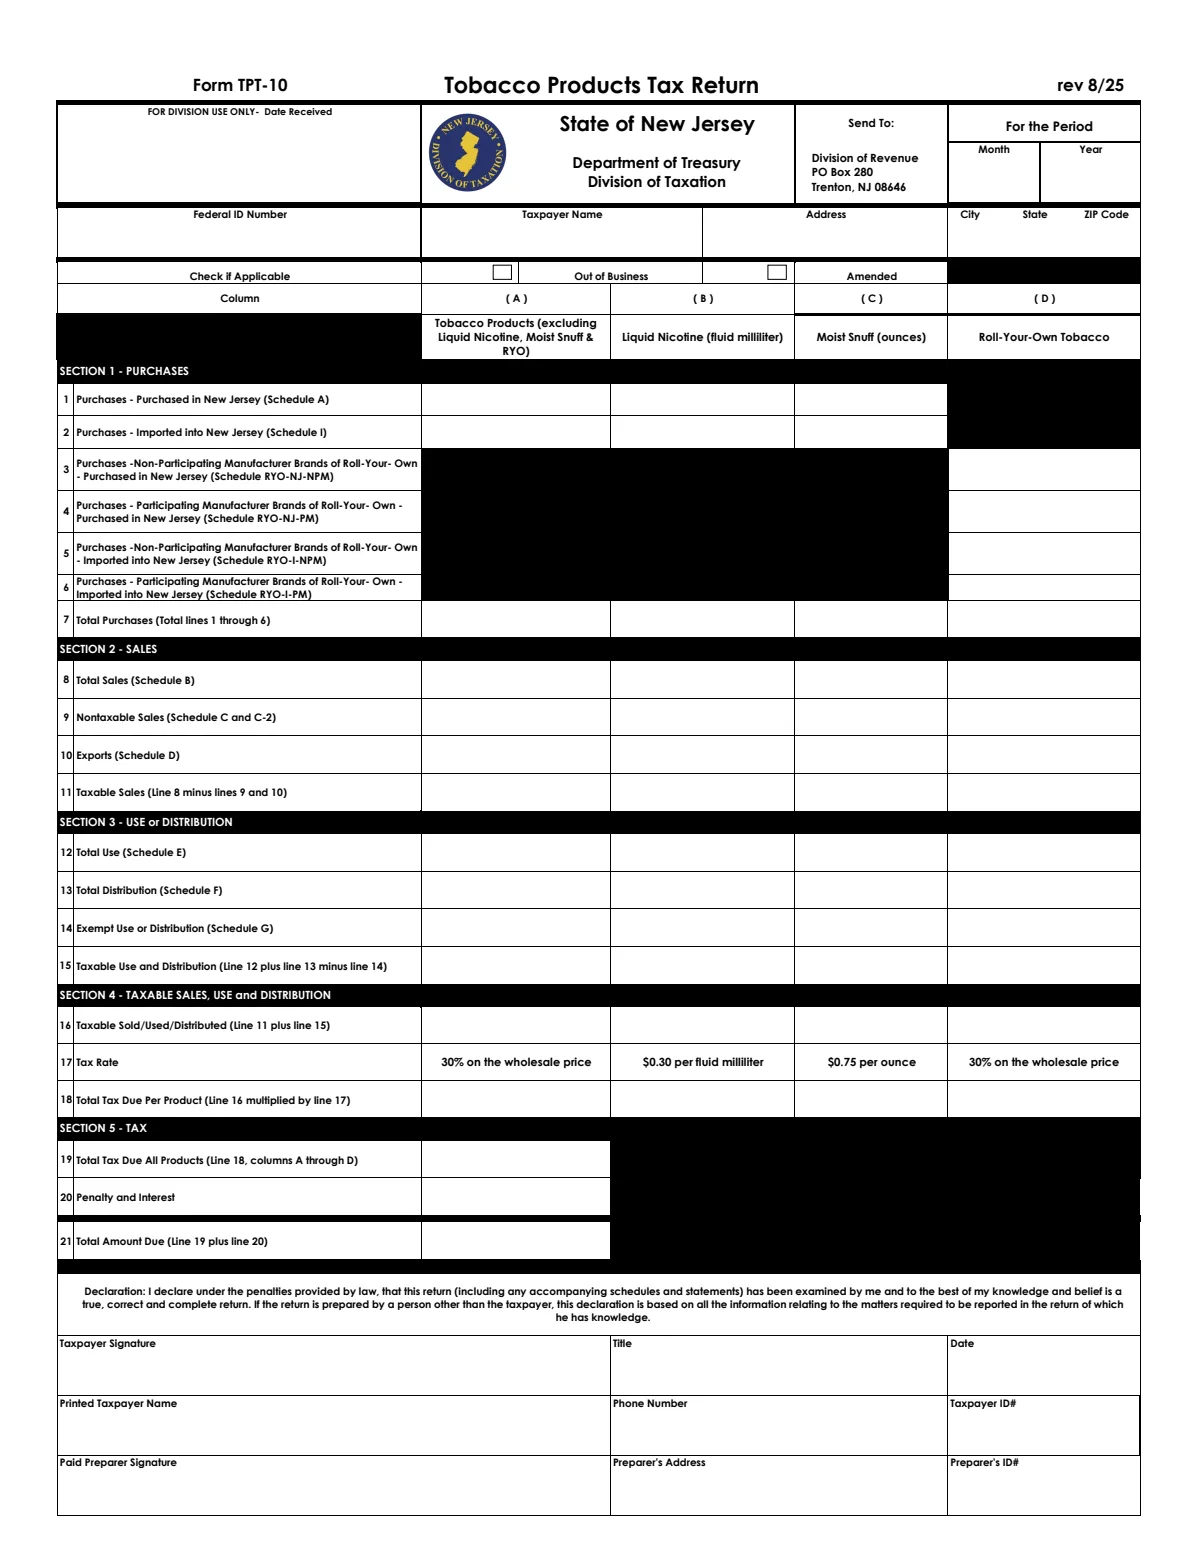
The header identifies the business and the month. The black cells on the form mark columns that a line does not use: lines 1 and 2 have no column D, and lines 3 to 6 have only column D.
| Line | Label | What goes there |
|---|---|---|
| Div-use | FOR DIVISION USE ONLY- Date Received | The Division's receipt stamp. Leave it blank. |
| Period | For the Period: Month, Year | The month the return covers. “All businesses that are registered for the Tobacco and Vapor Products Tax are required to file the monthly Tobacco Products Tax return, Form TPT-10 along with the applicable schedules, on the 20th day of the month following the end of the prior month.” |
| FEIN | Federal ID Number | The business's federal ID number, the same one it registered with. |
| Name | Taxpayer Name | The registered name. |
| Address | Address | The business's street address. |
| City | City, State, ZIP Code | City, state and ZIP. |
| Out-of-business | Check if Applicable: Out of Business | Check it on the final return when the business stops. |
| Amended | Check if Applicable: Amended | Check it when the return corrects one already filed. |
Lines 1 to 21
The return moves from purchases to the taxable total. Purchases in Section 1 are reported for the Division's matching; the tax itself is figured on what you sold, used or distributed taxably (Section 4) at the rates printed on line 17.
Form TPT-10 (rev 8/25) and its instructions.
| Line | Label | What goes there |
|---|---|---|
| 1 | Purchases: purchased in New Jersey (Schedule A) | From Schedule A (tobacco products purchased in New Jersey): column A the wholesale price of tobacco products, column B the fluid milliliters of liquid nicotine, column C the ounces of moist snuff. |
| 2 | Purchases: imported into New Jersey (Schedule I) | From Schedule I (tobacco products imported into New Jersey): the same three columns for product brought in from outside the state. |
| 3 | Non-participating manufacturer RYO purchased in NJ (Schedule RYO-NJ-NPM) | Column D only: the wholesale price of roll-your-own tobacco of non-participating manufacturer (NPM) brands bought in New Jersey, from Schedule RYO-NJ-NPM. Which brands are participating or non-participating is on the Attorney General's manufacturers directory. |
| 4 | Participating manufacturer RYO purchased in NJ (Schedule RYO-NJ-PM) | Column D: participating manufacturer (PM) brands of roll-your-own bought in New Jersey, from Schedule RYO-NJ-PM. |
| 5 | Non-participating manufacturer RYO imported into NJ (Schedule RYO-I-NPM) | Column D: NPM roll-your-own brands imported into New Jersey, from Schedule RYO-I-NPM. |
| 6 | Participating manufacturer RYO imported into NJ (Schedule RYO-I-PM) | Column D: PM roll-your-own brands imported into New Jersey, from Schedule RYO-I-PM. |
| 7 | Total purchases | Lines 1 and 2 added in columns A to C, and lines 3 to 6 added in column D. Purchases are reported but are not the tax base: the tax runs from sales, use and distribution below. |
| 8 | Total sales (Schedule B) | From Schedule B (tobacco products sold), all four columns: wholesale price, milliliters, ounces and roll-your-own wholesale price. |
| 9 | Nontaxable sales (Schedules C and C-2) | From Schedules C and C-2 (tobacco products sold in a nontaxable manner). |
| 10 | Exports (Schedule D) | From Schedule D (tobacco products exported). |
| 11 | Taxable sales | Line 8 minus lines 9 and 10, each column. |
| 12 | Total use (Schedule E) | From Schedule E (tobacco products used). |
| 13 | Total distribution (Schedule F) | From Schedule F (tobacco products distributed). |
| 14 | Exempt use or distribution (Schedule G) | From Schedule G (exempt use or distribution of tobacco products). |
| 15 | Taxable use and distribution | Line 12 plus line 13, minus line 14. |
| 16 | Taxable sold/used/distributed | Line 11 plus line 15: everything sold, used or distributed taxably, by column. |
| 17 | Tax rate | The printed rates, which match the Division's rate table as of November 2026: tobacco products at 30% of the wholesale price, liquid nicotine at $0.30 a fluid milliliter, moist snuff at “Moist snuff | Per ounce | $0.75”, and roll-your-own at 30% of the wholesale price. The liquid nicotine rate rose on Aug. 1, 2025: “Recent adoption of State law (P.L. 2025, c. 68) will increase tax on cigarettes, liquid nicotine, and container e-liquid on August 1, 2025.” |
| 18 | Total tax due per product | Line 16 times line 17 in each column. |
| 19 | Total Tax Due All Products (Line 18, columns A through D) | The four column taxes added. |
| 20 | Penalty and Interest | “Enter the total penalty and interest due on the return if filed or paid late.” The rates are Not listed in the saved sources. |
| 21 | Total Amount Due (Line 19 plus line 20) | What you pay. |
| Sign | Taxpayer Signature, Title, Date | Below the declaration: “I declare under the penalties provided by law, that this return (including any accompanying schedules and statements) has been examined by me”. |
| Printed | Printed Taxpayer Name, Phone Number, Taxpayer ID# | The signer's printed name, a phone number and the taxpayer ID. |
| Preparer | Paid Preparer Signature, Preparer's Address, Preparer's ID# | Completed by a paid preparer, whose declaration covers the information known to the preparer. |
What is not on TPT-10
- Cigarettes. They are outside this tax and are taxed through stamps; see the New Jersey excise tax page.
- Container e-liquid. New Jersey also taxes container e-liquid at “30% of the listed retail sale price of container e-liquid”, and retail sellers need a Vapor Business License. TPT-10 has no column for it (column B is liquid nicotine by the milliliter), and the return for container e-liquid is Not listed in the saved sources.
- The 2025 floor tax. Liquid nicotine on hand on Aug. 1, 2025 owed an extra $0.20 a milliliter on a separate return, the Tobacco Products Tax Floor Stocks Return, TPT-FL, due by Oct. 1, 2025.
- Nicotine pouches. A separate rate is Not listed in the saved pages.
How it connects
- New Jersey's cigarette, tobacco, vapor, fuel and alcohol taxes: New Jersey excise tax, tobacco section.
- Other states: cigarette tax by state and vapor tax by state. Other state tobacco returns: West Virginia TPT-709 and Wyoming Form 71.
- The federal tax on the same products: tobacco excise tax and TTB F 5000.24.
Questions filers ask
When is New Jersey Form TPT-10 due?
On the 20th day of the month after the report month, or the next business day when the 20th falls on a weekend or holiday.
What is New Jersey's tax rate on tobacco products?
30 percent of the wholesale price for tobacco products and roll-your-own tobacco, $0.30 per fluid milliliter of liquid nicotine and $0.75 per ounce of moist snuff, as printed on line 17 of the rev 8/25 form.
Are cigarettes reported on TPT-10?
No. Cigarettes are exempt from the Tobacco and Vapor Products Tax and are taxed through stamps.
Do I report purchases or sales?
Both. Section 1 reports purchases from the schedules; the tax is figured on sales, use and distribution, less nontaxable sales, exports and exempt use, in Sections 2 to 4.
What are the RYO lines?
Lines 3 to 6 split roll-your-own tobacco purchases by participating and non-participating manufacturer brands and by bought in New Jersey or imported, each from its own schedule, all in column D.